 Insights
The Goods Stay in Storage. Who Controls Their Release? What Digital Warehouse Receipts Change
Secro's November 2026 announcement puts digital warehouse receipts in the spotlight. For a lender, the useful question is how a receipt, financing agreement and warehouse release stay connected. Control of an electronic record, evidence of stored goods and permission to release them need separate examination.
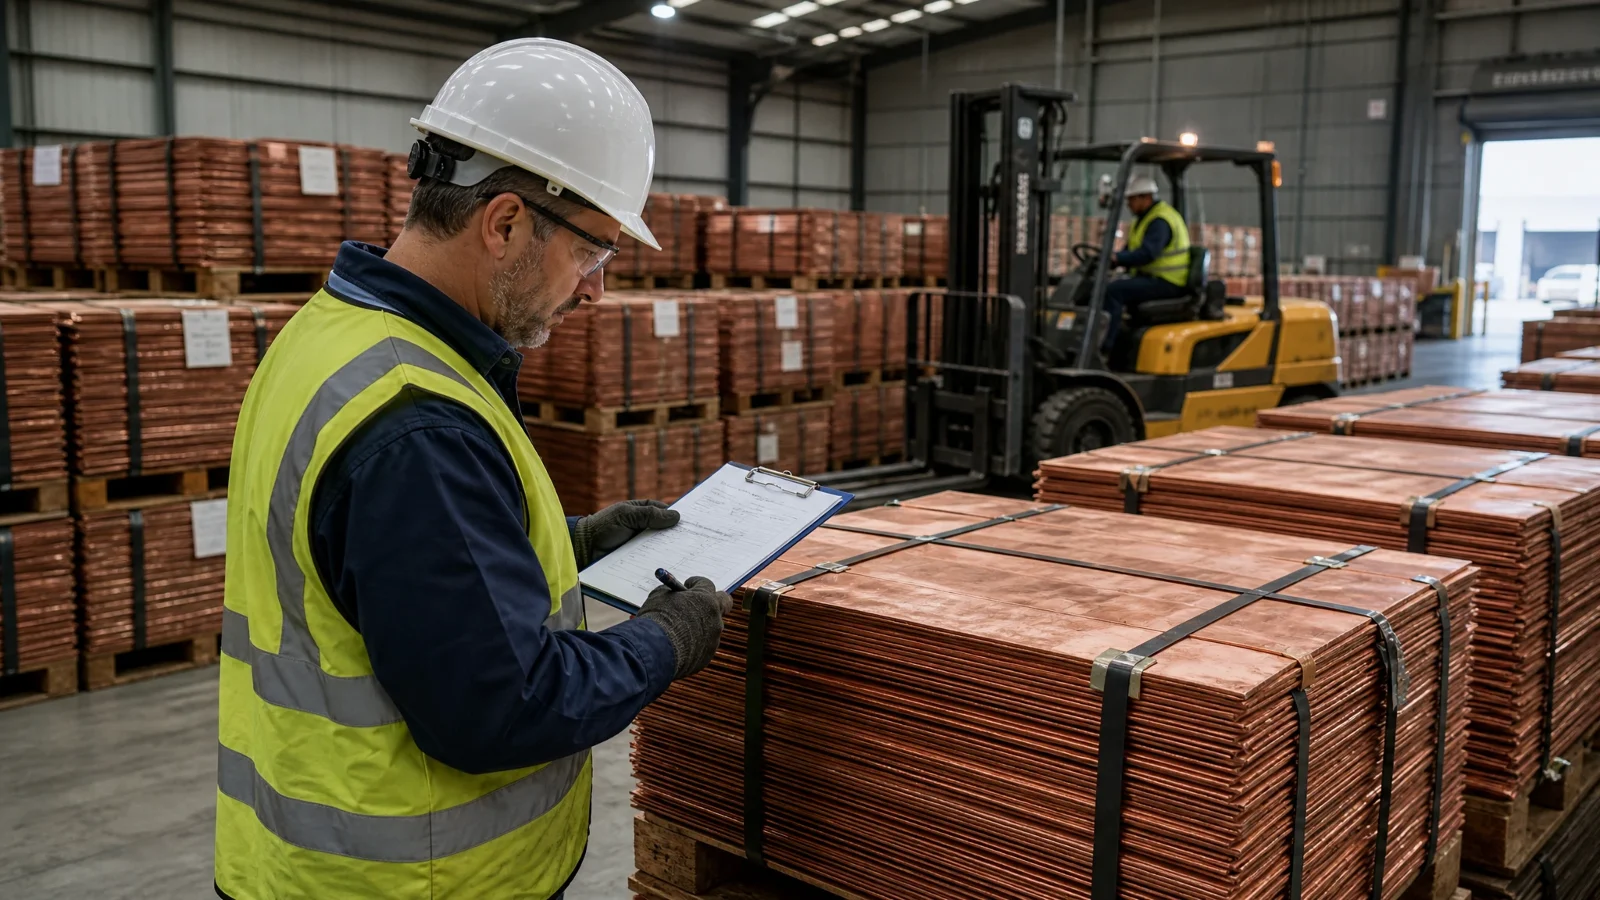
Goods can support financing without leaving the warehouse. The difficult part is establishing which goods a document represents, who controls the relevant record and who may authorize their release. That makes warehouse receipts a useful place to examine what digitisation changes in an otherwise physical business.
On 4 November 2026, Secro announced a Finance Innovation Award for its inventory-finance work. Its release describes tokenised warehouse receipts and holding certificates that can be issued, pledged, transferred, split and cancelled, and identifies the inventory-finance solution as a pilot with banking and trading partners. Those are company statements about the product and its stage, rather than independently measured results across the market. Secro's announcement
For a lender or trader, the commercial question is more specific than whether a receipt is a token. Can the parties keep the financing record aligned with the goods that remain available, especially when some stock is released? A reliable answer depends on the connection between the document, the warehouse operation and the financing terms.
A warehouse receipt connects a document to stored goods
UNCITRAL describes the purpose of the 2024 UNCITRAL–UNIDROIT Model Law on Warehouse Receipts as supporting transactions in stored goods, including their use as collateral. The framework covers paper and electronic receipts and addresses issuance, transfers, security rights and warehouse-operator obligations. It is a model for States to consider adopting, not proof that a particular transaction already has the same legal treatment everywhere. UNCITRAL's explanation of the model law
That gives a useful starting point for commercial review. Identify the warehouse operator, the depositor, the goods described and the relevant receipt. Then establish what the applicable documents and law say the holder or secured party may do. A storage confirmation, a negotiable receipt and a contractual promise should not be assumed to provide identical rights simply because each refers to the same stock.
The receipt's usefulness depends on that specificity. "Copper in storage" is insufficient if the financing concerns a particular lot, grade, quantity and location. A reviewer needs a way to connect the documentary description to the warehouse's records and the relevant agreement. If the description is incomplete or disputed, a digital format should preserve the question instead of making the uncertainty less visible.
| Relationship to establish | Evidence to examine | Question left open by the document alone |
|---|---|---|
| Warehouse and goods | Issuer, receipt reference and stock description | Does the described stock exist in the stated condition? |
| Receipt and holder | Applicable transfer or control record | What rights follow under the relevant law and terms? |
| Financing and security | The financing agreement and its identified collateral | Which obligations and release conditions apply? |
| Release and remaining stock | The authorized instruction and warehouse report | What was actually delivered and what remains? |
This table describes review questions, not a determination of title, priority or enforceability. The important point is that each relationship needs a source. A name or quantity repeated in several files does not establish that the files describe the same current position.
Electronic control solves a documentary problem
UNCITRAL's Model Law on Electronic Transferable Records uses reliable identification, control and integrity to describe functional equivalence with transferable paper instruments. Exclusive control plays the role that possession performs for paper. Its approach is technology-neutral and leaves the underlying substantive law in place. A token label, by itself, does not establish that these requirements or the applicable local rules are satisfied. UNCITRAL: electronic transferable records
The practical distinction is between having a readable copy and controlling the operative record. Several reviewers may legitimately see copies of a receipt while only a specified person has the relevant control. A review pack should make that distinction clear rather than treating access to an image or PDF as evidence of control.
It also needs to explain what happened to earlier versions. Where a paper receipt is replaced or an electronic record is changed, a reviewer needs a documented account of which record remains operative. That is a question about the actual process and its safeguards. It cannot be answered merely by observing that the newest file has a cryptographic signature.
Document integrity is valuable, but it is not a physical inspection. A reliable record of an assertion does not establish the goods' quality, the condition of a warehouse or the completeness of inventory reporting. Those are separate evidence questions. This is an analytical boundary between documentary control and physical verification, not an allegation about Secro or a named warehouse.
Partial release tests the connection to the financing
Consider a hypothetical receipt describing 100 tonnes of a commodity. A trader asks to release 20 tonnes for delivery to a customer. Subtracting 20 from 100 produces an arithmetic remainder, but it does not establish that the release is permitted, that the remaining stock has been verified or that the debt fell by the same proportion.
The reviewer needs the applicable financing terms and release authority. The warehouse needs an instruction it can associate with the correct goods and document. Afterwards, the recorded delivery and the remaining stock need to be connected to the relevant receipt history. These illustrative quantities do not describe a transaction reported by Secro.
- Identify the receipt, goods description and financing agreement that define the position.
- Establish the applicable release condition and the source-described authorized role.
- Record the instruction with its scope, quantity, date and supporting evidence.
- Retain the warehouse's reported delivery and the operative receipt or replacement references.
- Review remaining-stock and financing evidence separately, preserving differences and open questions.
The relationship between collateral and debt deserves particular care. A release may depend on repayment, substitute collateral, a permitted borrowing-base calculation or another agreed condition. Those are possible contractual structures, not terms established for the announced pilot. The governing agreement must supply the actual condition; a generic workflow should not invent it.
Nor is splitting a record the same as splitting the goods or creating two independent assets of unchanged size. A review needs to preserve the link to the earlier receipt, the quantities represented and the status of the superseded record. Otherwise, a history of valid documentary changes can become a misleading inventory total.
Judge a pilot by the operational questions it can answer
Secro's release claims faster partial releases and stronger controls over duplicate issuance and unauthorized delivery. The announcement does not provide a public, transaction-level dataset with which to verify those outcomes independently. A pilot can be worth following while its claimed benefits remain subject to evidence and the conditions of each deployment. The company's stated benefits and pilot status
For a prospective user, a useful evaluation would examine an actual completed example rather than only the interface. Which receipt and goods were involved? What condition authorized release? Who accepted the instruction? How were the remaining position and any exception reported? These questions can reveal commercial value without requiring a promise that every kind of fraud has become impossible.
| Measure to examine | What a useful result would distinguish |
|---|---|
| Release time | Instruction, authorization and physical delivery timestamps |
| Documentary continuity | Original, replacement, split and cancelled record references |
| Stock reporting | Reported quantity, reporting time and independent checks where applicable |
| Financing effect | The contractual basis for any repayment or collateral adjustment |
| Exceptions | Rejected, pending, corrected and uncertain outcomes |
UNIDROIT's project record places warehouse-receipt reform in the wider work on private-law rules and access to credit. It describes development alongside frameworks for secured transactions and electronic transferable records. That context explains why warehouse practice and financing law matter alongside technology; it does not certify a platform or establish a particular lender's security position. UNIDROIT's warehouse-receipts project
A more useful financing process would give the next reviewer a connected account of the goods, documentary control, release authority and resulting position. The stock may stay in the same building throughout much of the financing. What must remain inspectable is the chain of evidence explaining which goods support which obligation and what changes when a release occurs.