 Insights
The Loan Is Repaid. Is the Bitcoin Free? The Evidence Behind Collateral Release
Riot Platforms' September 2026 payoff shows why debt repayment, custody and release from a lender's security interest need separate records. Its changing bitcoin collateral balances also show why a dated quantity cannot be treated as the amount released months later. A useful review connects each event to its source, scope and effective date.
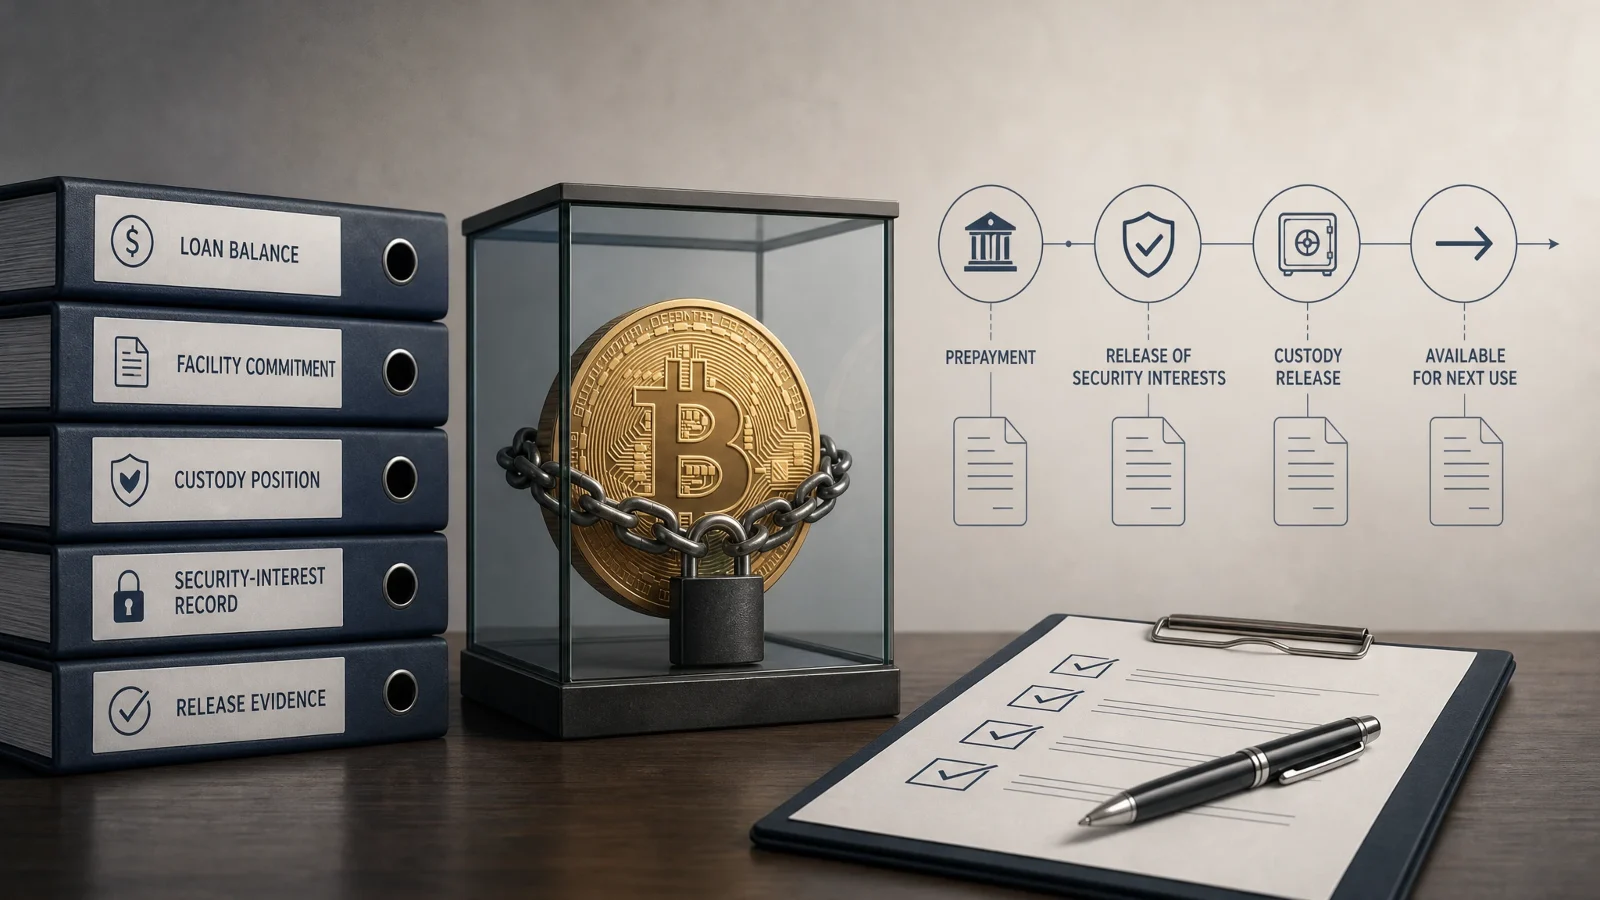
When a secured loan is repaid, a treasury team needs to know what it can do with the collateral next. A zero principal balance answers part of that question. It does not, by itself, establish which security interests have ended, whether a custody restriction has been removed or whether the same assets are available for another transaction. Those questions need their own evidence, even when the answers arrive on the same day.
Riot Platforms provides a useful case. In its Form 8-K dated 25 September 2026, the company reported full voluntary prepayment on 21 September, payment of accrued interest, discharge of its obligations, termination of its Coinbase Credit facility and commitment, and release of the security interests granted under the collateral documents. The filing describes an express release alongside payment. Riot's September Form 8-K, Item 1.02
The practical lesson is to preserve those facts separately. A payment record, a release statement and a custody statement may concern the same position, but each supports a different conclusion. Digital collateral makes the distinction visible because the asset can remain technically unchanged while the contractual rights around it change.
One facility, several different relationships
The facility provided up to $200 million of secured term-loan capacity. Riot's April disclosure named Coinbase Credit as lender, collateral agent and administrative agent, and identified Coinbase Custody Trust Company as custodian of financial assets including bitcoin, USDC and cash. The maximum facility amount describes capacity; it should not automatically be copied into a payment or current-balance field. Riot's April Form 8-K, Item 1.01
Different roles can belong to related organizations without becoming interchangeable. The custodian's identity explains where the position is administered. The lender and collateral agent have roles under the financing documents. A review should retain the legal entity and source for each role rather than combining them into a single reference to Coinbase.
| Record | Question it answers | What it does not establish on its own |
|---|---|---|
| Loan balance | What principal is reported as outstanding at a given time? | That interest, fees or other secured obligations are discharged. |
| Facility commitment | Is further borrowing still available under the facility? | That an amount has actually been drawn. |
| Custody position | Which account and custodian hold or administer the reported position? | That it is free from security interests or withdrawal restrictions. |
| Security-interest record | Which secured party claims rights over which collateral, under which document? | That all other claims or restrictions have been identified. |
| Release evidence | Which defined rights were released, with what scope and effective date? | That the asset is globally unencumbered or immediately transferable. |
This separation also helps when a facility has no outstanding principal but remains available for future drawings. Conversely, a facility can terminate while some closing steps remain unresolved. Neither possibility should be turned into an assertion about Riot; they explain why a reusable review process needs distinct fields rather than one closed/open switch.
The collateral quantity changed before final payoff
Riot's disclosures show why a collateral balance needs a date. Its 2025 annual report recorded 3,977 BTC pledged at year-end and a further 1,825 BTC pledged in February 2026 following a decline in bitcoin prices. Its first-quarter report then described an April release, while the second-quarter report supplied another quarter-end position. These are observations and events along a changing record, rather than competing answers to a timeless question.
| Date or event | Reported pledged quantity | Source and interpretation |
|---|---|---|
| 31 December 2025 | 3,977 BTC | Year-end position in the 2025 Form 10-K, Note 12. |
| February 2026 top-up | 5,802 BTC | The same annual report describes an additional 1,825 BTC pledged after prices fell. |
| April 2026 release | 4,258 BTC | The Q1 Form 10-Q, Note 11 reports 1,544 BTC released after quarter-end. |
| 30 June 2026 | 5,821 BTC | The Q2 Form 10-Q, Note 11 gives a new dated collateral position. |
| 21 September 2026 payoff | Not specified in the payoff filing | The September Form 8-K reports release of the defined security interests without quantifying the bitcoin then pledged. |
The April number is a subsequent-event disclosure in a report for the quarter ended 31 March. Its reporting period must not be mistaken for the release date. Similarly, the June balance cannot be carried forward almost three months and relabelled as the amount released at final payoff. Where an event and a quantity come from different dates, the record needs to preserve that gap.
The June report identifies 5,821 BTC pledged at 30 June 2026. That is a position at a specified date.
The September filing reports release of the facility's security interests on 21 September. It does not specify the bitcoin quantity pledged on that date.
The figures are drawn from the Q2 and September filings linked above. A careful reviewer can retain both statements without inventing the missing bridge between them. The same discipline applies to collateral substitutions, repayments, sales and new pledges in any secured portfolio.
LTV depends on the contract's inputs
Loan-to-value, or LTV, compares an exposure with an eligible collateral value. If the loan balance is unchanged and the collateral price falls, the ratio can rise. Adding collateral can restore the ratio without any new borrowing. A changing pledged quantity therefore does not necessarily imply a changing debt balance.
Riot's agreement defines Actual LTV using outstanding principal and its defined Prevailing Market Value. Bitcoin pricing references transactions on a platform selected by the administrative agent and regulated by the New York Department of Financial Services; other collateral receives zero value under that definition. The agreement also sets margin-demand and conditional release procedures. Credit agreement, Section 1.01 and Section 2.06
That valuation distinction matters: an asset may fall within the security package without contributing to the contractual LTV denominator. Adding the market values of everything in custody would answer a different question. A useful calculation record consequently needs the governing definition, eligible assets, quantity and price timestamps, source of prices and person or system responsible for the calculation.
It also needs to distinguish a reported contractual result from an analyst's illustration. Public market data can explain the direction of a change, but it does not establish that a notice was valid, a contractual threshold was met or a release became available. Those conclusions depend on the applicable terms and evidence at the relevant time.
A release request is a stage, not the outcome
Under Riot's margin-release provisions, the threshold must be met for the required period, with no continuing blocking event, before a request proceeds to a fresh calculation and custodian instruction. Section 2.06(c) links release of the relevant liens to the specified collateral transfer. A submitted request is therefore different from a completed release. Credit agreement, Section 2.06(b)-(c)
A general review process should retain the requested amount, decision, instruction and completion evidence as separate items. A rejection or a changed calculation should remain visible rather than disappearing behind the latest status. The exact legal and operational sequence will vary by agreement; a workflow diagram cannot establish it for another transaction.
- Identify the facility, collateral position and governing release provisions.
- Record the request, stated conditions and any required calculation or decision.
- Retain the agent instruction and evidence of the relevant custody action.
- Identify the document and effective date supporting release of the defined security interest.
- Review remaining restrictions before describing the position as available for another use.
This is an evidence-review sequence, not an instruction to execute a transfer. It helps an operator avoid marking collateral released merely because a borrower asked for it, a payment arrived or an internal ticket was closed.
What does “free” actually mean?
The narrow claim that a defined lender's security interest has been released is different from the broader claim that an asset is unrestricted. A position might still be subject to another pledge, a legal hold, a custody condition or an internal reservation. The label free is useful only when its scope, date and evidential limits are clear.
Custody and legal state also need separate treatment. An unchanged account or blockchain address does not prove that contractual rights are unchanged. A transfer does not, on its own, prove that a security interest has ended. A blockchain record can contribute transaction evidence, while the relevant agreements and authoritative records address different questions about rights and authority.
Riot's Q2 report classified the pledged bitcoin as restricted bitcoin. That accounting presentation records a reporting-date position; it should not be treated as a substitute for release evidence or a current withdrawal confirmation. Nor does a later release statement, by itself, tell a reviewer the complete post-release custody path. Q2 Form 10-Q, Notes 5 and 11
For a hypothetical account holding 10,000 BTC, a reported pledge of 5,000 BTC does not establish that the other 5,000 BTC are available. That conclusion also requires a defined account scope, a current balance and knowledge of other restrictions. If two obligations refer to overlapping collateral, simply subtracting both stated quantities can double-count the restriction. Any derived available balance should expose those assumptions and unresolved overlaps.
Refinancing makes the time dimension especially important. A release from one lender can be followed by a new pledge to another. A continuous appearance of restriction can conceal a significant change in creditor, priority and source documents. Conversely, a brief release event should not be presented as permanent freedom from encumbrance.
Build a review record that preserves the unanswered questions
The useful starting point is a source-backed position and event record. Each assertion should carry the facility or account it concerns, who supplied it, its effective or as-of date, the document date and its review status. Unknown values should stay unknown rather than being copied from an earlier report to make the record look complete.
| Review area | Information to retain | Question to resolve |
|---|---|---|
| Facility and payment | Borrower, lender, facility reference, commitment, principal, interest, fees and payoff evidence. | Which obligations ended, and can further amounts still be drawn? |
| Collateral position | Asset, account, custodian, reported quantity, quantity date and allocation to the facility. | Is the quantity current and does it overlap another allocation? |
| Rights and control | Source-described parties, security and control documents, scope, claimed priority and supporting references. | What is reported, and what requires qualified legal review? |
| Valuation and margin | Contract definition, eligible value, price source, calculation time, notices, deadlines and reported responses. | Is this an authoritative calculation, a source assertion or an illustration? |
| Release and availability | Request, decision, instruction, completion evidence, released rights, effective date and remaining restrictions. | What supports the specific availability claim being made now? |
| History and correction | Earlier positions, top-ups, releases, substitutions, refinancings and the reasons for corrections. | Can another reviewer reconstruct what was known at the relevant time? |
This organization helps distinguish a performing pledge from a default, an available remedy from active enforcement, and an approved release from its completion. It can also make missing notices and stale quantities easier to spot. It does not turn a document collection into an authoritative registry of all liens or a complete live custody ledger.
AI can assist by proposing source-linked parties, dates and statements for human review. More ambitious uses, such as reconstructing every allocation or detecting double pledges across systems, require a defined data model, authoritative inputs and evidence of completeness. They should be evaluated as separate capabilities rather than assumed to follow from document extraction. Legal effectiveness, priority and permission to repledge remain decisions for the appropriate authorized reviewers.
For the next treasury or credit review, the decisive question is specific: which rights over this identified collateral ended, when did they end, and what evidence supports the proposed next use? A well-kept record makes both the answer and its remaining limits visible.
Sources
- Riot Platforms: September 2026 Form 8-K, full prepayment and release.
- Riot Platforms: April 2026 Form 8-K, amended facility and named parties.
- Second Amended and Restated Credit Agreement: definitions and collateral adjustments.
- 2025 Form 10-K: year-end collateral and February 2026 top-up.
- Q1 2026 Form 10-Q: April collateral release disclosed after quarter-end.
- Q2 2026 Form 10-Q: pledged and restricted bitcoin at 30 June 2026.