 Insights
When a Loan Portfolio Becomes Central-Bank Collateral: Eligibility Is an Asset State
British banks are increasingly mobilising less-liquid credit assets through the Bank of England’s Sterling Monetary Framework. Level C collateral held by the Bank more than doubled over the year to £17.8 billion, while the eligible universe includes residential mortgages, consumer and auto loans, asset finance, corporate and SME loans and other loan portfolios. The deeper lesson is that a loan does not become central-bank collateral merely because it exists: eligibility depends on portfolio...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
Owning a billion pounds of performing loans does not necessarily give a bank a billion pounds of immediately usable central-bank collateral. Borrowers may be paying, agreements may be signed and balances recorded, while the evidence, legal assurance and operational preparation required for mobilisation remain incomplete. The distinction is important in the United Kingdom, where the cited reporting describes growing use of less-liquid collateral. A loan's economic value and its readiness for a particular liquidity operation answer different questions.
On 2 September 2026, Reuters reported that British banks were making greater use of Level C collateral in the Bank of England’s Indexed Long-Term Repo, or ILTR, operations. The stock of Level C collateral held by the Bank had risen to approximately £17.8 billion, compared with £8.7 billion a year earlier. On 18 August alone, banks pledged £1.9 billion of Level C assets, the highest weekly amount reported since March 2020. Reuters: Banks rush to swap higher-risk credit assets for Bank of England cash
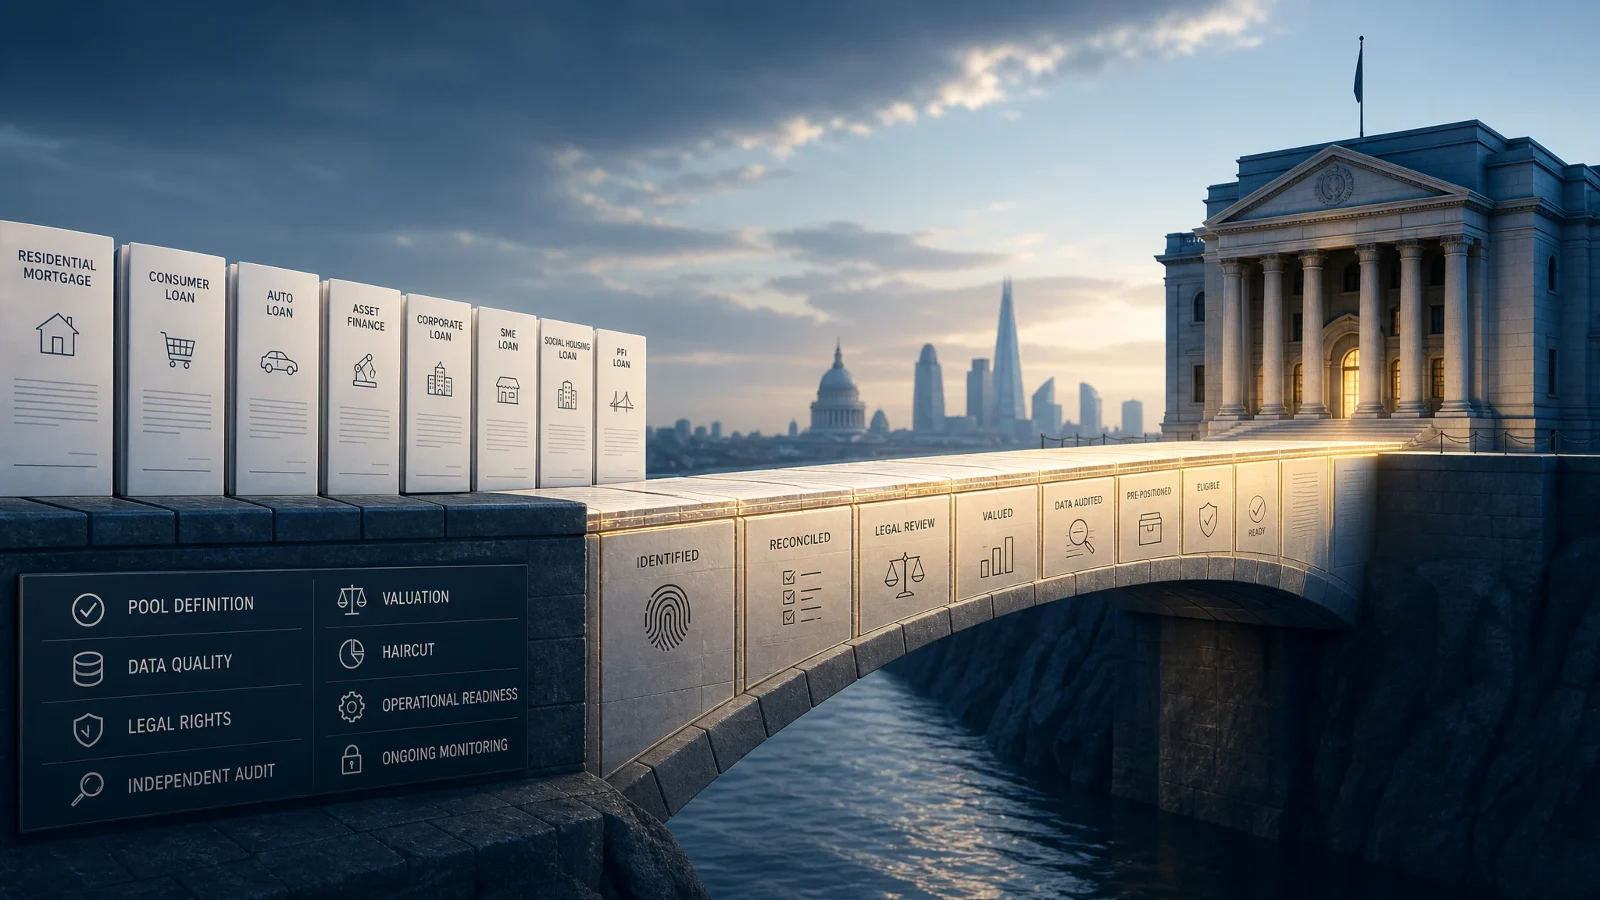
The assets involved are more interesting than the headline. Level C is the Bank’s least-liquid collateral category and can include securitisations, own-name securities and portfolios of loans. The Bank of England’s current eligible-collateral framework includes loan-level data templates for:
- residential mortgages;
- consumer loans;
- asset-finance loans;
- auto loans;
- corporate loans;
- SME loans;
- social-housing loans; and
- private-finance-initiative loans.
Bank of England: Eligible collateral This turns a familiar banking asset into something more operationally demanding. A portfolio of SME loans may be valuable. A portfolio of SME loans that has been identified, reconciled, legally reviewed, audited, valued, pre-positioned and kept operationally ready can become something else: mobilisable central-bank collateral. That suggests an important DaDepo principle:
Collateral eligibility is not an intrinsic property of a loan. It is a state created by evidence, legal rights, data quality and operational readiness.
Establish eligibility at loan and pool level
Start with one ordinary bank loan. The bank may know:
- Borrower
- Principal
- Interest rate
- Maturity
- Payment status
- Security
That can be enough to manage the credit. A central bank needs a different level of assurance. The Bank of England says its pre-positioning process is intended to ensure it can:
- efficiently value the assets;
- effectively risk-manage them; and
- confidently take legal ownership if necessary.
Bank of England: Guide to Pre-positioning Loan Collateral That means the asset needs to answer more than: Does the borrower owe money? It must also answer: Can this exact loan be transferred, valued and enforced within the collateral framework? Those are different questions.
A loan can exist in the bank’s balance sheet without satisfying the Bank of England’s eligibility criteria. For Level C loan pools, eligibility can depend on factors such as:
- asset type;
- borrower location;
- governing law;
- loan seasoning;
- residual maturity;
- concentration;
- documentation;
- payment status; and
- other product-specific requirements.
For example, the Bank’s guidance sets minimum seasoning periods for several loan classes. Residential mortgages generally require at least two months of seasoning. Corporate and SME loans generally require three months. Asset-finance, auto and consumer loans generally require at least one payment and one month of seasoning. The same loan therefore moves through states:
Originated → Seasoning → Potentially eligible.
The passage of time can change eligibility without changing the loan agreement. That is an asset-state transition.
The Bank’s guidance also makes an important distinction around non-performing loans. Loans already in arrears or default when a portfolio is being pre-positioned or topped up must not be included. But a loan that defaults after it has entered a pre-positioned pool is not simply erased from the record. The Bank requires the default to continue to be reported in the regular data tape with the appropriate status.
Bank of England: Additional Guidance for Loan Collateral This is exactly what a proper asset lifecycle should do. The loan identity remains. Its state changes. A simplistic system might say: Eligible: Yes and later: Eligible: No. A stronger system records:
| Record item | Value or state |
|---|---|
| Entered pool | 2026-04-01 |
| Status at entry | Performing |
| Default event | 2026-08-15 |
| Current status | Default |
| Reported in collateral tape | Yes |
The event matters.
Keep pool membership and churn effective-dated
Central-bank collateralisation is not always performed one loan at a time. The Bank accepts pools of loans. That creates a hierarchy:
Individual loan → Sub-portfolio → Collateral pool → Central-bank collateral position.
The pool has characteristics that no individual loan has. For example:
- total balance;
- number of borrowers;
- concentration;
- geography;
- vintage;
- product mix;
- default rate;
- expected cash flow; and
- haircut.
The Bank’s guidance prefers granular and diversified pools and sets concentration tests, including minimum effective borrower counts and limits on exposure to individual borrowers. That means: Loan eligible does not automatically imply: Pool eligible. Portfolio composition becomes part of the collateral state.
Suppose a bank pre-positions 20,000 residential mortgages. Over time:
- borrowers repay;
- mortgages refinance;
- loans default;
- properties are sold;
- new mortgages are originated;
- loans are added; and
- other loans are removed.
The pool therefore changes continuously. A useful collateral record might look like:
- Pool ID: RM-UK-004
- 30 June
- Loans: 20,000
- Balance: £3.2bn
- 31 July
- Loans removed: 412
- Loans added: 630
- Balance: £3.28bn
- 31 August
- Loans defaulted since pre-positioning: 51
- Current balance: £3.24bn
The pool is not a static file. It is a changing population of assets.
The Bank of England’s management guidance explicitly recognises this. Once a loan pool is pre-positioned, participants must continue providing data and maintaining the pool. A significant level of portfolio turnover, or churn, can trigger a new data audit. Material changes to IT systems or the way loan-level data is produced can also trigger additional audit work. Material changes to standard-form loan documentation or terms and conditions can trigger a new legal review.
Bank of England: Guide to the Management of Loan Collateral This means collateral readiness can deteriorate even if credit performance is unchanged. A portfolio can contain exactly the same type of performing loans and still require renewed assurance because: Data system changed or Documentation changed. Eligibility is operational as well as economic.
Treat data and legal assurance as separate controls
The Bank requires third-party data audits for loan portfolios during the pre-positioning process. The purpose is not merely to check arithmetic. The Bank says the audit is intended to verify:
- the existence of the loans; and
- the quality and ability of the participant’s systems and processes to produce accurate data.
For residential mortgages, audit procedures can require the unique:
- loan identifier;
- borrower identifier; and
- property identifier
to agree with the primary system of record. Borrower names can be checked against original applications, offers, valuations and registered legal charges. For SME loans, borrower names, identifiers and other fields are similarly reconciled to source systems and documentation. Bank of England: Data audit AUPs and results tables That is a strong signal about institutional asset infrastructure.
The central bank does not merely need a portfolio total. It needs confidence that the individual assets represented in the tape actually exist and are correctly described.
Private-credit markets frequently treat a data tape as a reporting output. Central-bank collateral shows why it can be more important. A data tape can determine:
- which loans are included;
- which loans are excluded;
- which value is used;
- how the pool is modelled;
- which haircut is applied; and
- how much liquidity can ultimately be drawn.
If a field is wrong, the consequences are not merely cosmetic. The Bank may:
- remove specific loans;
- apply additional haircuts; or
- deem the pool ineligible.
Data quality can therefore change drawing capacity. This is the point where asset data becomes liquidity infrastructure.
A portfolio can have excellent data and still be legally unsuitable. The Bank requires a separate legal due-diligence process. External counsel may need to review:
- standard-form agreements;
- document variants;
- governing law;
- transfer mechanisms;
- signatures;
- restrictions;
- registered charges; and
- other terms relevant to legal enforceability.
The objective is to ensure that the Bank can take legal ownership of the assets if required. This creates two separate assurance states: Data assurance and Legal transferability / enforceability assurance. Neither should be represented by a generic: Verified: Yes.
Even inside the United Kingdom, legal mechanics can differ. The Bank’s pre-positioning guidance notes that loans governed by Scottish law must be held in a separate pool from loans written under the laws of England, Wales and Northern Ireland because the legal transfer mechanisms differ. That is a powerful example of why portfolio identity needs legal context. Two otherwise similar SME loans can have:
- Same borrower type
- Same coupon
- Same maturity
- Same credit quality
and still need different collateral treatment because of governing law. A global private-asset platform should expect this kind of fragmentation.
Distinguish pre-positioning from encumbrance
This distinction is central. A bank may pre-position collateral with the Bank of England so it is ready to use. That does not necessarily mean the assets are already legally encumbered in an outstanding central-bank transaction. The Bank’s collateral-management guidance distinguishes the process of keeping assets ready from the process of legally encumbering and unencumbering them when used for a drawing. That suggests several separate states:
Owned by bank → Eligible → Pre-positioned → Available → Encumbered to central bank → Released / unencumbered.
These states should never be collapsed into one field called: Collateral: Yes.
The same loan cannot be freely used in multiple places at the same time if legal rights conflict. A bank therefore needs to know:
- is the loan already pledged;
- is it inside a securitisation;
- is another lender secured over it;
- is it available for central-bank use;
- when did an encumbrance begin; and
- when was it released?
A robust asset record would preserve:
- Encumbrance type
- Secured party
- Effective date
- Release date
- Amount secured
- Source document
This is relevant far beyond central banks. It is one of the foundations of any collateral marketplace.
The Bank encourages participants to prepare collateral in advance. Pre-positioning can involve:
- building the data tape;
- completing due-diligence questionnaires;
- site visits;
- data audit;
- legal review;
- risk assessment; and
- operational testing.
The Bank’s guide shows that the full process for a new portfolio can take months, with legal review potentially taking substantially longer than data preparation. That means the bank cannot wait for a liquidity event and then decide:
- We have loans.
- Let us use them tomorrow.
Liquidity readiness has to be built before stress. That is a useful lesson for all private assets.
A mortgage loan is one asset. A portfolio of mortgages is another analytical object. A central-bank-ready portfolio adds another layer:
Loan assets + Pool definition + Eligibility evidence + Data audit + Legal review + Valuation + Haircut + Operational readiness.
The result is not a new legal loan. It is a new financing state of the existing portfolio.
Has been prepared for the relevant collateral process, with the required evidence and operational steps. Preparation does not itself mean that the assets currently secure a borrowing.
Is subject to the relevant pledge or other collateral relationship for a transaction. Amount, scope, effective time, release and any reuse limits need their own evidence.
Separate asset value, drawing value and market liquidity
Collateral value is not equal to liquidity value. Suppose a portfolio has a current balance of £1.0bn. The Bank applies a haircut. The collateral supports less than £1.0 billion of central-bank credit. For Level C loan collateral, the Bank calculates haircuts for each pool individually, reflecting the specific risk characteristics of the portfolio. Bank of England Market Operations Guide: Our tools
This means one pool can have several simultaneous values:
- Outstanding loan balance
- Accounting value
- Economic value
- Central-bank collateral value
- Haircut-adjusted drawing value
Those are not interchangeable.
The haircut can depend on the current portfolio. If the pool changes, risk changes. If concentration rises, the haircut can change. If credit quality deteriorates, risk treatment can change. If data quality is insufficient, loans can be removed or additional haircuts applied. A good proposed evidence record therefore needs:
- Haircut
- As-of date
- Method
- Authority
- Pool version
A number without its effective date is incomplete.
The increase in Level C usage also sits inside a larger monetary-operating transition. The Bank is moving toward a more repo-led, demand-driven framework for supplying central-bank reserves. Its 2025 recalibration increased the size of ILTR operations and explicitly reserved capacity for less-liquid Level B and Level C collateral. The Bank said it expected Level C reserves in the ILTR to be supplied at approximately 20 to 40 basis points over Bank Rate, depending on auction conditions. Bank of England: Recalibration of the Indexed Long-Term Repo Operation
This gives less-liquid bank assets a direct liquidity role. The assets do not become liquid in a public market. They become mobilisable within central-bank infrastructure. That is an important difference.
A private SME loan may be difficult to sell. There may be:
- no exchange;
- no continuous price;
- limited buyers;
- bespoke documentation; and
- significant settlement friction.
But if it is accepted within a collateral framework, the bank can use it to obtain liquidity without selling it. That creates another useful distinction:
Market liquidity and collateral liquidity are different.
An asset can be illiquid in the market and still be highly useful to a balance-sheet manager. This is a major reason collateral infrastructure matters.
Two banks can own economically similar loan books. Bank A has:
- inconsistent identifiers;
- incomplete documentation;
- fragmented systems;
- uncertain transferability; and
- no pre-positioned collateral pool.
Bank B has:
- reconciled loan-level data;
- clear legal documentation;
- verified ownership;
- identified security;
- a maintained collateral pool;
- current audit;
- current legal review; and
- central-bank operational readiness.
The credit assets may look similar. Their liquidity utility is not. Asset quality includes the quality of the infrastructure around the asset.
A proposed collateral record that stays current
As a proposed direction for DaDepo, this use case suggests a clear hierarchy.
| Record layer | Information to retain |
|---|---|
| Individual loan | loan identifier; borrower identifier; borrower; originator; current holder; original principal; current balance; interest; maturity; payment status; arrears; default status; governing law; source agreement. |
Security
Where applicable:
- property or financed asset;
- property identifier;
- charge;
- priority;
- valuation;
- valuation date;
- registration;
- guarantor; and
- release status.
| Record layer | Information to retain |
|---|---|
| Eligibility | eligible asset class; seasoning; borrower location; maturity eligibility; arrears eligibility; concentration attributes; documentation status; eligibility exceptions. |
| Pool membership | pool ID; inclusion date; removal date; reason for removal; sub-portfolio; pool balance; pool version. |
| Assurance | data-audit date; audit provider; audit outcome; legal-review date; legal adviser; legal-review status; open exceptions; remediation. |
| Collateral state | pre-positioned; available; encumbered; secured party; encumbrance date; release date; collateral value; haircut; drawing value. |
| Central-bank transaction | facility; operation date; amount drawn; collateral pool; settlement date; maturity; price or spread; release status. |
| Provenance | core banking system; original loan document; security registry; audit file; legal opinion; valuation; Bank of England reporting tape; reviewer; last updated time. |
This is not merely a loan database. It is a collateral-readiness system.
Loan servicing can change eligibility and valuation. Relevant events include:
- payment received;
- partial prepayment;
- arrears;
- default;
- refinance;
- security release;
- property sale;
- borrower insolvency;
- loan amendment;
- maturity extension; and
- full repayment.
Those servicing events should feed the collateral state. A portfolio cannot remain current if the central-bank tape is disconnected from the servicing system.
Suppose a bank changes its standard SME loan agreement. The commercial team sees: New documentation version. The collateral-management team may need to see: Potential legal-review trigger. The Bank’s guidance specifically identifies material changes to standard documentation or terms and conditions as a reason legal review may need to be repeated. This is another reason asset-state events should propagate across systems. One amendment can affect:
Loan origination → Legal documentation → Collateral eligibility → Liquidity readiness.
The same is true for IT. A migration from one servicing platform to another may not change the loans economically. It can still affect assurance. If data production methods materially change, the Bank may require a new audit. That means: Technology migration can be a collateral-state event. This is unusually important. It shows that a financial asset’s usability depends partly on the information system that describes it.
AI preparation and DaDepo's limited role
The following AI uses describe proposed assistance within this evidence model. They do not establish that DaDepo currently automates these workflows. Extraction and inconsistency flags would remain suggestions for review, not legal, credit, compliance or valuation decisions.
AI can help with:
- document classification;
- loan-field extraction;
- borrower-name reconciliation;
- property-address matching;
- security-document detection;
- maturity extraction;
- arrears identification;
- duplicate detection; and
- data-tape preparation.
Across a large portfolio, AI can flag:
- loans missing original agreements;
- borrower names inconsistent with legal charges;
- property identifiers that do not match;
- loans that appear in multiple pools;
- loans already encumbered elsewhere;
- loans past eligibility criteria; or
- documentation versions requiring legal review.
That is valuable. AI should not independently decide:
- that a loan is legally transferable;
- that security is perfected;
- that the Bank of England will accept a loan;
- that a haircut is correct;
- that an audit exception is immaterial; or
- that collateral may safely be pledged.
Those are institutional and legal decisions.
DaDepo's supported contribution is private intake of supported documents and preparation of a draft for user review. Its Parties and contractual roles evidence table can record the party, specific contract, source-described role, document and clause reference, relevant source-stated date and review status. Suggested rows require the user's review and confirmation. The wider relationship models, automated monitoring, reconciliation and decision workflows discussed here are proposed capabilities, not a description of existing DaDepo functionality.
DaDepo does not need to become a central bank or collateral agent. The relevant opportunity is upstream. A private loan portfolio can be represented as:
Loan → Current state → Pool → Eligibility evidence → Legal assurance → Pre-positioned collateral → Encumbrance → Liquidity transaction.
A proposed DaDepo extension could help preserve the evidence and lifecycle around those transitions. That could create a cleaner foundation for:
- treasury;
- collateral management;
- securitisation;
- private-credit portfolio reporting;
- refinancing;
- loan sales;
- central-bank preparation; and
- other secured-funding workflows.
The important point is not that every DaDepo asset should become central-bank collateral. It is that financeability depends on state.
Creating or reviewing a loan or loan-pool Asset Passport does not mean that DaDepo has:
- determined Bank of England eligibility;
- pre-positioned collateral;
- completed a regulatory data audit;
- completed legal due diligence;
- issued a legal opinion;
- valued the collateral;
- calculated an official haircut;
- verified security perfection;
- established legal transferability;
- encumbered assets;
- obtained central-bank liquidity;
- operated a central-bank facility;
- serviced the loans;
- provided lending; or
- provided legal, regulatory, audit, treasury, collateral-management, accounting, tax, investment, credit-rating, underwriting or valuation advice.
Important: DaDepo provides technology and information tools. It does not provide legal, financial, regulatory, audit, central-bank, treasury, collateral-management, lending, servicing, credit-rating, underwriting or valuation advice or services unless a specific service is expressly identified and lawfully provided. Central-bank collateral eligibility, valuation, haircuts, pre-positioning and operational requirements are determined by the relevant central bank and can change over time.
Review questions for central-bank collateral
Before a loan portfolio is described as ready for secured liquidity, ask:
- Asset identity: Can every loan be uniquely identified?
- Borrower identity: Is each borrower reconciled to the authoritative system and documents?
- Ownership: Does the institution legally own the loans it proposes to pledge?
- Security: Are relevant charges, mortgages or financed assets correctly linked?
- Eligibility: Does each loan satisfy the current asset-specific criteria?
- Seasoning: Has the required minimum period elapsed?
- Performance: Are arrears and default states current?
- Governing law: Are jurisdictional differences reflected in pool structure?
- Pool composition: Is the pool sufficiently granular and diversified?
- Data tape: Can all required fields be generated accurately and repeatedly?
- Audit: Has required third-party data assurance been completed?
- Legal review: Has required legal due diligence been completed?
- Exceptions: Are failed audit tests and legal exceptions visible?
- Pre-positioning: Has the portfolio completed the operational preparation process?
- Encumbrance: Is the asset currently free to be pledged?
- Haircut: What haircut applies to the current pool and as of what date?
- Drawing value: How much liquidity does the pool support after haircut?
- Churn: Has portfolio turnover triggered renewed assurance requirements?
- Change control: Have system or documentation changes triggered a new review?
- Provenance: Can every material field be traced to source systems, documents, audits and legal evidence?
If a bank knows what its loans are worth but cannot prove which loans it owns, which are transferable and which are free to pledge, it does not yet have mobilisable collateral.
Eligibility belongs in the asset lifecycle
The Bank of England’s Level C framework makes a broader private-market principle unusually visible. A loan is not only:
Borrower + Principal + Interest + Maturity.
It can also be:
- Eligible
- Pre-positioned
- Available
- Encumbered
- Haircut-adjusted
- Mobilised
- Released
Those states matter because they determine what the asset can do. A portfolio may be illiquid in the secondary market but highly useful for funding. A performing loan may be economically sound but operationally unusable as collateral. A legally valid portfolio may lose readiness if its data process changes. A pre-positioned pool may later contain defaults. A current haircut may change as the pool changes.
This is why central-bank collateral is a powerful model for private-asset infrastructure. The asset does not become more real when it is pledged. It becomes more usable because the evidence around it has reached a higher standard. That is what institutional market infrastructure ultimately does. It turns assets into reliable states that other institutions can act on.
Sources
- Reuters: Banks rush to swap higher-risk credit assets for Bank of England cash
- Bank of England: Eligible collateral
- Bank of England: Guide to Pre-positioning Loan Collateral
- Bank of England: Guide to the Management of Loan Collateral
- Bank of England: Additional Guidance for Loan Collateral
- Bank of England: Data audit AUPs and results tables
- Bank of England: Report on official market operations March 2025–February 2026
- Bank of England: Recalibration of the Indexed Long-Term Repo Operation