 Insights
The Token Cannot Have Its Own Reality: What the SEC’s New Stock Rules Reveal About Asset Identity
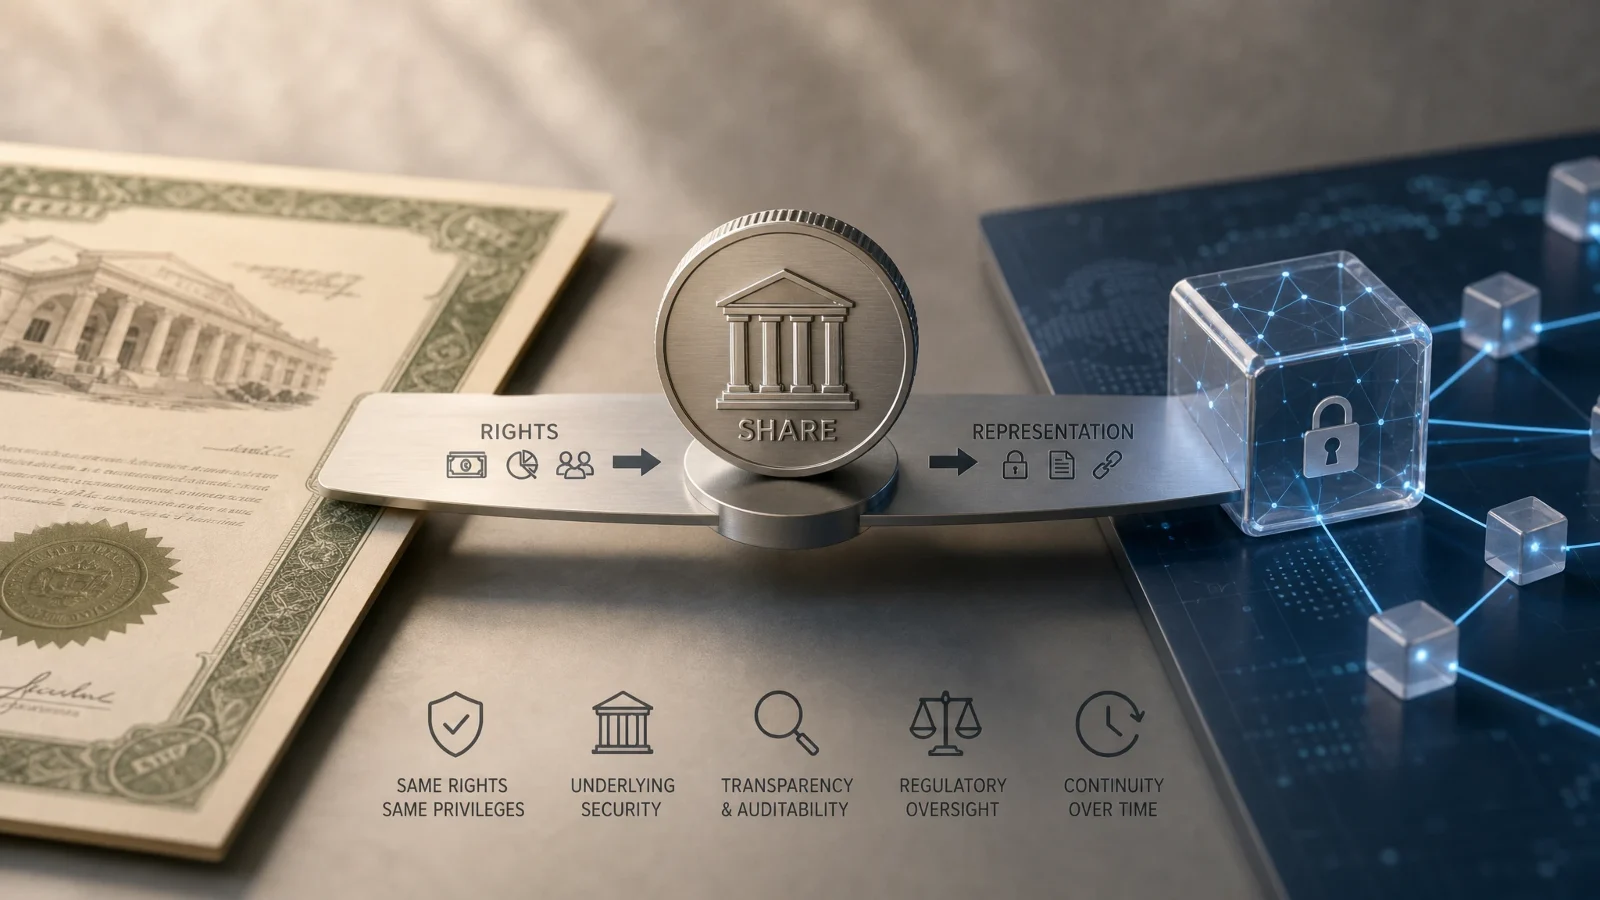
The US Securities and Exchange Commission has created a five-year conditional exemption allowing limited on-chain trading of tokenised NMS stocks on Tokenized Securities Venues. The conditions make the underlying infrastructure lesson unusually explicit: a tokenised stock must provide the same rights and privileges as the equivalent traditional share, issuers can object to unaffiliated third-party tokenisation, smart contracts must be public and auditable, and trading in the tokenised stock...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
A digital representation can use a new settlement rail while remaining dependent on the same underlying security. Its holder rights, corporate actions and trading status cannot safely drift into a separate account of reality.
On 17 September 2026, the SEC announced an Innovation Exemption providing temporary, conditional relief for limited trading of tokenised National Market System stocks on Tokenized Securities Venues, TSVs. The conditions matter as much as the token technology: the described framework requires continuity with the traditional security's rights and primary-market state. This article concerns that particular conditional framework, not an unrestricted permission for every tokenised-stock model. SEC announcement
Equivalent price exposure is not equivalent shareholder rights
The SEC requires a TSV to verify that the tokenised NMS stock gives holders the same rights and privileges as its traditional equivalent, expressly including dividends and voting. Chairman Paul Atkins described tokenisation by or for the issuer, or by an unaffiliated third party, subject to that continuity. A synthetic instrument tracking price is a different object. Atkins statement
The underlying security already has an issuer, class, rights, ownership process, primary listing, corporate actions, trading status and regulatory treatment. A token representation must connect to those facts instead of becoming another authority for them.
Voting and dividends are only part of the map. Merger, tender, split, spin-off, liquidation and information rights also require a defined path to the holder. Reviewers need the exact share class, how votes are exercised and dividends passed through, what happens in a split and what follows a suspension. A token balance cannot answer those questions alone.
Wallet possession also may sit within a chain of registered and beneficial owners, custodians, brokers, nominees, depository positions and economic beneficiaries. “Owner” should not collapse the structure. The SEC's separate September 2026 transfer-agent modernisation proposal concerned electronic and blockchain recordkeeping and uncertificated securities; a proposal is distinct from a completed rule change or a finding that every blockchain is the legal register. SEC transfer-agent developments
Issuer notice and trading halts create specific dependencies
For relevant unaffiliated third-party tokenisation, the TSV must give written notice and an opportunity for the issuer to object. That is a notice-and-objection process, not necessarily “Issuer approved: Yes”. Preserve the provider, affiliation status, notice date and recipient, objection period, response, objection and effective state with their sources.
Issuer history can continue through later concerns, restructuring, merger, delisting or cessation. An absence of objection at one time should not erase subsequent events.
The framework also requires concurrent cessation of token trading when the primary exchange stops trading the underlying NMS stock. An underlying halt and a token venue continuing normally would be a material state mismatch.
This dependency extends as an architectural principle to splits, dividends, mergers, tenders, spin-offs, delisting and suspension, name or ticker changes, rights issues, record dates and voting. Not all events have the same rule or consequence, but each needs an identified source and a corresponding representation response.
Corporate actions require two linked histories
An illustrative 2-for-1 split involves an issuer action, an authoritative security-record update, entitlement calculation, token adjustment and venue reconciliation. If one stage does not update, the representation can diverge.
A dividend likewise connects declaration and record date to authoritative entitlement, token-holder mapping and distribution. A wallet observed after the record date may not identify the person entitled at that earlier time. Voting requires proxy distribution, instructions, the controlling date, beneficial-owner mapping, any intermediary aggregation, prevention of duplicate votes and an authoritative record.
The underlying security's issue, trades, dividends, split, halt, resumption and merger form one history. The representation's mint, transfer, lock, burn and remint form another. Both should be connected. A tender right not passed through, or a delisted security presented as ordinarily tradeable, is more than a cosmetic data difference.
Public contracts coexist with permissioned market access
The SEC conditions described in the source require TSV smart contracts to be public, auditable and deployed on a public, permissionless distributed ledger. Operational provenance may therefore include the contract, version, audit, deployment and venue use. Public code is useful evidence, but rights can still depend on offering documents, venue rules, transfer-agent and custody records, issuer actions, eligibility, securities and corporate law and contractual arrangements.
The TSV framework uses permissioned automated market makers and liquidity pools and requires participant access standards. A public chain and public contract can therefore coexist with permissioned securities trading. Network openness and legal market access are different properties.
Symbol and volume limits also form part of the exemption. A token can technically exist while a venue's permitted activity is constrained. Venue information may need the symbol, cap, access state, suspension or underlying halt, notices, pool, reporting and exemption eligibility. Underlying security, token, holder, venue, liquidity pool and settlement are separate coordinated states.
Technical ledger finality is not necessarily the whole securities-settlement result. Cash payment, legal rules and participant obligations, custody, records, reconciliation, entitlement, reporting and error handling can still matter.
A proposed record should expose mismatches and their sources
Contract address and network identify a representation; issuer, class, CUSIP/ISIN or another authoritative identifier and primary listing identify what it represents. Keep both visible, alongside symbol and venue.
| Proposed layer | Evidence and state to preserve |
|---|---|
| Underlying security | Issuer/LEI, class and authoritative identifier, listing/ticker, voting, dividend and other rights, trading state and action history. |
| Authoritative ownership | Transfer agent/depository, registered owner and beneficial structure, custody chain, record date, position source, reconciliation time and current authority. |
| Token | Issuer/provider and relationship, contract/network/version/address/symbol, supply, mint/burn rules, transfer restrictions and current state. |
| Rights mapping | Underlying and equivalent holder right, dividend/voting/action mechanisms, redemption/conversion, settlement, exceptions and evidence. |
| Issuer notice | Provider, unaffiliated status, notice and recipient, objection window, response/objection, effective status and source. |
| Venue | TSV, access and participants, AMM/pool, symbol/volume limits, trading/halt status, notices, transaction reporting and exemption status. |
| Synchronisation | Underlying and token halt, halt/resume times, action and adjustment, reconciliation, exception, unresolved mismatch and reviewer. |
| Provenance | Issuer filing, exchange and agent records, SEC order, venue disclosure, contract source/audit, transaction, reconciliation report, time/version and reviewer. |
That is a proposed information model. A complete securities synchronisation or exemption-compliance engine is not an existing capability established by a DaDepo Passport.
A useful record can explicitly show underlying halted / token trading, dividend declared / pass-through pending, or issuer notice sent / objection period open. It should not hide disagreement behind a general green status. Reconciliations may compare supply with authorised positions, holders with ownership records, entitlements with distributions and venue trading with primary-market status.
Preparation cannot manufacture shareholder or regulatory authority
DaDepo's bounded role is document-backed private preparation and reviewable information. A user can retain issuer and instrument documents and explain the intended representation and relevant sources. External market records, notices, legal analysis and authorised institutions remain necessary for ownership, rights and trading determinations.
Future specialised AI checks could extract actions, map filings to contracts, compare supply and positions, identify dividend dates and rights descriptions, classify restrictions, flag stale notices, monitor contract versions and build underlying/token timelines. Those are proposed checks, rather than a claim that the current product automatically monitors markets.
AI cannot independently establish equivalent legal rights, ownership, valid objection, legal finality, exemption compliance, correct action implementation, enforceable code or suitability. Preparing a Passport does not issue or tokenise stock, act as transfer agent, register, depository, custodian, TSV, exchange, pool or broker/dealer, verify exemption eligibility, determine rights, process actions, settle trades or guarantee reconciliation. Securities issuance, tokenisation, transfer agency, depository, custody, trading, dealing, clearing, settlement, legal, regulatory, tax, accounting, investment and valuation services require their own expressly identified and lawful basis.
Questions for continuity between the security and the token
Identity, rights and authority
- Underlying security: Which exact traditional security is represented?
- Issuer: Which legal entity issued it?
- Class: Which share class or security class applies?
- Identifier: Which authoritative identifier anchors the asset?
- Primary market: Where is the underlying security listed or recorded?
- Rights: Which dividends, voting and other rights attach to it?
- Ownership: Where is authoritative ownership recorded?
- Token issuer: Who created the representation?
- Token contract: Which smart contract defines it?
- Network: On which ledger is it deployed?
- Rights equivalence: How are underlying rights passed to token holders?
- Issuer notice: Was the issuer notified where required?
- Issuer objection: Is any objection active?
- Supply: How is token supply reconciled with the underlying position?
Transfer, market state and continuing review
- Transfer: What legal effect does an on-chain transfer have?
- Access: Who is permitted to trade?
- Venue: Which TSV or other venue is used?
- Trading status: Is the underlying stock trading?
- Token trading status: Is the tokenised representation trading?
- Halt synchronisation: Do the two states match?
- Corporate actions: How are splits, dividends and mergers propagated?
- Record dates: Which system determines entitlement?
- Voting: How are voting instructions transmitted?
- Settlement: Which events establish completion?
- Reconciliation: When were token and authoritative records last compared?
- Smart-contract audit: Which audit exists and which version did it cover?
- Regulatory basis: Which exemption, registration or rule applies?
- Provenance: Can every right and state be traced to a source and timestamp?
The continuity problem also arises for tokenised bonds, funds, money-market instruments, private credit, receivables and commodities. A new rail does not create a new authoritative account of the underlying rights. The representation is useful while its holder rights and current state remain connected to the asset's documented and institutional reality.
Further reading
- SEC: Innovation Exemption for tokenised NMS stock
- SEC Chairman Atkins: Innovation Exemption statement
- SEC Commissioner Uyeda: Innovation Exemption statement
- SEC: Order and request for comment, File No. 4-927
- Reuters: Five-year exemption for tokenised-stock trading
- SEC: Transfer-agent and tokenisation developments