 Insights
The Token Is Not the Product: $351 Billion-a-Day Repo Shows Where Digital Securities Actually Matter
Broadridge’s Distributed Ledger Repo platform processed an average of $351 billion of repo transactions per day in August 2026 and is expanding from tokenised US Treasury collateral to G7 securities and cross-border repo. The significance is not that a bond received a token. Repo is exposing the more valuable use case: real-time collateral identity, encumbrance, eligibility, intraday mobility and synchronized delivery-versus-payment across existing institutional workflows.
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
Minting a digital representation of a bond and moving it between wallets demonstrates a technical transfer, but it says little about whether the asset can support an institutional financing transaction. Repo is a harder test: the security must be identified, eligible and available; its ownership and encumbrance must be understood; collateral and cash must settle; and release or return must make any later use possible.
That sequence is why tokenisation's relevance to repo lies in collateral-state infrastructure rather than the number of tokens created. On 2 September 2026, Broadridge announced that its Distributed Ledger Repo, or DLR, platform was expanding from tokenised US Treasury collateral to G7 securities, supporting international cross-border repo, intraday repo and collateral movements. The scale is already substantial. Broadridge said DLR processed an average of $351 billion in repo transactions every day during August 2026, totalling $7.4 trillion for the month, with thousands of transactions passing through the platform daily. Broadridge: Broadridge Brings G7 Securities to Institutional Tokenized Repo
This is not a pilot-sized number. DLR had already processed an average of $365 billion a day in July and $357 billion a day in June. Broadridge: DLR Processes $8.0 Trillion in July The important question is therefore no longer:
Can distributed ledger technology settle a repo?
The stronger question is:
What changes when collateral can be identified, encumbered, moved, released and reused with much less operational friction?
That is a DaDepo question.
Start with repo, ownership and encumbrance
A repo can be described economically as secured borrowing. One party provides securities. The other provides cash. The parties agree that the securities will later be repurchased under defined terms. A simplified lifecycle looks like:
Seller / cash borrower → Delivers securities → Buyer / cash lender → Buyer → Delivers cash → Seller.
At maturity:
Seller → Returns cash plus repo economics → Buyer → Buyer → Returns securities → Seller.
The security temporarily plays a collateral role. That role is time-dependent. The underlying bond has not become a different bond. Its state has changed.
Suppose Bank A owns a government bond. Before repo:
| Record item | Value or state |
|---|---|
| Owner | Bank A |
| Encumbered | No |
| Available collateral | Yes |
During repo:
| Record item | Value or state |
|---|---|
| Economic / legal position | governed by repo structure |
| Counterparty | Bank B |
| Encumbrance / collateral state | Active |
| Repo maturity | Today 16:00 |
After close:
- Repo settled
- Collateral returned / released
- Available again
The exact legal mechanics vary by repo documentation and jurisdiction. The infrastructure principle is universal. A security needs more than Owner. It also needs: Current collateral state.
Many asset systems answer: Who owns this? Far fewer answer reliably: Who currently has rights over it? A security can be:
- pledged;
- repoed;
- lent;
- posted as margin;
- held in custody;
- subject to a lien;
- frozen;
- earmarked; or
- otherwise unavailable for another transaction.
The same issue appears in private assets. A receivable may already be assigned. A mortgage may already secure another facility. A loan may already sit inside a securitisation. A GPU may already be pledged. A property may already have a senior charge. Asset ownership without encumbrance state is incomplete.
For a long-term secured loan, collateral may remain pledged for years. Repo can change much faster. A security might be:
| Record item | Value or state |
|---|---|
| Unencumbered at 09 | 00 |
| Repo collateral at 09 | 15 |
| Released at 12 | 00 |
| Reused at 12 | 30 |
| Returned at 16 | 00 |
That creates a need for high-frequency asset-state management. The token is useful because the state can move with less reconciliation. The commercial value is not the token itself. It is the reduction in uncertainty and delay around collateral availability.
Establish availability separately from eligibility
Broadridge specifically supports intraday repo. Traditional secured funding is often discussed in overnight or term horizons. Intraday repo treats collateral as a liquidity resource inside the day. An institution might need cash for several hours because:
- settlement outflows occur before inflows;
- margin must be posted;
- another securities transaction settles later;
- treasury balances are temporarily uneven; or
- payment-system timing creates a short liquidity gap.
If collateral can be mobilised quickly, an institution can finance that gap without holding the same amount of idle cash all day. That is collateral efficiency.
Suppose a treasury desk sees: £5bn government bonds. That number is almost useless by itself. The desk needs to know:
- £5bn total holdings
- £1.5bn already repoed
- £0.8bn pledged as margin
- £0.4bn restricted
- £0.3bn pending settlement
- £2.0bn available
The economically important field is Mobilisable now. That value can change throughout the day. Digital collateral infrastructure is valuable when it can maintain that state reliably.
A security can be available and still not be eligible for a specific repo. Eligibility may depend on:
- issuer;
- jurisdiction;
- currency;
- rating;
- maturity;
- haircut schedule;
- counterparty rules;
- mandate;
- regulatory treatment;
- settlement venue; or
- negotiated collateral schedule.
Therefore: Unencumbered: Yes does not mean: Eligible for this transaction: Yes. A good collateral record needs both.
Consider a German government bond. It may be:
- Eligible for Repo Agreement A
- Ineligible for Repo Agreement B
- Eligible for Central Bank Facility C
- Not permitted under Fund Mandate D
Eligibility belongs to the relationship between:
Asset + Rule set + Counterparty + Time.
It is not a permanent property of the bond. That is exactly the kind of context a proposed evidence record should preserve.
Connect cross-border securities, cash and settlement
G7 expansion creates a cross-border state problem
Broadridge’s latest expansion brings G7 securities into DLR. This matters because collateral mobility becomes much harder when assets cross markets. The workflow can involve:
- different CSDs;
- different custodians;
- different currencies;
- different settlement calendars;
- different market cut-offs;
- different legal regimes; and
- different collateral conventions.
Traditional infrastructure often moves these states through multiple systems. The asset can exist simultaneously in:
- Trading system
- Custody system
- Collateral system
- Settlement system
- Treasury system
- Accounting system
Every hand-off creates reconciliation. Digital infrastructure becomes useful when those systems can refer to one coherent asset state.
Broadridge says DLR supports the synchronized movement of tokenised securities and cash. That is atomic settlement. The crucial point is that:
The security leg and the cash leg are distinct.
The two are separate assets. Atomic settlement connects their state transitions:
Securities are delivered if and only if cash is delivered.
This reduces principal and settlement risk. It does not merge the security and money into one object.
A robust repo record needs to distinguish:
1. Underlying security
The bond, note or other eligible instrument.
2. Security position
The quantity held by a particular institution.
3. Collateral allocation
The portion of that position assigned to the repo.
4. Repo contract
The legal transaction defining cash, collateral, maturity and repurchase terms.
5. Cash leg
The amount and currency transferred.
6. Settlement state
Whether each leg has been instructed, matched and completed. A token can help connect these objects. It should not collapse them.
A US Treasury does not need to be legally reissued every time it participates in a tokenised repo. A digital infrastructure can create a representation or control layer that allows the asset state to be managed on-chain while preserving links to conventional securities infrastructure. This distinction matters. The useful architecture can be:
Traditional security → Authoritative custody / settlement position → Digital representation or control record → Repo lifecycle.
The value comes from synchronisation. Not from pretending the original security disappeared.
Keep the token tied to authoritative rights and release
This is the main design risk. Suppose a token says Bank A controls $100m Treasury collateral. The underlying custody record says Bank A owns $80m. The token infrastructure is now wrong. The system therefore needs reconciliation between:
- underlying security;
- custody position;
- digital representation;
- repo allocation; and
- settlement state.
Blockchain immutability cannot rescue a bad mapping.
A repo does not end when cash arrives. Collateral must later become free again. A lifecycle might be:
Available → Allocated → Encumbered → Settled → Maturing → Returned → Released → Available.
The release event matters. Without it, collateral can become trapped operationally. A system can have billions of securities on its balance sheet and still suffer a liquidity problem if it cannot identify which assets are free.
Repo markets can involve collateral reuse depending on transaction structure and legal rights. That creates another layer. The system may need to know:
- may the recipient reuse the collateral;
- has it been reused;
- under which transaction;
- when must equivalent collateral be returned; and
- what happens if the chain breaks?
A generic field such as Pledged: Yes cannot represent this. The lifecycle can form a graph.
Imagine:
Fund A → Repo to Dealer B → Dealer B → Permitted reuse → Repo to Bank C.
Now one underlying security is connected to several contractual positions. The market needs to know:
- who has legal title;
- who has an obligation to return equivalent securities;
- who has economic exposure;
- which repo matures first; and
- which collateral can be substituted.
This is not a spreadsheet problem. It is an asset graph.
Identifies the security and the relevant legal or economic position. It may include securities already allocated, pledged, repoed, restricted or awaiting settlement.
Requires a current view of encumbrance, allocation, eligibility, settlement and release conditions. A holding amount or token balance alone does not establish availability.
Follow substitution, haircuts, margin and corporate actions
Repo agreements can permit collateral substitution. That means the original collateral can be replaced during the life of the trade. The repo contract persists. The collateral changes. For example:
- Repo R-1001
- 09:00 collateral:
- US Treasury A
- 13:00 substitution:
- US Treasury A released
- German Bund B delivered
- Repo remains open
If the system stores: Collateral: Treasury A as a static field, it becomes wrong at 13:00. The correct model is event-based.
Repo financing rarely treats collateral market value as equal to cash advanced. Haircuts or margin determine the financing value. A bond worth $100 million might support: $98 million cash depending on terms. The record therefore needs:
- quantity;
- market price;
- market value;
- haircut;
- collateral value;
- cash amount;
- margin requirement; and
- valuation time.
These values can change intraday.
If the collateral price falls, the repo may require additional collateral. If the price rises, collateral may be released. The lifecycle can therefore include:
Initial collateral → Market value changes → Margin deficit → Margin call → Additional collateral posted.
or:
Excess collateral → Release.
Real-time or near-real-time infrastructure makes these transitions easier to manage.
Repo collateral does not exist outside securities servicing. If a bond:
- pays coupon;
- matures;
- is called;
- changes identifier; or
- undergoes another event,
the repo system needs to know. A digital collateral platform therefore still needs integration with:
- corporate actions;
- security master;
- custody; and
- settlement.
Tokenisation is not a replacement for asset servicing. It is another layer of it.
Broadridge’s G7 expansion is intended to support collateral across markets, currencies and jurisdictions. That can introduce:
The security currency can differ from the cash currency.
Now the transaction may also involve:
- FX rates;
- currency haircut;
- settlement windows;
- payment-system availability; and
- cross-border legal considerations.
A proposed repo evidence record needs to distinguish all of them.
A proposed collateral record with an encumbrance history
As a proposed direction for DaDepo, the most important design lesson is not a repo-specific smart contract. It is the need for an encumbrance ledger. A security or private asset should be able to answer:
- Who owns me?
- Who has rights over me?
- Am I available?
- Am I eligible?
- What transaction currently uses me?
- When will I be released?
That model applies to:
- bonds;
- loans;
- receivables;
- mortgages;
- equipment;
- intellectual property;
- claims; and
- other private assets.
A useful repo/collateral record could include several layers.
| Record layer | Information to retain |
|---|---|
| Security identity | issuer; instrument; ISIN or equivalent; currency; maturity; coupon; current quantity; authoritative security-master source. |
| Ownership and custody | legal owner; beneficial owner; custodian; account; depository; current position; as-of time. |
| Digital representation | network; token or digital identifier; representation type; mint / burn authority; backing relationship; reconciliation status. |
| Eligibility | counterparty; collateral schedule; eligible / ineligible state; haircut category; jurisdiction; currency restrictions; concentration constraints; effective date. |
| Encumbrance | available quantity; encumbered quantity; repo ID; secured counterparty; start time; end time; reuse permission; reuse state; release status. |
| Repo economics | cash amount; currency; repo rate; start date; maturity; repurchase price; haircut; margin; substitution rights. |
| Settlement | security instruction; cash instruction; DvP state; settlement venue; settlement timestamp; failure; reversal or correction status. |
| Lifecycle | allocation; initial settlement; substitution; margin call; additional collateral; partial unwind; maturity; return; release. |
| Provenance | repo agreement; collateral schedule; custodian record; CSD record; market price; blockchain transaction; settlement confirmation; reviewer; last updated timestamp. |
This is what makes digital collateral useful.
Repo markets use highly standardised securities. Private markets are messier. But the core state problem is identical. Consider a receivable. It can be:
- Owned
- Available
- Assigned
- Pledged
- Released
- Sold
A mortgage loan can be:
- Held
- Securitised
- Repoed
- Released
- Transferred
A GPU can be:
- Owned
- Secured
- Released
- Repledged
A legal claim can be:
- Owned
- Funded
- Subject to participation
- Assigned where legally permitted
If DaDepo wants private assets eventually to move between financing venues, the platform needs the same concept that repo infrastructure needs today: current collateral state.
Assess activity and workflow integration
A blockchain dashboard can celebrate: 1 million tokens minted. That is not necessarily economically meaningful. Collateral infrastructure should care about:
- how many assets are mobilised;
- how often they can move;
- settlement failure;
- intraday financing generated;
- collateral released;
- reuse efficiency; and
- liquidity saved.
Broadridge’s $351 billion daily repo volume is important precisely because it measures activity. The tokens are being used.
Broadridge emphasises that DLR is embedded inside existing institutional trading and post-trade processes. That is a significant design choice. Banks do not need every trader and operations team to become blockchain specialists. The digital layer needs to connect to:
- trade capture;
- treasury;
- collateral management;
- settlement;
- accounting;
- risk; and
- reporting.
This is likely how private-asset tokenisation will mature too. Users will not want to “use blockchain”. They will want to: finance this asset or transfer this collateral. The infrastructure should make the technology secondary.
Broadridge has also made aggregated DLR activity available to Bloomberg Terminal subscribers through its collaboration with Kaiko. That includes:
- repo par value;
- turnover; and
- trade count.
This does not expose private transaction-level data. It does show that institutional on-chain markets can begin generating familiar market data. A mature private market will likely need the same progression:
Asset state → Transaction state → Aggregated market data.
Market transparency emerges from reliable underlying records.
AI assistance and the limits of DaDepo's role
The following AI uses describe proposed assistance within this evidence model. They do not establish that DaDepo currently automates these workflows. Extraction and inconsistency flags would remain suggestions for review, not legal, credit, compliance or valuation decisions.
AI can help collateral managers:
- identify eligible securities;
- forecast liquidity;
- optimise allocations;
- detect concentration;
- compare haircuts;
- flag settlement mismatches;
- identify idle collateral; and
- propose substitutions.
Across a large portfolio, AI can find:
- assets pledged twice in internal systems;
- digital positions inconsistent with custody;
- collateral due to mature before repo close;
- positions blocked by corporate actions; or
- excessive concentration with one counterparty.
That can improve operations. AI should not independently decide:
- that legal title transferred;
- that collateral is unencumbered;
- that a repo is enforceable;
- that a security is eligible;
- that settlement is legally final; or
- that collateral may be rehypothecated.
Those states require authoritative systems and legal rules.
DaDepo's supported contribution is private intake of supported documents and preparation of a draft for user review. Its Parties and contractual roles evidence table can record the party, specific contract, source-described role, document and clause reference, relevant source-stated date and review status. Suggested rows require the user's review and confirmation. The wider relationship models, automated monitoring, reconciliation and decision workflows discussed here are proposed capabilities, not a description of existing DaDepo functionality.
DaDepo does not need to operate institutional repo. The lesson for DaDepo is architectural. A proposed evidence record should eventually be capable of connecting:
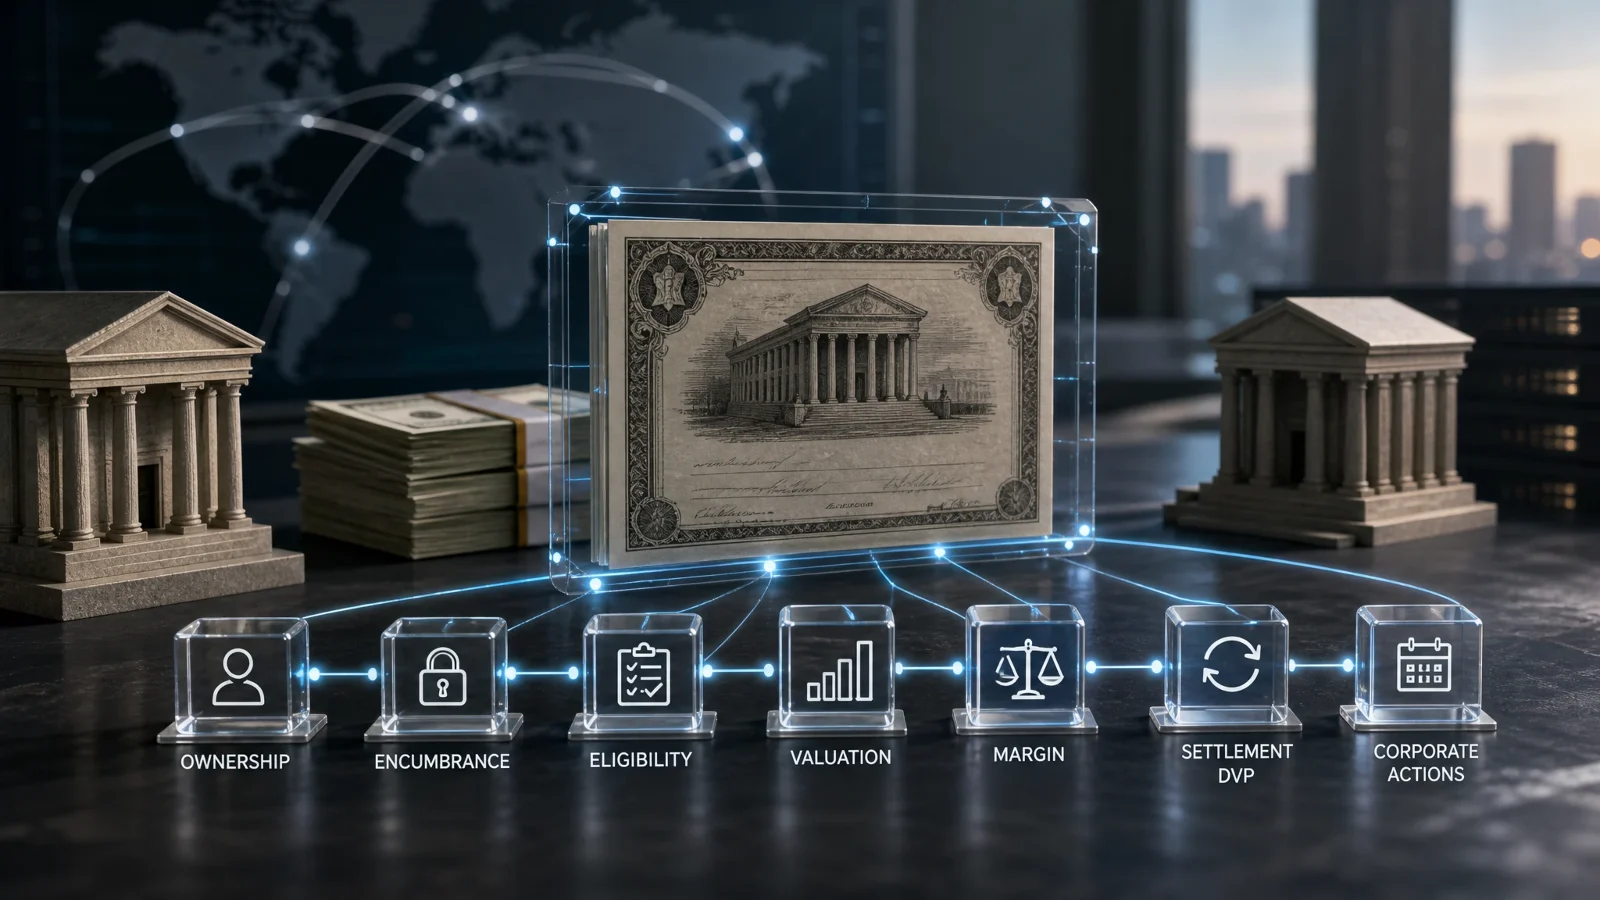
Asset identity → Ownership → Eligibility → Encumbrance → Financing → Settlement → Release.
That is true whether the asset is:
- a government bond;
- a loan;
- a receivable;
- a mortgage;
- equipment;
- IP; or
- another private right.
Tokenisation becomes useful when it helps those state changes move across institutions without losing provenance. The token is not the product. The trusted asset lifecycle is the product.
Creating or reviewing a collateral Asset Passport does not mean that DaDepo has:
- executed a repo;
- acted as repo counterparty;
- determined collateral eligibility;
- verified legal ownership;
- provided custody;
- acted as CSD or depository;
- created legal encumbrance;
- perfected security;
- valued collateral;
- calculated an official haircut;
- provided brokerage;
- cleared or settled a trade;
- issued cash or stablecoins;
- determined settlement finality;
- authorised collateral reuse;
- guaranteed liquidity; or
- provided legal, regulatory, treasury, collateral-management, investment, tax, accounting, brokerage, custody, clearing, settlement or valuation advice.
Important: DaDepo provides technology and information tools. It does not provide legal, financial, investment, tax, accounting, brokerage, repo, custody, clearing, settlement, depository, collateral-management, treasury, underwriting or valuation advice or services unless a specific service is expressly identified and lawfully provided. Repo rights, collateral ownership, eligibility, reuse, settlement finality and cross-border treatment depend on transaction documents, market infrastructure, governing law and jurisdiction.
Review questions for collateral mobility
Before an asset is treated as digitally mobilisable collateral, ask:
- Identity: Which exact security or asset is being used?
- Ownership: Who legally owns it before the transaction?
- Custody: Where is the authoritative position recorded?
- Digital representation: What does the token or digital record legally and operationally represent?
- Reconciliation: Does the digital position match the authoritative underlying position?
- Availability: How much of the position is currently unencumbered?
- Eligibility: Is the asset eligible for this specific counterparty and agreement?
- Haircut: What financing value applies?
- Allocation: Which quantity is allocated to the transaction?
- Encumbrance: When does the collateral become unavailable for other use?
- Cash leg: What cash amount and currency are exchanged?
- Settlement: Are security and cash movements synchronized?
- Finality: Which system or legal rule determines that settlement is complete?
- Substitution: Can collateral be replaced while the repo remains open?
- Margin: How are market-value changes reflected?
- Reuse: May the receiving party reuse the collateral?
- Corporate actions: How are coupons, maturities and other events processed?
- Release: What event returns the asset to available status?
- Cross-border: Which custody, settlement, currency and legal constraints apply?
- Provenance: Can every state transition be traced to the trade, custody record, digital ledger and settlement evidence?
If an institution can transfer a token instantly but cannot tell whether the underlying asset is already pledged somewhere else, it has digitised the wrong problem.
Make collateral state observable
Broadridge’s DLR volumes matter because they reveal where institutional tokenisation is already useful. Not in creating digital collectibles. Not in demonstrating that a bond can have a token ID. Not even primarily in giving investors a new way to view securities. The value is in making a highly repetitive institutional process more efficient:
Identify collateral → Confirm availability → Allocate → Encumber → Move against cash → Monitor → Substitute if necessary → Return → Release → Reuse.
Repo turns the security into a financing resource. Digital infrastructure makes that resource easier to mobilise. That is a much more important transformation than token issuance by itself. The future of tokenised assets may therefore be measured less by: How many securities have tokens? and more by: How quickly can trusted asset state move between owners, counterparties and financing uses? At $351 billion a day, institutional repo is beginning to provide an answer.
Sources
- Broadridge: Broadridge Brings G7 Securities to Institutional Tokenized Repo
- Broadridge: Distributed Ledger Repo Processes $8.0 Trillion in July
- Broadridge: Distributed Ledger Repo Processes $7.5 Trillion in June
- Broadridge: Distributed Ledger Repo Platform Achieves 508% Year-over-Year Growth in January
- Broadridge: Distributed Ledger Repo