 Insights
Financing the Step from Local Business to Exporter
Afreximbank's reported US$75 million commitment to the Development Bank of Nigeria pairs wholesale funding with export-readiness and market-access support. For a small business, the practical questions concern the participating lender, the purpose of the loan and the cash cycle it must support. An announced facility still needs to become an accessible lending product.
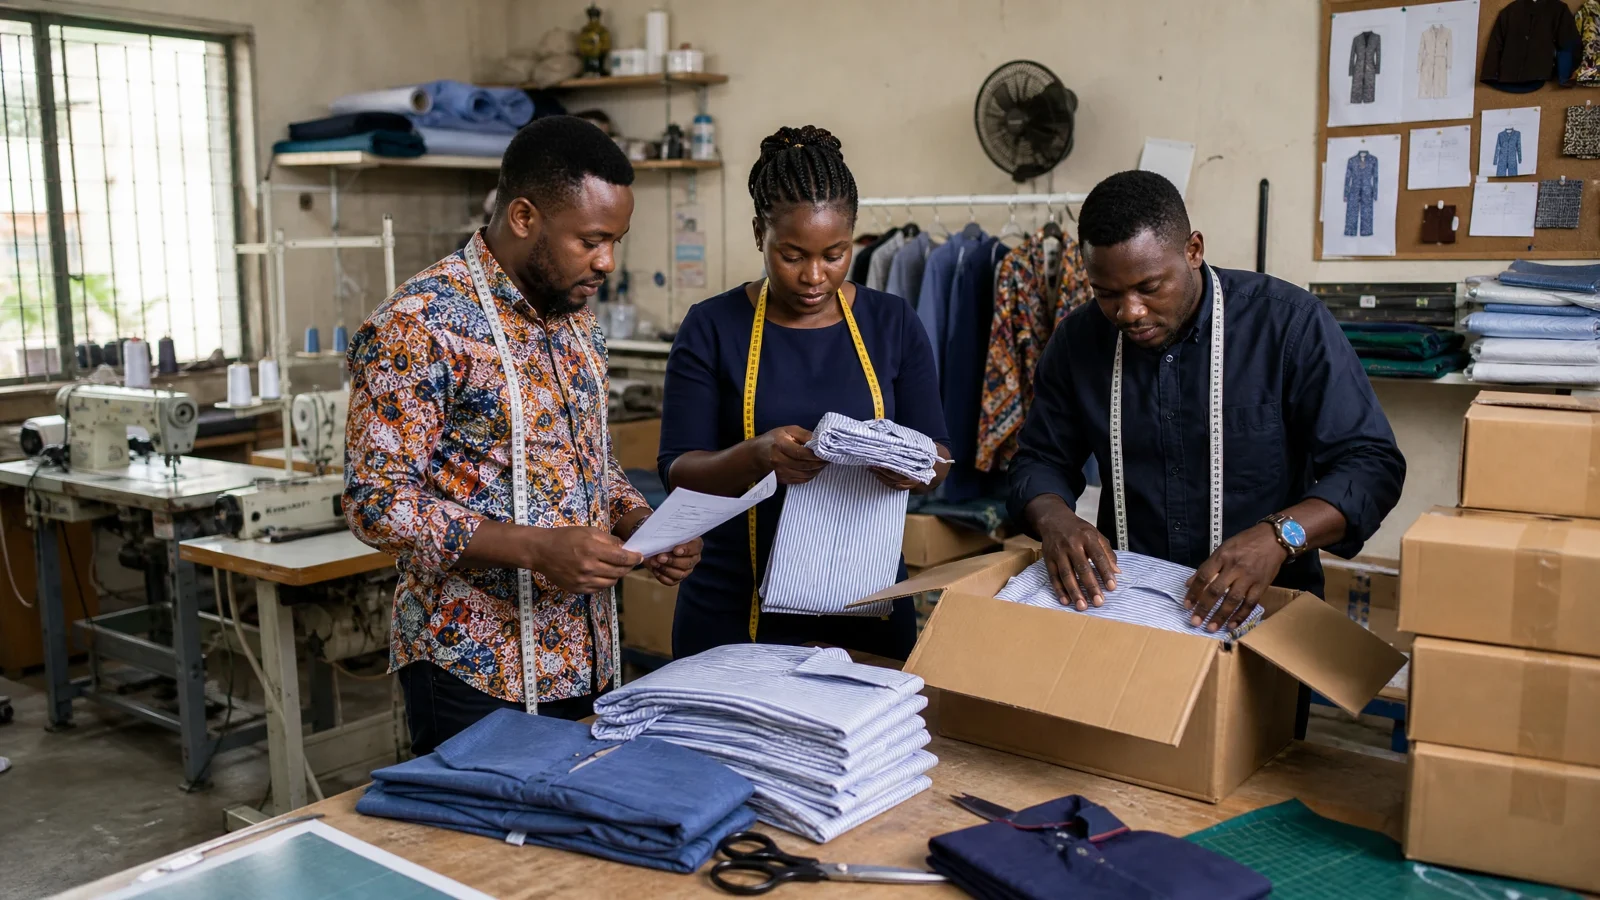
A small business can find a buyer abroad before it has the cash to fulfil the order. Materials, staff and delivery may need to be paid for before the customer pays. For a business making that transition, access to finance is connected to the practical work of producing, selling and collecting payment in a new market.
Afreximbank has committed US$75 million to the Development Bank of Nigeria (DBN) for small and medium-sized businesses, including creative enterprises, according to Premium Times' 11 November 2026 report on a joint statement. Funding is intended to flow through DBN's participating financial institutions. That identifies a lending route; an individual business's approval and receipt of funds still need their own evidence. Premium Times' report
The useful question for a founder is how that route becomes available in practice. A wholesale commitment can increase the resources behind lending, while the individual business still needs a lender, suitable terms and a credible explanation of how the borrowing will be used and repaid.
Start with the institution that can make the loan
DBN's own general guidance explains its on-lending model. A business approaches an eligible participating financial institution, which appraises the business and loan purpose. If that assessment is favourable, the institution applies to DBN for funding; DBN approval leads to disbursement to the institution for on-lending. This is DBN's published general process, not a facility-specific application guide for the newly reported commitment. DBN: how to get a loan
- The business approaches an eligible participating financial institution with its financing request.
- The institution appraises the business and loan purpose and, if favourable, applies to DBN for funding.
- If DBN approves, funding goes to the institution for on-lending to end borrowers, under the applicable arrangements.
For an applicant, that makes the lending relationship the starting point. The relevant institution needs to confirm whether it participates, whether an appropriate product is available and which conditions govern the request. General information about DBN programmes should not be treated as an offer under this particular facility.
It also helps to separate the decisions being made. Funding provided to a financial institution and a loan offered to a business sit at different points in the chain. An announcement about the former cannot establish the latter's price, repayment schedule or approval. Those details need to be confirmed through the institution actually offering the product.
Explain the cash cycle the finance will support
Working capital and an equipment purchase can put pressure on the same business at different times. A useful request explains what is being financed and when the cash is expected to return. That gives the proposed borrowing a practical purpose beyond a general ambition to expand.
Consider a hypothetical clothing workshop preparing its first substantial overseas order. It may need fabric and wages before dispatch, an additional machine to increase capacity, or funding while waiting for an agreed customer payment. These are illustrative needs, not statements that the workshop qualifies for the announced programme. Each request would benefit from explaining a different part of the business's cash cycle.
| Illustrative need | What the business would explain | Question to resolve with the lender |
|---|---|---|
| Producing an order | The production budget, delivery timetable and expected customer payments. | How does the proposed repayment schedule relate to that timetable? |
| Buying equipment | The purchase cost, productive use and cash needed during installation. | What term, conditions and security would apply? |
| Waiting for payment | The sale, delivery position, payment terms and expected receipt. | Which receivables or other repayment sources would the lender accept? |
The table is a preparation aid, not a published list of DBN application requirements. Its purpose is to make a request understandable. A single amount labelled growth finance can conceal several uses of cash with different timings. Separating those uses gives the business and lender a clearer basis for discussing the proposed borrowing.
Currency belongs in that conversation too. The US-dollar size of a wholesale facility does not establish the currency in which a small business would borrow or repay. A business receiving customer payments in another currency needs to understand the terms of any actual offer and how changes in payment timing or exchange rates could affect its cash needs.
Export readiness is part of the proposed support
The reported partnership also includes capacity building, export-readiness support and market access, with training intended to strengthen participating lenders' ability to serve export-oriented SMEs. Those are announced components of the approach, not measured outcomes. The partnership's stated support model
The combination addresses a practical issue: obtaining capital and being ready to fulfil an export order are connected tasks. A business still needs to understand what the buyer expects, whether it can meet the delivery timetable and how payment will be collected. More borrowing cannot, by itself, settle an unclear order or correct a production plan that does not match the customer's requirements.
Support for lenders matters for similar reasons. A useful appraisal needs to understand how the particular enterprise earns and receives money. The cash cycle of a production business may differ from that of a creative project with staged payments or a licence-based income stream. Capacity building can be assessed by whether it helps lenders evaluate those differences, alongside whether finance reaches viable businesses.
That gives the partnership a broader test than the amount announced. The intended connection between finance and practical support would need to show up in products that businesses can access and in preparation that helps them complete commercial transactions. The announcement identifies the ambition; implementation will provide evidence of how it works.
Watch for the terms that turn the announcement into an option
The report provides no facility-specific borrower rate, individual limit or application timetable. Any actual offer needs its own confirmed terms, including the conditions that must be met before funds become available.
The next useful information would identify available products, the relevant lender, eligible uses, currency, all applicable charges and the process for receiving a decision. Actual lending and the distribution of that lending would then help show whether the facility is reaching the businesses it is intended to support. A signed commitment and a business-level disbursement describe different stages of that progress.
For a smaller exporter, the practical preparation is to connect the financing request with the trade it is meant to support. The budget, order, delivery plan and expected receipts should tell a coherent story, while unresolved conditions remain visible. That makes it easier to evaluate an actual lending offer when one becomes available, and to see where additional commercial preparation is still needed.