 Insights
Bankruptcy Is Not a Group-Level Asset State: Why Debt Needs Legal-Entity Identity
Brightline's restructuring separates the affiliates in Chapter 11 from the operating company behind particular insured bonds. New financing, payment elections and insurance have their own terms and dates. A useful credit record identifies the entity, instrument and obligation before assigning a status to the group.
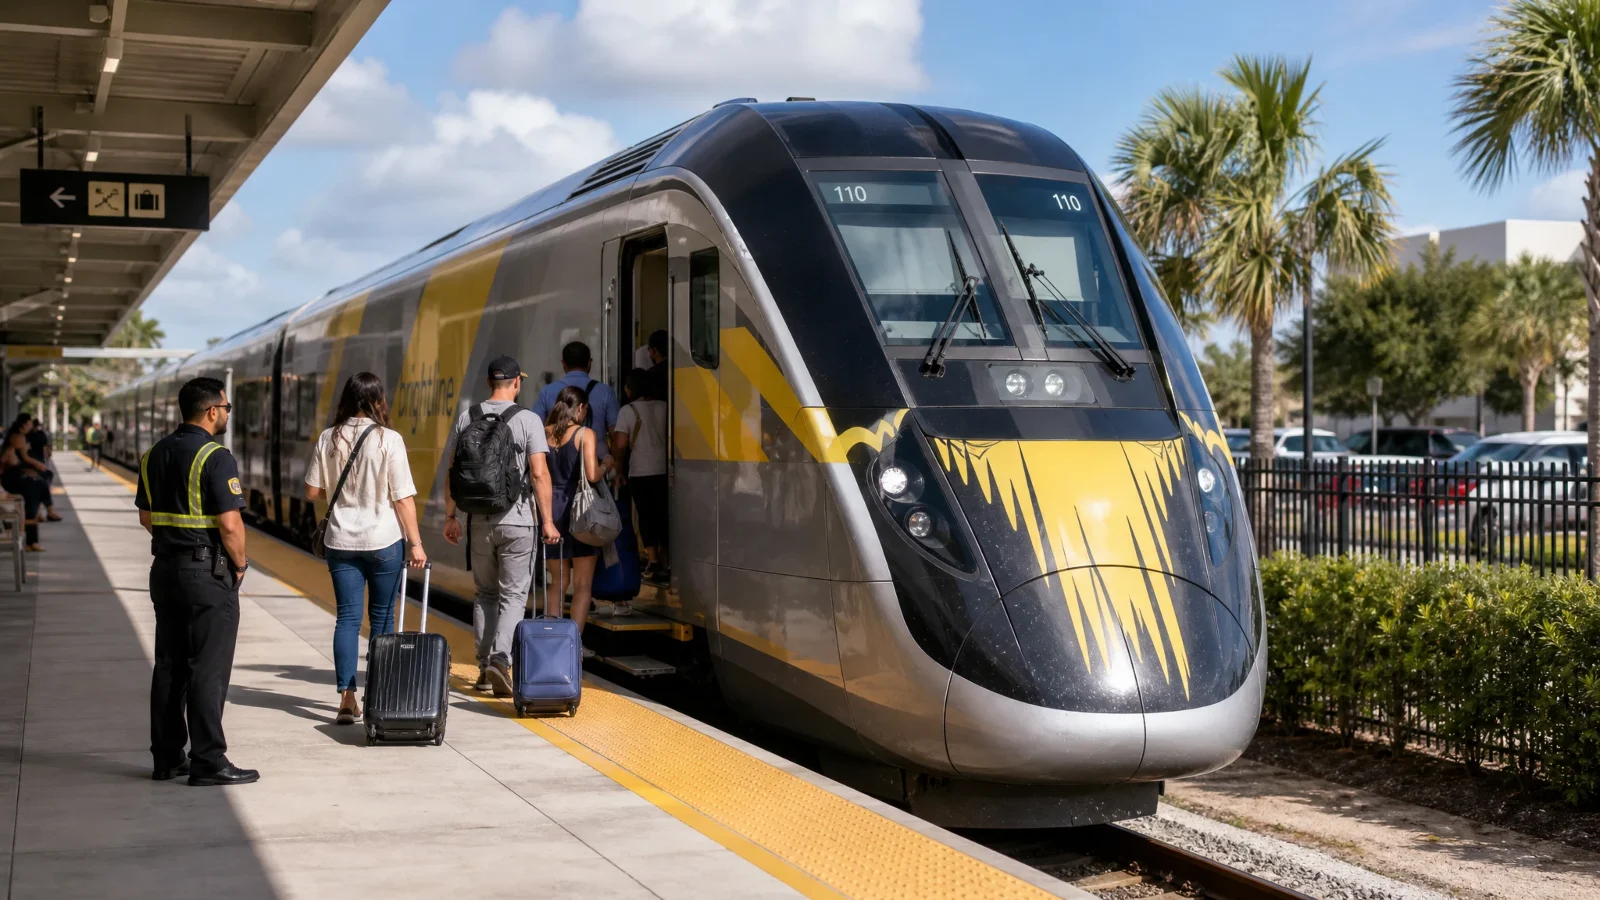
A railway can continue carrying passengers while some companies in its financing structure enter Chapter 11. A particular operating-company bond can remain outstanding while other debt is being restructured. For a creditor, the important question is which entity owes which obligation, rather than whether a familiar brand has appeared in a bankruptcy headline.
Brightline's September 2026 announcement makes that distinction concrete. It described Chapter 11 processes for certain parent entities while saying Brightline Trains Florida LLC would remain outside that process and continue operating. It also identified the approximately US$2.2 billion Series 2024 tax-exempt bonds associated with that operating company as remaining outstanding through the restructuring. These are statements about specified entities and instruments, not every claim connected to the railway. Brightline's restructuring announcement
The case is useful beyond rail finance. A group name helps a reader recognize a business, but it cannot replace the identity of a borrower, guarantor, insurer or security provider. A review needs to preserve those relationships before it interprets a filing, an amendment or a payment event.
Start with the entity named in the obligation
Assured Guaranty's September statement identified Brightline Trains Florida LLC as the obligor on the tax-exempt senior bonds it insures. It said that this company had not filed for Chapter 11 and that filings by certain other Brightline entities did not alter payment obligations on those insured bonds. That is a deliberately bounded statement; it is not a finding that every Brightline security is unaffected. Assured Guaranty's statement
A practical credit review would attach a reported filing status to the named legal entity and its source. It would then identify which instruments, guarantees or other arrangements refer to that entity. If the source does not establish the effect on a particular obligation, that question remains open rather than inheriting a group-wide answer.
| Record to identify | What a reviewer needs | Inference to avoid |
|---|---|---|
| Filing entity | Exact name, proceeding reference and dated evidence | Every affiliate is a debtor in the same case. |
| Bond or loan obligor | The entity and capacity named in the governing documents | The operating brand identifies every payment obligation. |
| Instrument or position | Issue, series, tranche or holding reference | All debt bearing the same brand has the same terms. |
| Guarantor or insurer | The applicable undertaking, scope and beneficiary basis | A guarantee or policy protects every group obligation. |
| Security provider | The named grantor and documented collateral arrangement | Shared operations establish shared collateral. |
These distinctions also prevent a misleading opposite conclusion. A company remaining outside a particular proceeding is not, by itself, evidence that it faces no financial strain. Legal filing status, operating performance and payment capacity are different questions. The documents supporting one should not silently answer the others.
New capital must keep its stage and its rank
Brightline announced commitments for US$490 million of long-term capital, comprising US$140 million of additional senior debt and US$350 million of junior debt. Its release also noted court-approval conditions for certain obligations. A commitment in a restructuring plan should not be recorded as completed funding solely because an announcement gives a headline total. The announced financing structure
Assured Guaranty's later quarterly filing describes the US$490 million as capital to be received upon the affiliates' exit from Chapter 11, subject to conditions. It separately describes US$258 million of post-petition funding and its own agreement to provide up to US$122 million of that amount. The filing identifies the affiliate filings as occurring on 24 September. These dated disclosures are more useful than carrying forward the earlier announcement without checking for changes. Q3 Form 10-Q, U.S. Transportation discussion
For a reviewer, the principle is to retain the facility, the relevant provider, the stated amount and the stage being described. An overall facility amount is not necessarily one participant's commitment, and a commitment is not a receipt. A later amendment can change a participant's share without changing the headline size of the arrangement.
Identify the funding arrangement, relevant borrower, provider commitments and evidence of actual advances during the restructuring process.
Identify the conditions, expected recipient and evidence that the required exit and funding events occurred. An announced commitment does not establish completed funding.
Priority needs a similarly precise treatment. Assured Guaranty described specified new senior debt and post-petition funding as ranking pari passu with existing operating-company senior debt. The expression identifies a stated ranking relationship; it does not supply every collateral, voting, payment or recovery term. Those questions require the applicable documents rather than a general label such as "senior." The insurer's September description
Payment elections belong to the relevant holding
An instrument remaining outstanding does not mean that every holder necessarily follows the same payment timetable. Assured Guaranty's September statement distinguished holders electing a limited interest deferral from holders retaining the original schedule, and described its guarantee by reference to the relevant elected terms. A review should therefore preserve the applicable election and the source supporting it for the particular holding. Payment-election and insurance discussion
This is a different task from applying a status to an entire issue. A reviewer might need the notice offering an election, the holder's instruction, confirmation of acceptance and the resulting schedule. Missing evidence of an election is a question to resolve. It is not a reason to assign whichever timetable appears most recently in correspondence.
The insurer's later filing also states that it had paid no claims on its Brightline exposure as of 5 November 2026. That is an insurer-specific, dated observation. It does not establish that every borrower payment was made from operating revenue or that every creditor experienced the same outcome. The dated claims disclosure
A useful record consequently distinguishes the contractual amount due, any documented amendment or election, the borrower's reported payment and any insurer payment. Combining them into a single "paid" field can make it difficult to explain what happened and in which capacity a party acted.
Keep insurance, collateral and business performance separate
The parties can be connected economically without becoming interchangeable legally. A railway's revenues may matter to its financing, while a policy adds a separate contractual source of payment protection. Neither the presence of insurance nor continuing passenger operations establishes the complete recovery position of a creditor.
For a hypothetical debt holding, consider three files: a bond document naming the obligor, a security document describing collateral and an insurance policy defining covered payments. A restructuring notice then arrives for an affiliate. The review question is how that notice relates to each file and the particular holding, not whether the files can all be updated with the affiliate's bankruptcy status.
| Question | Source basis to preserve |
|---|---|
| Who must make the payment? | The obligation and the named party's capacity |
| What security supports it? | The applicable grant, scope and relevant amendments |
| What does insurance cover? | The policy, insured instrument and payment terms |
| Which financial information is being used? | Reporting entity, period and measurement basis |
| What has actually changed? | The notice, amendment, order or confirmed event supporting that change |
That approach leaves room for a qualified legal or credit assessment without presenting data entry as the assessment itself. A source-described relationship can be recorded for review even when its legal effect remains unresolved. Where records conflict, the conflict should remain visible together with the documents and dates involved.
Make the next update specific enough to review
The most useful next update is attached to an identifiable entity, instrument and event. A court filing, a financing amendment, an election or a payment confirmation can each change part of the picture. They need not change every related record, and their dates may differ.
A review pack should therefore explain what the source establishes, the position to which it applies and what remains unconfirmed. Earlier source statements should remain distinguishable from later ones. That makes it possible to understand a revised funding share or payment schedule without erasing the history behind the previous view.
Brightline illustrates the value of this discipline. A recognizable operating business, a collection of legal entities and several financing relationships can coexist through a restructuring. For the holder of a particular debt interest, a reliable answer begins with that interest's documentary identity and continues through its own dated changes.