 Insights
The Collateral Did Not Move. Your Priority Did: What Rescue Finance Reveals About Secured Claims
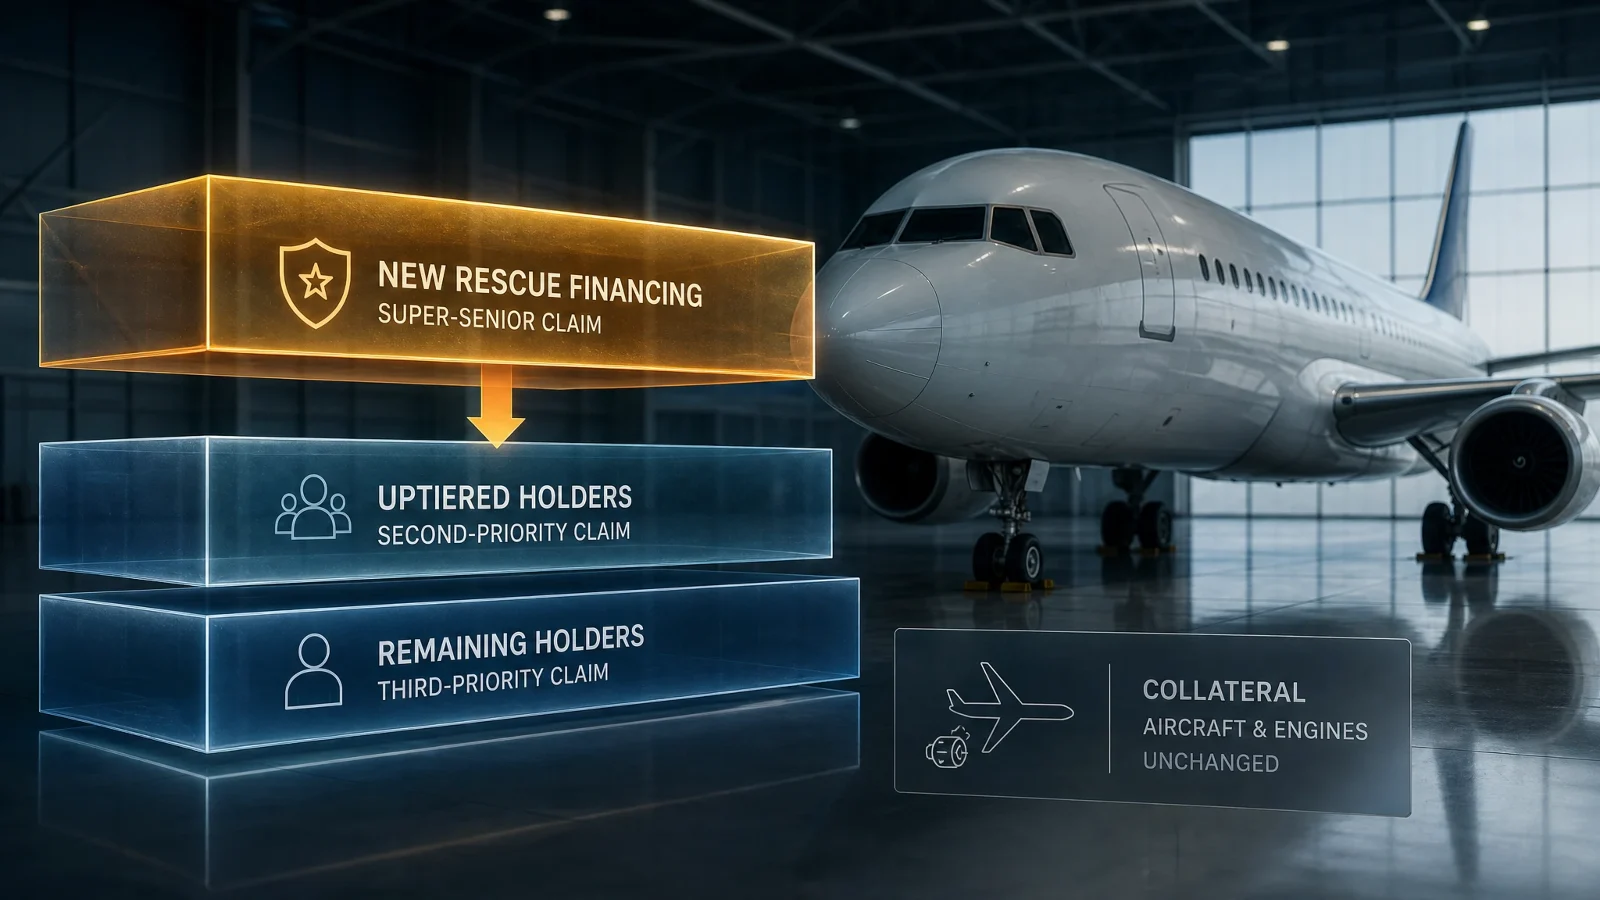
airBaltic’s proposed rescue financing shows why “senior secured” is not a permanent property of a debt instrument. The airline is seeking approval to raise up to €257 million of new super-senior debt that would rank ahead of existing 2029 bonds against collateral including eight aircraft and seven engines, while some existing holders could exchange into a new second-priority tranche and the remaining 2029 notes would fall to third priority. The collateral itself does not need to move for the...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
An issuer, bond name, maturity and collateral pool can remain unchanged while an investor's recovery position changes. Priority is a relationship among claims and governing rules, rather than a permanent characteristic of the physical collateral.
airBaltic's 2026 proposed rescue financing illustrates the distinction. Reuters reported a request to raise up to €257 million of super-senior debt due in February 2027, with first priority over collateral including eight aircraft and seven engines. Participating holders in a proposed uptier exchange would move to second priority, while remaining 2029 bonds would rank third. Reuters: Financing proposal
The bondholder meeting scheduled for 11 September was postponed to 15 September to give investors more time to review and vote. At the source article's drafting, the ranking change remained proposed, not a completed fact. A later outcome must not be inferred from that proposal or scheduled meeting. Reuters: Meeting postponement
Ask “senior to what?” and identify the shared collateral
“Senior secured” can be accurate at issuance while later new money, super-senior or priming debt, additional or permitted liens, exchanges and uptiering, covenant waivers, extensions, amendments, releases, substitutions and intercreditor changes alter relative rights.
Priority depends on competing claims over the same assets, security and intercreditor agreements, contractual subordination, statutory claims, insolvency rules, enforcement costs and jurisdiction. Separate claims may have different maturities, coupons, guarantees, security and enforcement rights, amendment powers and voting thresholds. “Secured debt” alone does not explain the order of payment.
| Illustrative claim stack | Collateral value | Claims and ranking |
|---|---|---|
| Before new money | 100 | Claim A: 80, first priority. |
| After proposed restructuring | 100 | New-money B: 30, first; uptiered A1: 40, second; remaining A2: 40, third. |
The assets need not move for the waterfall to change. Rescue finance may preserve a chance of survival while requiring first-ranking security, tighter covenants, fees, equity participation, control or other protections. Whether that trade-off is appropriate is a restructuring decision; the record's job is to show its effect accurately.
Current terms come from a document chain
Amendments can change coupon, maturity and payment timing, liquidity covenants, collateral and guarantors, thresholds and quorum, permitted debt and liens, enforcement, priority or waiver status. Keeping the new PDF without updating the explanation of current rights leaves the record incomplete.
airBaltic's investor-relations material lists original documentation alongside supplemental trust deeds, mortgage and asset-pledge amendments, additional security, assignments and meeting documents. airBaltic: Bonds 2024
A reviewer may need the original trust deed, successive supplemental deeds and bondholder resolution to establish current terms. Preserve the affected provision, original and amended text, approval and effective dates, expiry and waiver scope, consent and superseded version. The original prospectus is a starting point, not necessarily the current position.
Proposed, approved, executed, effective and funded are different
A claim can move from issue and outstanding status through amendment, capitalised coupon or covenant waiver, proposed priority change, consent request, exchange or non-exchange and legally effective ranking. The identifier can survive while the rights change.
Consent also has its own history: notice, convening, quorum, vote, achieved or failed threshold, and effective or failed resolution. A scheduled vote is not a held vote; support is not necessarily formal consent; approval does not establish execution or funding. Notice, record dates, proxies, eligible and excluded voters, adjournment and different reserved-matter thresholds can all matter.
Uptiering can split an original creditor base. Participating holders might receive a second-priority claim behind rescue money, while non-participants retain a third-priority claim. Record which holder exchanged, what it delivered and received, principal moved, old principal remaining, class and collateral, and effective date. A static bond master cannot explain every holder's result.
Value and the waterfall must be assessed together
A simplified recovery order might place enforcement costs before super-senior, second- and third-priority claims, unsecured creditors and equity. Actual structures can be more complex, with collateral allocations, standstills, enforcement control and release rights that require their own documents and scenarios.
An illustrative €200 million aircraft valuation does not determine an investor's recovery without the claims ahead, costs, other security and jurisdiction. If collateral remains worth €200 million, an original €150 million senior claim can suffer reduced effective coverage when €100 million of super-senior debt is added. Coverage changes even though the valuation is unchanged.
| Proposed record layer | Information to preserve |
|---|---|
| Instrument | Issuer and identifier, issue/maturity, currency, original/current principal, coupon, listing, law and current status. |
| Holder claim | Holder, principal and accrual, entitlement, exchange participation, amended rights, class and as-of date. |
| Collateral | Asset/owner/security provider, agreement and registration, jurisdiction, value/date, competing interests, release and provenance. |
| Ranking | Ahead, pari passu and behind classes, contractual/intercreditor sources, effective date, proposed/approved/effective state and reviewer. |
| Amendments | Document/provision, original/revised term, approval/effectiveness/expiry, holder consent, waiver scope and supersession. |
| New money | Facility/lender, amount and maturity, interest, security/ranking, purpose, commitment and funding, effective date and disclosed refinance plan. |
| Governance | Meeting/notice/record date, quorum and threshold, eligible holders, vote/result/resolution, effectiveness and source. |
| Waterfall | Costs/classes, collateral allocation and proceeds order, standstill/control/release rights, scenario, document and as-of date. |
| Provenance | Prospectus and trust/supplemental deeds, security/intercreditor documents, notices, announcements, exchange/registry records, valuations, extracted fields, legal review, dates/version/update. |
This is a proposed information model for review, not a claim that DaDepo calculates legal priorities or recovery waterfalls automatically.
Preparation should preserve authority for the restructuring decision
DaDepo's bounded contribution is private document-backed preparation and reviewable information. Suggested principal, maturities, coupons, collateral schedules, guarantors, source-described clauses, dates, thresholds, meeting details, waivers, exchange ratios and funding terms can help reviewers organise the package.
Future specialised comparisons could flag an outdated ranking, released collateral, an unrecorded lien, an exchange creating another class, a proposal presented as effective or an old waterfall used after restructuring. These are proposed checking capabilities, not asserted current automatic functions.
AI cannot determine amendment validity, sufficient consent, perfection, legal priority, intercreditor enforceability or recoveries. A Passport does not establish ranking, value collateral, calculate recovery, approve rescue finance, recommend consent, interpret a deed as legal advice, represent a creditor, negotiate a restructuring, run a meeting or exercise enforcement. Legal, restructuring, insolvency, trustee, lending, investment, enforcement and valuation services require their own express and lawful basis.
The proposed evidence chain would let an authorised reviewer see the instrument, holder, collateral, competing rights, changes, new money, consent and current waterfall while preserving what remains pending.
Questions for a creditor-priority review
Claim, collateral and ranking
- Instrument: Which debt instrument is being reviewed?
- Holder: What claim does this holder currently own?
- Principal: What amount is outstanding?
- Collateral: Which assets secure the claim?
- Security: What document creates that security?
- Competing claims: Which creditors share the collateral?
- Priority: Which claims rank ahead?
- Pari passu: Which claims share the same level?
- Subordination: Which claims rank behind?
- Source: Which document establishes ranking?
Change and consent
- Amendments: Has that document changed?
- Waivers: Which temporary waivers are effective?
- New money: Has rescue financing been proposed or funded?
- Priming: Would it rank ahead?
- Consent: Is creditor approval required?
- Meeting: Has the vote actually occurred?
- Threshold: What approval threshold applies?
- Quorum: Was quorum satisfied?
- Exchange: Can holders exchange into a different priority class?
- Participation: Did this holder exchange?
Current outcome and evidence
- Current class: What claim class applies now?
- Waterfall: What is the current proceeds order?
- Control: Who controls enforcement?
- Value: What is the latest collateral value?
- Coverage: How much debt ranks ahead?
- Pending changes: What is proposed but not effective?
- Provenance: Can every ranking statement be traced to a current document?
The same issue appears in private credit, leveraged and property loans, NPLs, rescue and warehouse lending, receivables, project finance and secured corporate debt. Priority is a time-dependent relationship among claims, documents and enforcement rights. The practical test is whether a reviewer can reconstruct who gets the first euro from this collateral today, without mistaking a proposal for an effective change.