 Insights
Wszystkie Insights
Wyszukuj i filtruj wszystkie opublikowane poradniki DaDepo dotyczące przygotowania udokumentowanych aktywów.
Przeglądaj według tematu
Wszystkie tematy występujące w opublikowanych poradnikach.
Przeglądaj poradniki
Wyszukuj i filtruj poradniki opublikowane po angielsku według odbiorców, typu aktywa, etapu lub tematu.
Centrum wskazówek
1–12 z 15 opublikowanych poradników-
01
 Poradnik
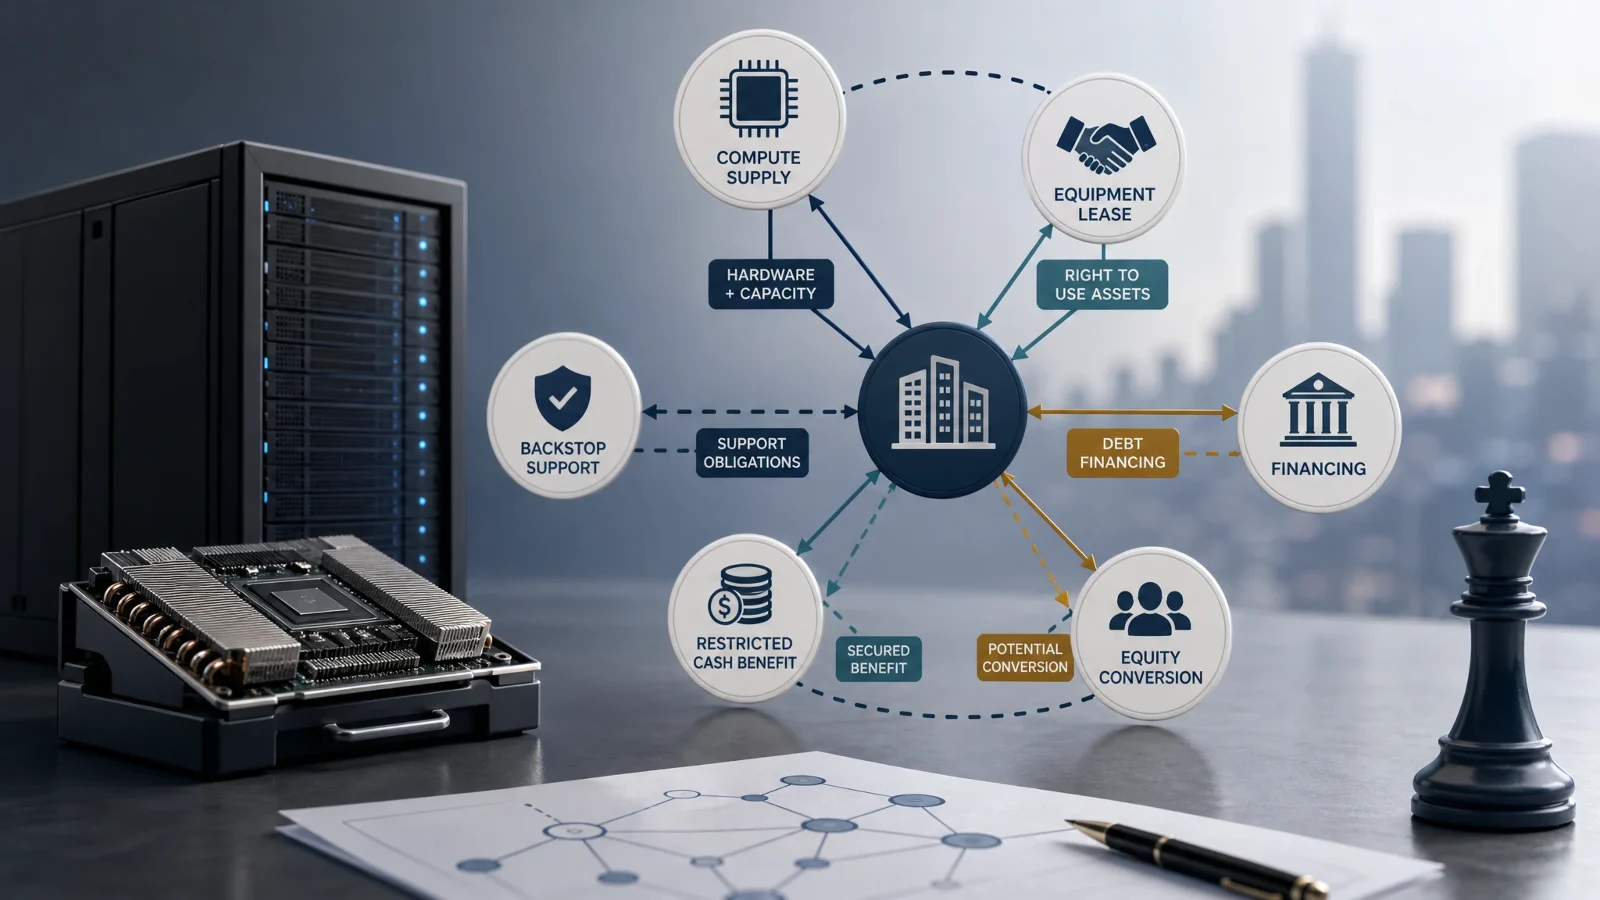
The Supplier Is Also the Lender: Why Vendor-Financed Compute Needs a Conflict-Aware Asset Graph
Anthropic’s IPO prospectus reveals a financing structure in which Broadcom is not only a critical compute and hardware partner but may also provide up to $42 billion of financing tied to Anthropic’s five-year TPU compute commitments. Reuters reported that the convertible-note capacity could fund about one-third of Anthropic’s $125.2 billion TPU lease commitment, while Broadcom’s own SEC filing says the notes may be issued under certain circumstances and must be used for obligations under the...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Etap
- Learn
- Tematy
- vendor finance compute equipment leasing
-
02
 Poradnik
The Payment Is Overdue. The NPL Flag Says No: What Vanke Reveals About Credit Classification State
Reuters reported in September 2026 that Chinese financial regulators had informally asked some major banks not to classify overdue loans to China Vanke as non-performing, while also encouraging maturity extensions and, in some cases, deferred interest collection. The reported guidance is not a published regulatory rule, but it exposes an important private-credit data problem: contractual payment state, days past due, forbearance, restructuring, regulatory classification, accounting...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- NPL
- Etap
- Learn
-
03
 Poradnik
The Project Was Funded. The Debt Did Not Move: What $18 Billion of AI Loans Reveals About Distribution Risk
Project Jupiter, a New Mexico data-center development linked to Oracle and OpenAI, raised about $18 billion of project-finance loans from a large bank group in late 2025. The financing was designed to be distributed more broadly to banks and institutional investors. By September 2026, however, Financial Times reporting cited by Reuters said syndicate banks were quoting the loans at 89–91 cents on the dollar and that attempts to sell the debt more widely had stalled, leaving banks with more...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Secured loan
- Etap
- Learn
-
04
 Poradnik
An Insured Invoice Is Still Not a Verified Receivable: What Radiant World Reveals About Trade-Credit Evidence
The Radiant World disputes have moved beyond lenders and commodity counterparties into trade-credit insurance. The Financial Times reported that Zurich and Allianz Trade wrote policies covering transactions linked to the embattled iron-ore trader, including Zurich cover tied to non-payment by counterparties such as Glencore. That adds a new layer to a case already involving allegations that some invoices used in financing were invalid or had already been paid. The lesson is not that...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Invoice
- Etap
- Learn
- Tematy
- receivables verification invoice finance trade credit insurance
-
05
 Poradnik
The Invoice Exists. The Receivable May Not: What Radiant World Reveals About Trade-Finance Asset Identity
The widening Radiant World disputes show why an invoice is not enough to establish a financeable receivable. In one Singapore lawsuit, Incomlend alleges that it advanced $31.7 million against two Glencore invoices with a combined face value above $34 million, only to be told later that the invoices had already been paid and that the underlying contracts were not genuine. Separately, a Jefferies-linked fund has obtained a London freezing order of up to $499 million against Radiant World, its...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Receivable
- Etap
- Learn
- Tematy
- invoice and trade finance receivables asset identity
-
06
 Poradnik
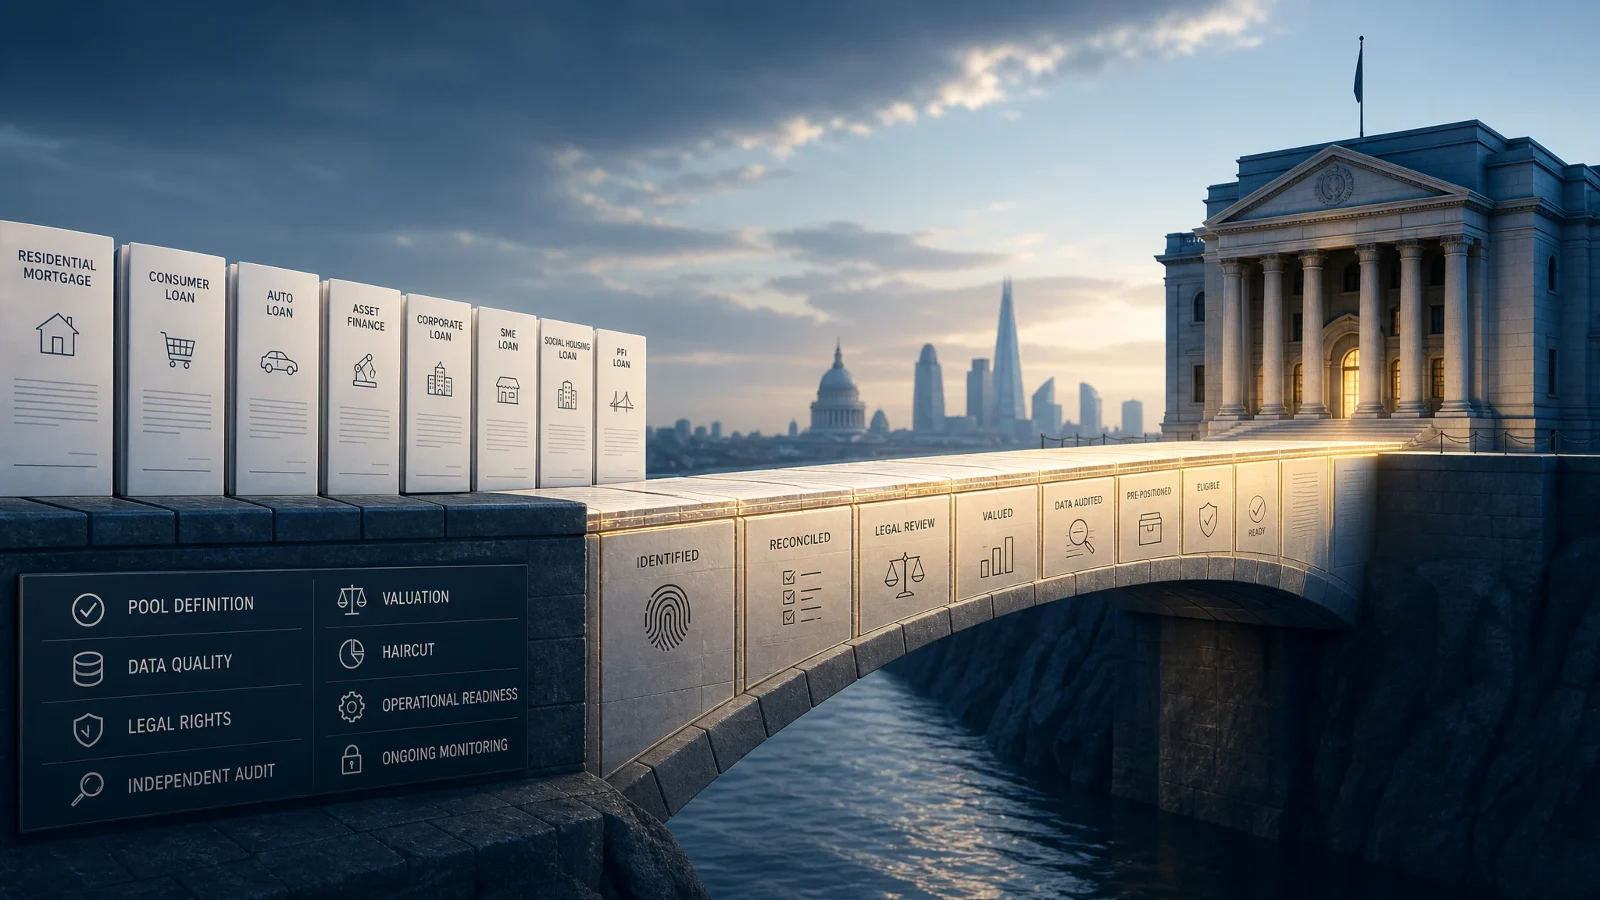
When a Loan Portfolio Becomes Central-Bank Collateral: Eligibility Is an Asset State
British banks are increasingly mobilising less-liquid credit assets through the Bank of England’s Sterling Monetary Framework. Level C collateral held by the Bank more than doubled over the year to £17.8 billion, while the eligible universe includes residential mortgages, consumer and auto loans, asset finance, corporate and SME loans and other loan portfolios. The deeper lesson is that a loan does not become central-bank collateral merely because it exists: eligibility depends on portfolio...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Secured loan
- Etap
- Learn
- Tematy
- central bank collateral collateral asset readiness
-
07Poradnik
When the Collateral Is Compute: What a GPU-Backed Loan Actually Owns
GPU-backed private credit is developing into a distinct form of equipment and infrastructure finance. Bullish provided USD.AI with a $100 million stablecoin-based facility in August 2026 to support loans secured by high-performance computing assets, while USD.AI reported more than $281 million of lifetime deployed capital across GPU financings by month-end. The challenge is that the collateral is mobile, rapidly depreciating, technically specialised and economically dependent on data-centre...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Secured loan
- Etap
- Learn
- Tematy
- asset backed finance collateral asset identity
-
08Poradnik
A Maturity Extension Is Not a Refinance: Why Private Credit Needs Loan-State History
US software borrowers are increasingly using amend-and-extend transactions to push debt maturities out by two or three years while lenders demand higher pricing, tighter covenants, stronger collateral protections and better reporting. The loan can remain the same legal asset while its contractual and economic state changes materially. That makes amendment history, consent provenance and effective-dated loan terms essential infrastructure for private credit.
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Secured loan
- Etap
- Learn
-
09Poradnik
Buying Your Own Debt Is Not the Same as Cancelling It: Why Loan Ownership Needs a Lifecycle
Guggenheim’s August 2026 purchase of portions of a roughly $1.2 billion loan linked to its asset-management business illustrates a subtle but important loan-state problem. An affiliate can buy debt in the secondary market and hold it as an investment while the loan remains outstanding. Holder, borrower, related-party status, market price, outstanding principal and cancellation are therefore separate states that a reliable private-credit record needs to preserve.
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Secured loan
- Etap
- Learn
-
10Poradnik
The Financing That Stays With the Building: Why C-PACE Is Becoming an Institutional Asset Class
Commercial Property Assessed Clean Energy finance is moving from a specialist sustainability product into institutional real-estate credit. Nuveen’s fourth C-PACE lending fund reached a first close above $1 billion in August 2026, taking commitments across the series above $3 billion. The unusual part is the asset itself: repayment is structured through a property assessment, the obligation is tied to the property rather than only its current owner, and the resulting lien must coexist with...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Secured loan
- Etap
- Learn
-
11Poradnik
The Token Is the Last Step: Why a Receivable Must Become a Reliable Asset Before It Goes On-Chain
POSCO-related trade-finance projects in July and August 2026 show a more useful model for tokenisation than simply putting invoice data on a blockchain. In the latest transaction, invoices, purchase orders, credit notes and shipment documents were reconciled before verified receivables were registered on-chain. The lesson is fundamental: a token can preserve and move an asset state, but the receivable first needs a reliable identity, evidence chain, current balance and ownership record.
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Receivable
- Etap
- Learn
-
12Poradnik
Economics Without Ownership: Why Legal Title Still Matters in Asset Finance
Participation-interest structures can give an SPV the economics of loans or receivables while legal title remains with an originator, sponsor or partner bank. In normal conditions the cash flows may look almost identical to a direct-title structure. Under stress, the distinction can determine control of collections, enforcement, bankruptcy isolation and the investor’s actual route to the underlying assets. Asset infrastructure therefore needs to model legal title, economic rights and ...
Przeczytaj artykuł- Odbiorcy
- Credit manager
- Aktywo
- Receivable
- Etap
- Learn