 Insights
The Loan Is Not the Only Leverage: Why Private Credit Needs a Fund-Level Debt Map
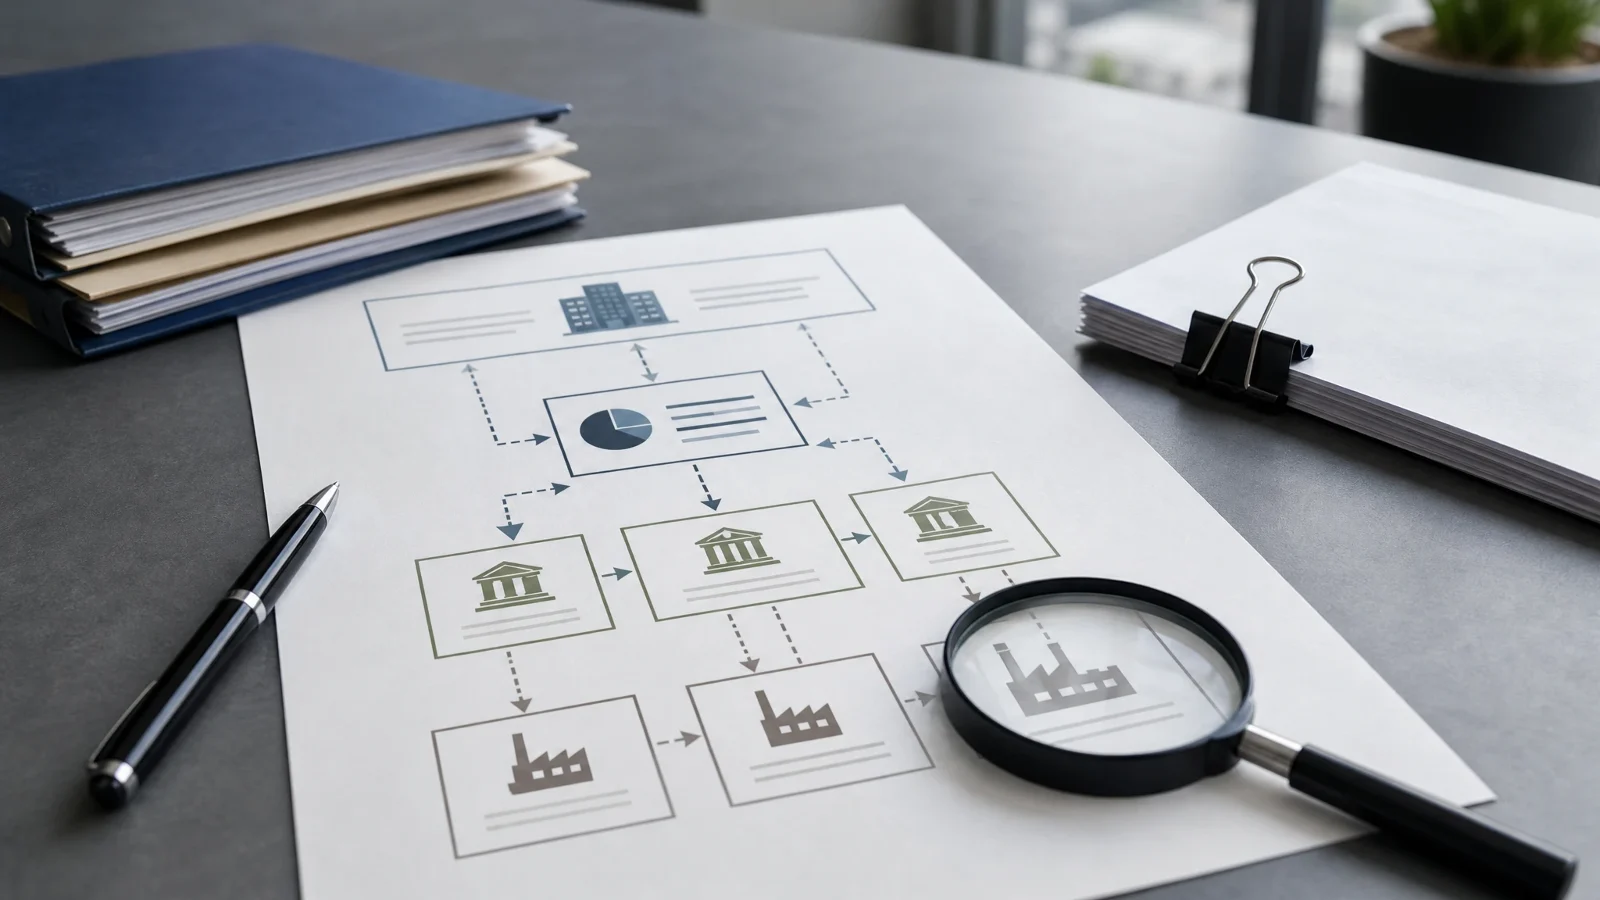
A private-credit fund can own loans and borrow against its portfolio, while a feeder adds another financing layer. Each claim has different debtors, collateral and calculation rules. A useful debt map keeps those layers separate, connects their evidence and shows how a change in portfolio value can affect fund financing and investor cash flows.
A loan can be performing while the fund that owns it is losing room under its own financing agreement. The borrower may still pay interest on time, yet a lower portfolio valuation can reduce the fund's borrowing capacity. If another vehicle has borrowed against its fund interest, that financing adds a further set of obligations and cash-flow constraints.
This is why borrower analysis alone cannot describe every private-credit exposure. Borrower debt, fund borrowing and feeder financing belong to different balance sheets. Reviewing them together requires a map of the entities, claims and supporting evidence, with a clear distinction between an economic connection and a legal right.
The market estimates describe different things
The Financial Stability Board's May 2026 report estimated global private-credit assets at $1.5–2.0 trillion at end-2024. Across its reporting members, available data captured approximately $220 billion of drawn and undrawn bank credit lines to private-credit funds, while commercial estimates ranged from $270 billion to $500 billion. These are differently scoped observations, and a line's undrawn commitment is not outstanding debt. The FSB also identified gaps in fund- and loan-level data and warned about opaque layers of leverage. FSB: private-credit vulnerabilities, 6 May 2026
The Wall Street Journal's reporting puts an estimated $500 billion of borrowing by U.S. private-credit managers at the centre of its transparency question. That estimate has a different geography and definition from the FSB's global asset figure and bank-line observations. It should not be added to either as though the amounts were disjoint categories. Wall Street Journal: Opaque Private-Credit Leverage Raises Risks for Investors
A third measure concerns the broader fund-finance market. Reuters reported on 27 April 2026 that Moody's put that market above $1 trillion, with private-credit funds participating as both borrowers and lenders in NAV financing. Fund finance also serves strategies beyond private credit. Its total is therefore not a measure of additional debt sitting exclusively above private-credit loans. Reuters report, reproduced by Investing.com
The useful question for an individual review is more precise than the headline totals: which legal vehicle owes which amount, on what date, and what supports repayment? A market estimate can motivate that question. It cannot answer it for a particular fund.
Start with the borrower at each layer
Consider a fund holding a loan to Company A. The company's debt-to-earnings ratio describes the company. A separate loan taken out by the fund describes the fund. Financing at a feeder that owns an interest in the fund describes another entity again. These liabilities may depend on related economic performance, but that does not make them one instrument or create a single meaningful leverage ratio.
Fund-finance structures also use different sources of support. Standard Chartered describes subscription facilities as generally sized against eligible uncalled investor commitments, with advance rates and concentration protections. NAV financing looks toward portfolio value and cash flows; hybrid structures combine the two bases. The facility documents establish the actual borrower, collateral and calculation rules. Standard Chartered: Fund Finance at Scale, 10 September 2026
| Financing layer | Starting point for the review | Distinction to retain |
|---|---|---|
| Operating-company loan | Company, loan agreement, outstanding balance and any security | Borrower leverage describes this company's obligations. |
| Subscription facility | Fund borrower and eligible uncalled investor commitments | Committed investor capital and money already called are different records. |
| NAV facility | Named borrower, portfolio support and contractual value definition | Fund-reported NAV and the facility's calculation base may differ. |
| Hybrid facility | The agreement's combination of commitment and portfolio support | Record how each component contributes; avoid counting the same support twice. |
| Feeder financing | Borrowing vehicle, fund interest and financing documents | Identify which investors and interests are exposed to this additional layer. |
This is a review framework, not a statement that every fund uses all five structures. A fund may have no borrowing, several facilities or financing in a subsidiary. The entity names and obligations need to come from the documents, rather than from the manager's brand or a diagram's convenient labels.
Economic dependence does not establish legal recourse
Suppose a fund lender relies on distributions from a portfolio-holding vehicle. A deterioration in the portfolio can weaken that repayment source. Whether the lender has security over particular loans, shares, accounts or other rights is a separate documentary question. The fact that its repayment ultimately depends on Company A does not by itself make Company A its debtor.
A portfolio loss may reduce the value or cash available to service another financing layer. Trace the dependency and state the scenario assumptions.
The agreements identify the debtor, collateral, guarantees and any enforcement rights. An economic link alone does not establish direct recourse or priority.
The same discipline applies when a bank appears at more than one layer. A bank's corporate revolving loan and its facility to a fund may relate to the same underlying business, but each exposure has its own obligor and terms. Summing them without an aggregation boundary can obscure the structure; collapsing them into one claim loses the rights that matter in a recovery analysis.
An evidence map should therefore label its connections. “Holds a loan,” “borrows under a facility,” “pledges a specified right” and “receives distributions from” are different statements. Each needs its own source and effective date. A reviewer can then follow an economic stress path without mistaking it for a chain of automatically enforceable claims.
A valuation change can move the ratio without a new draw
The following example is hypothetical. Assume a vehicle holds three loan positions with a gross portfolio value of $300 million and owes $90 million under one facility. For this illustration, all three positions qualify at full value for the facility's denominator, and there are no other assets, liabilities, fees or currency effects. One position falls in value from $100 million to $50 million; the facility balance stays unchanged.
| Illustrative measure | Before the markdown | After the markdown |
|---|---|---|
| Eligible gross portfolio value | $300 million | $250 million |
| Facility debt outstanding | $90 million | $90 million |
| Debt / eligible gross portfolio value | 30.0% | 36.0% |
| Net asset value after this debt | $210 million | $160 million |
| Debt / net asset value | 42.9% | 56.25% |
The first ratio rises from $90m / $300m = 30% to $90m / $250m = 36%. Calling the $300 million denominator “fund NAV” would hide the $90 million liability. Under this simplified balance sheet, net asset value is $210 million before the loss and $160 million afterwards, producing a different debt-to-NAV ratio. A real agreement may define its denominator differently again, including through exclusions, adjustments or a specified valuation process.
Now assume, solely for the example, a maximum contractual ratio of 35% of eligible gross portfolio value. Arithmetic headroom moves from 5 percentage points below that threshold to 1 percentage point above it. That calculation identifies a question for review. The agreement's testing dates, cure provisions, waivers and other conditions determine the contractual consequences; the table alone does not establish an enforceable default.
This is also why a loan's payment status and its value should remain distinct. A timely interest payment answers a different question from a valuation used in a facility calculation. Neither record should silently update the other, and a ratio should identify both the debt-balance date and the valuation date used to compute it.
Ownership, eligibility and cash availability need separate evidence
A fund's asset schedule establishes what its reporting says it holds. A borrowing-base certificate addresses what a particular facility counts under its rules. Those sets can differ. In a hypothetical facility, a holding might remain on the asset schedule while a concentration limit reduces its borrowing-base contribution. The relationship to the facility has changed even though the holding has not been sold.
Eligibility is consequently a statement about an asset under a named facility, rule set and date. “Eligible” without those qualifiers is too imprecise for comparison. An asset accepted by one facility may be excluded by another, or included only after a haircut. A reviewer also needs to distinguish a manager's reported treatment, the lender's acceptance where required and an unresolved question about the governing terms.
Cash follows a related but separate path. If a facility restricts distributions in specified circumstances, cash received from otherwise performing loans may not be freely distributable to investors. The actual restriction and its application must be evidenced. Borrower payment, fund cash receipt, a distribution entitlement and cash available to a feeder are different events.
- Identify the loan event and the source supporting its date and reported value.
- Check which portfolio and facility calculations use that loan and valuation version.
- Reconcile the reported debt balance, eligible value and contractual test definition.
- Review any applicable cure, waiver or distribution condition with the responsible decision-maker.
- Record the conclusion and unresolved questions for the relevant fund and investor layer.
The arrows describe a review sequence. They do not mean that a markdown automatically causes a breach, blocks a distribution or gives an investor a redemption right. Those outcomes require the relevant terms and facts at each step.
Build the map from a dated evidence pack
A useful debt map starts small enough to inspect. Identify the exact portfolio-owning vehicle, then connect its asset records to each financing agreement and any relevant investor or feeder layer. Keep a facility's total commitment, drawn debt and remaining availability separate: the undrawn portion may still be subject to conditions, and subtraction alone does not prove that it can be borrowed.
| Record to keep | Minimum evidence to carry forward | Question it helps resolve |
|---|---|---|
| Loan position and holder | Loan/tranche reference, source-named holder, balance, currency, date and portfolio schedule | Which reported position is being analysed? |
| Portfolio value and net NAV | Valuation version, preparer, as-of date, methodology and liability reconciliation | What does this value include or deduct? |
| Fund facility | Borrower, lender, type, commitment, drawn amount, maturity, amendments and agreement references | Where does the borrowing sit and which terms apply? |
| Borrowing base and support | Included assets or commitments, exclusions, haircuts, concentration treatment and dated certificate | What supports this facility's reported availability? |
| Tests and cash restrictions | Ratio definitions, thresholds, testing dates, reported result, cure or waiver evidence and distribution terms | What was assessed, and what remains unresolved? |
| Investor or feeder layer | Vehicle and interest identity, any financing or pledge, capital commitments and relevant cash-flow rights | Which additional obligations affect this investor's position? |
Dates need more than a single “last updated” field. A report issued in October may describe a September valuation, a facility balance may be more recent, and an amendment may take effect between the two. Preserve these dates alongside document versions and reviewer decisions. An internally consistent calculation can still answer the wrong question if its inputs refer to incompatible periods.
ILPA's July 2024 NAV-facility guidance offers a useful transparency reference: it calls for clearer LP–GP engagement and standardized disclosures. Its recommendations specifically concern private-equity strategies; they should not be presented as universal private-credit requirements or substituted for a fund's governing documents. The transferable review principle is to make the financing and its implications visible to the people assessing it. ILPA: guidance on NAV-based facilities
DaDepo can help prepare the documentary basis
DaDepo's supported contribution begins with private document preparation. Supported files can be brought into a private draft, and available contractual-role evidence tools can retain source-described parties and roles with references and review decisions. Passport preparation can organize the evidence basis and outstanding questions. These are useful inputs to a financing review because they make its supporting material easier to locate and examine.
That preparation does not supply a fund debt graph, calculate official NAV, determine collateral eligibility or decide covenant compliance. A proposed map spanning vehicles and facilities remains an analytical model for qualified reviewers to establish from the documents. Preparing evidence also remains separate from signing, Passport issuance and disclosure; each retains its applicable permissions and confirmations.
For the reader assessing a portfolio, the practical objective is an explanation that survives a change in viewpoint. A borrower analyst should be able to see the company loan; a fund lender should be able to identify the support for its own facility; and an investor should be able to trace the additional obligations affecting its interest. Keeping those claims distinct, with dated evidence connecting them, makes the effect of another financing layer possible to review.