 Insights
Institutional Capital Does Not Buy Projects: Why Private Assets Need to Become Portable Before They Become Investable
The World Bank Group says it mobilised a record $112 billion of private capital in FY2026 and wants to exceed $200 billion within two to three years. The strategic shift is not simply to originate more projects. It is to standardise and package loans into structures that pension funds, insurers and asset managers can hold. IFC’s Emerging Markets Securitization Program shows the model in practice: two CLO transactions have issued more than $1 billion of securities backed by 119 IFC-originated...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
Large institutional investors can have substantial capital to deploy without wanting to underwrite thousands of private loans individually. Development-finance institutions therefore face two connected tasks: originate worthwhile projects and prepare financing structures that institutional investors can assess at scale. On 17 September 2026, the World Bank Group said it had mobilised a record $112 billion of private capital in FY2026. The figure had been $35 billion in FY2022. World Bank: Record private capital mobilisation for developing countries Reuters reported that World Bank President Ajay Banga wants to lift annual private-capital mobilisation to more than $200 billion within two to three years. The important part is how.
The World Bank is working to standardise and package loans so that pension funds, insurers and asset managers can invest at scale. Banga’s explanation was unusually direct:
Large pools of institutional money do not typically come for individual projects.
Reuters: World Bank boosts private capital mobilisation to record $112 billion That creates a useful private-market principle:
An asset must become portable before a portfolio can become scalable.
The specialist records and lifecycle models below describe review requirements and illustrations. They should not be read as claims that software has verified the rights or that every proposed field and relationship is an existing DaDepo feature.
From individual projects to comparable financing structures
A development project can be investable on its own. It may have a borrower, a loan agreement, collateral, financial statements, covenants, repayment history, environmental and social documentation, insurance, guarantees, and a credit assessment. But institutional investors often need something else. They need repeatability. They need to compare one exposure with another. They need eligibility rules. They need portfolio data. They need standard reporting. They need a structure they already know how to hold. That is the difference between “Good project” and “Investable asset class”. The World Bank Group’s private-sector arm, IFC, has created the Emerging Markets Securitization Program, or EMSP. The programme packages IFC-originated loans into tradable securities.
IFC says that two transactions have now issued more than $1 billion. The combined portfolios contain 119 IFC-originated loans across industries and regions. IFC: Emerging Markets Securitization Program That creates a visible chain:
- Individual borrower
- Private loan
- Standardised portfolio data
- Eligible pool
- CLO
- Rated tranche
- Institutional investor
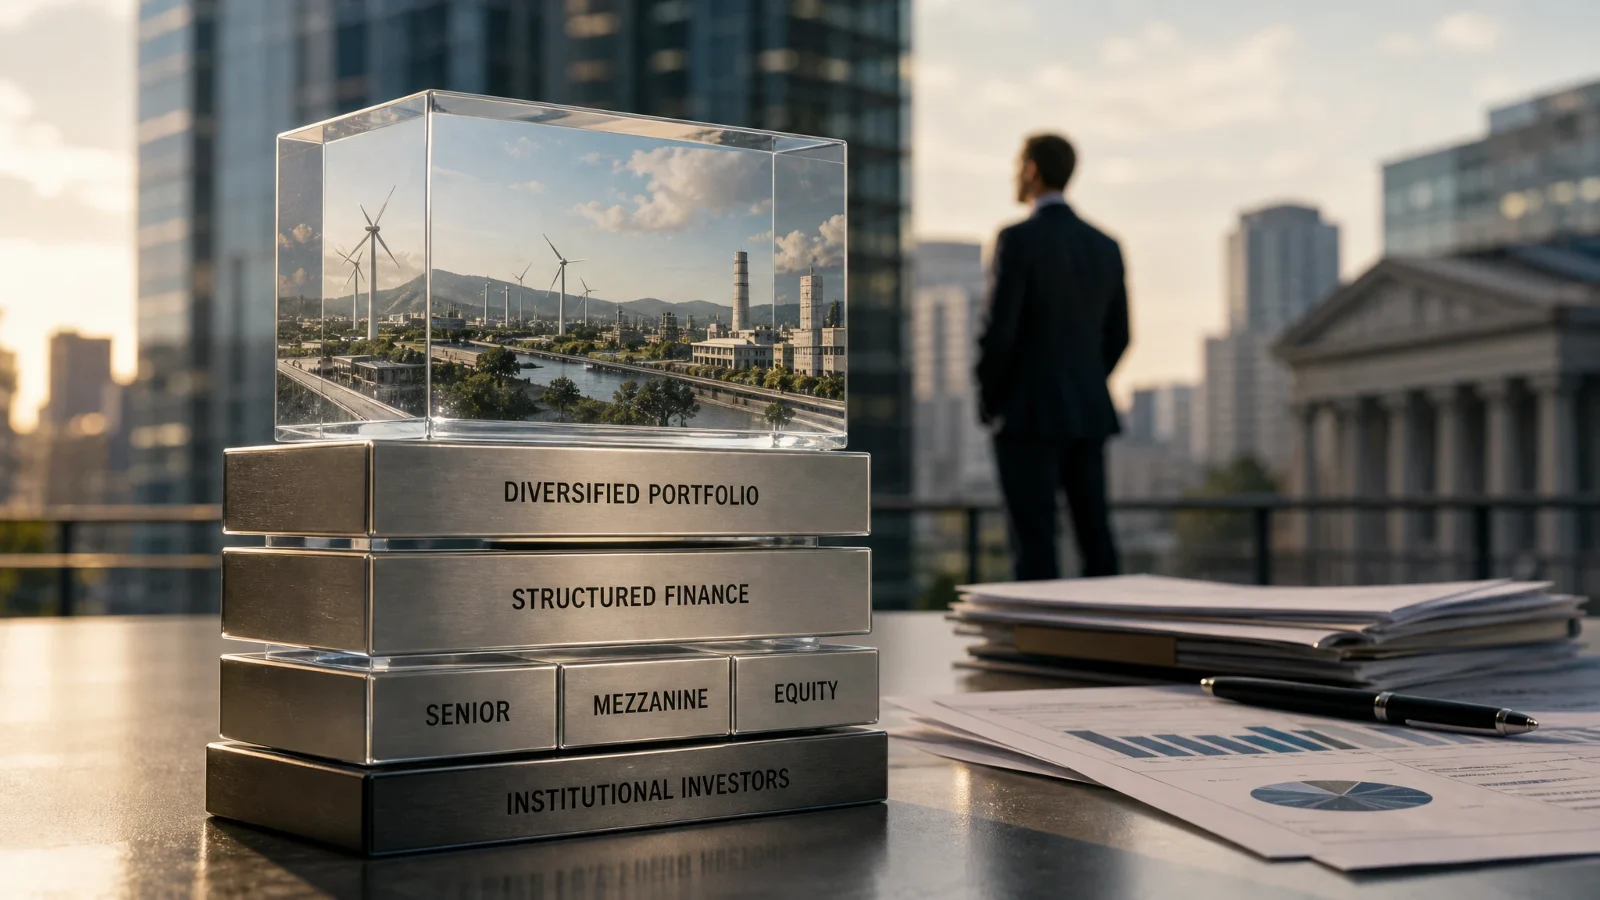
The underlying loan does not disappear when the CLO is issued. It becomes one component of a larger investment structure. IFC closed its second EMSP transaction in June 2026. The $509 million CLO packaged 62 IFC-originated loans. Its structure included: $320 million Aaa-rated senior tranche; $50 million Aa1-rated tranche; $80 million mezzanine tranche insured by a consortium of credit insurers; and $59 million equity tranche held jointly by IFC and the UK Foreign, Commonwealth & Development Office. Participating investors included: PIMCO, L&G, Shizuoka Bank, Sona Asset Management, and other institutional investors. IFC: Second Emerging Markets CLO The structure matters because investors do not need to become the bilateral lender to every underlying borrower.
They receive exposure through a familiar portfolio instrument. A common mistake is to think: “Standardised” means: “Identical”. It does not. The 119 underlying loans can differ by: country, borrower, sector, currency, tenor, interest rate, collateral, covenant package, risk, repayment profile, guarantee, legal framework, and servicing history. Standardisation means those differences can be represented consistently. The objective is not to erase heterogeneity. It is to make heterogeneity comparable.
Preserve asset identity, membership, eligibility and current balance
Suppose a portfolio contains 119 loans. A portfolio-level record such as “EMSP portfolio” is useful. It is not enough. For every loan, the system may still need borrower, facility identifier, origination date, original amount, current principal, currency, maturity, interest terms, payment schedule, collateral, guarantee, covenant status, arrears, restructuring history, transfer status, portfolio membership, and source evidence. The portfolio cannot substitute for the loan record. Once loans are pooled, a new asset relationship appears. The system needs to preserve Loan A, Loan B, Loan C and the other loans separately, alongside the portfolio, SPV, tranche and investor records.
Each layer has its own lifecycle. A borrower may prepay. A loan may default. A loan may be substituted. A tranche may amortise. A rating may change. An investor may sell its note. The asset infrastructure must preserve these events without confusing the layers. A loan can move through portfolio states such as:
- Candidate
- Eligible
- Selected
- Transferred
- Active in portfolio
An active loan may later become prepaid, defaulted, or substituted / removed. A field called “Portfolio: EMSP II” does not preserve that history. The system needs the event that created or ended portfolio membership. Before a loan enters a portfolio, it may need to satisfy defined rules. Possible eligibility criteria can concern: jurisdiction, borrower type, sector, credit quality, arrears, maturity, currency, documentation, concentration, transferability, sanctions, environmental criteria, collateral, guarantee status, and other transaction-specific conditions. The exact EMSP eligibility rules should be read from the governing documents. The general infrastructure principle is: “Eligible” should resolve into: Eligibility rule, Current asset field, As-of date, Source, and Reviewer.
A loan can be eligible when transferred and later deteriorate. The borrower can miss a payment. A covenant can be breached. A guarantee can expire. Collateral value can change. The borrower can restructure. The loan still exists. Its portfolio state may change. That means eligibility and performance need time-aware records. A loan may have been originated at: “$20 million”. Years later its current balance may be “$12.4 million”. A portfolio record must distinguish original commitment, amount drawn, principal outstanding, accrued interest, overdue amount, undrawn commitment, repayments, prepayments, and write-offs. The original contract amount is not the current asset exposure.
Separate the loan, security, guarantee and transfer conditions
A secured private loan may connect to:
- Loan
- Security agreement
- Collateral asset
The collateral can have its own: identity, owner, location, valuation, priority, encumbrance, insurance, release history, and enforcement state. Pooling the loan into a CLO does not collapse those objects. The portfolio needs to preserve them. Development-finance loans may also have sponsor guarantees, parent guarantees, political-risk protection, multilateral support, insurance, or other risk-sharing arrangements. Those rights can materially affect investor exposure. A field such as “Guaranteed: Yes” is too shallow. The record should ask: “Who guarantees what?”, “For how long?”, “Under which conditions?”, “Has the guarantee been called?” Traditional bilateral lending can look like:
- Originate
- Hold
- Collect
- Maturity
An originate-to-distribute model adds:
- Originate
- Season / monitor
- Standardise
- Select
- Transfer or participate
- Pool
- Issue securities
- Continue servicing / monitoring
That is a different information problem. The asset has to remain understandable after it leaves its original bilateral context. A loan can be economically attractive and still difficult to transfer. Transfer may depend on borrower consent, lender consent, assignment clauses, participation mechanics, local law, regulatory restrictions, tax, confidentiality, security transfer, registration, sanctions, and notice. A standardised asset record should include transferability as a sourced state. Not as an assumption. Legal transferability is only one part. Operational portability also matters. A loan is easier to package when another institution can understand it without reconstructing the entire origination file. That requires: identity, terms, balance, performance, security, covenants, valuation, transfer restrictions, evidence and current state.
Portability is partly a legal property. It is also an information property.
Keep the wrapper, tranches, insurance and data lineage connected
A pension fund or insurer evaluating a diversified portfolio may need to compare exposures across sectors, geographies, currencies, maturities, ratings, internal credit grades, collateral, concentration, performance, environmental risk, and expected cash flows. That is hard if every underlying loan is represented by a bespoke PDF folder. It becomes easier if each loan has a structured, source-backed record. A CLO gives institutional investors a familiar security. That is useful. It can also create abstraction. The investor may own a note rather than the underlying loans. But the quality of the note still depends on the underlying portfolio. A robust system therefore needs both: “Security-level record” and “Underlying asset-level records”. The wrapper improves access.
It should not destroy transparency. In a CLO, different investors can have different rights over the same pool. The structure may contain a senior tranche, a mezzanine tranche and an equity tranche. Those positions differ in: priority, coupon, expected loss, cash-flow entitlement, voting rights, control rights, maturity, rating, and sensitivity to portfolio performance. The underlying portfolio is shared. The investor rights are not. In the second EMSP transaction, the mezzanine tranche was insured by a consortium of credit insurers. That means the structure contains another chain:
- Underlying loans
- Portfolio credit risk
- Mezzanine tranche
- Insurance protection
The insurance is not the loan. It is not the tranche. It is a risk-transfer contract around the tranche. Again, the graph matters. IFC says the programme allows it to recycle capital into new lending. The logic is:
- Originate loans
- Package exposure
- Bring in institutional capital
- Release or recycle capital
- Originate more loans
For that model to scale, the assets must survive the transition from origination system to capital-markets structure. Identity continuity becomes operational infrastructure. A one-off transaction can be assembled manually. A repeat programme creates a different problem. After several issuances, the manager needs to answer: “Which assets belong to which vintage?”, “Were definitions consistent?”, “Did the same borrower appear in several pools?”, “Which assets prepaid?”, “Which eligibility rules changed?”, “Can performance be compared across vintages?” A reusable asset schema becomes more valuable with every transaction. An investor-visible field might originate from:
- Borrower document
- IFC system
- Portfolio dataset
- Transaction report
- Investor disclosure
If a number changes, the institution needs to know why. A source-backed model can preserve: original source, extraction date, transformation, reviewer, effective date, portfolio snapshot, and later correction. That is essential for trust.
A proposed two-level record and the limits of AI standardisation
Underlying loan identity
Borrower, borrower identifier, facility identifier, lender, origination date, currency, original commitment, current principal, maturity, interest terms, payment schedule, and governing law.
Performance
Scheduled payment, amount paid, days past due, arrears, default state, restructuring, waiver, covenant breach, watchlist state, internal credit grade, effective date, and source.
Security and support
Collateral, collateral identifier, security type, priority, valuation, valuation date, guarantor, guarantee amount, insurance, risk-sharing arrangement, and enforcement state.
Transferability
Assignment permitted, participation permitted, consent required, notice required, confidentiality restriction, jurisdictional restriction, tax issue, security-transfer mechanics, transfer event, and current holder.
Portfolio membership
Candidate date, eligibility assessment, eligibility result, selection date, transfer date, pool identifier, portfolio vintage, substitution, removal, prepayment, default, and current membership state.
Portfolio
Portfolio identifier, closing date, asset count, aggregate balance, geography, sector, currency, concentration, weighted maturity, performance metrics, eligibility rules, and reporting date.
Securitisation
SPV, transaction, tranche, principal, rating, coupon, priority, investor, insurance, listing venue, payment waterfall, and current security state.
Provenance
Loan agreement, amendment, borrower financials, collateral document, valuation, payment record, eligibility test, transfer document, portfolio tape, investor report, rating document, effective date, version, and reviewer.
AI-assisted preparation
The analytical uses discussed here are possibilities for document review, subject to source access and human judgement. They are not a claim that DaDepo currently performs every proposed check or reaches the resulting legal or financial conclusions. AI can help extract loan terms, normalise borrower names, map collateral, identify maturity dates, compare covenant language, detect missing fields, reconcile balances, classify amendments, build portfolio tapes, find duplicate borrower exposures, detect inconsistent currencies or units, and trace changes between reporting periods.
AI should not independently decide: whether a loan is legally transferable; whether security is perfected; whether a borrower is creditworthy; whether an asset satisfies transaction eligibility; whether a rating is appropriate; whether a guarantee is enforceable; whether a transfer is a true sale; whether a portfolio is suitable for an investor; or how a security should be priced. Those require authoritative documents, transaction rules and professional judgment.
The bounded DaDepo contribution and its limits
DaDepo can help prepare a private document-backed asset draft and retain source-linked information for human review. The private Parties and contractual roles table can record source-described party, contract and role rows with document and clause references, optional source dates, and pending, confirmed or rejected review decisions. The same party can appear in different contracts and roles. Where current compatible completed analysis is available, AI may suggest pending role rows; a user reviews and confirms or rejects them. These records do not establish legal title, priority, enforceability, the validity of a reported exposure or the outcome of a dispute.
The specialist information model for originate-to-distribute portfolios is a proposed information requirement. A complete relationship graph, automatic exposure reconciliation and automatic cross-contract decisions are not delivered capabilities established by this article. DaDepo does not need to become a CLO manager or development bank. The useful role is upstream. A proposed specialist workflow could make private assets easier to inspect, compare and package before they reach capital-markets infrastructure. A structured path could be:
- Loan
- Asset Passport
- Comparable asset data
- Eligibility
- Portfolio
- Transfer
- Securitisation
- Institutional investor
The Asset Passport does not create the securitisation. The proposed model aims to reduce the information friction before it. Creating or reviewing a loan or debt-portfolio Asset Passport does not mean that DaDepo has originated a loan; underwritten a borrower; made a credit decision; determined a loan is transferable; obtained borrower consent; perfected security; determined portfolio eligibility; structured a CLO; created an SPV; assigned a rating; arranged a securities offering; provided credit insurance; acted as trustee; acted as asset manager; provided brokerage; priced a security; recommended an investment; or provided legal, regulatory, tax, accounting, investment or valuation advice.
Important: DaDepo provides technology and information tools. It does not provide lending, underwriting, securitisation, ratings, asset management, brokerage, custody, trustee, legal, regulatory, tax, accounting, investment or valuation advice or services unless a specific service is expressly identified and lawfully provided. Transferability, eligibility, security, true-sale treatment, investor rights and portfolio economics depend on the governing documents, transaction structure, applicable law and qualified professional review.
Questions for an originate-to-distribute review
- Identity: Which exact loan or exposure is being packaged?
- Borrower: Who owes the obligation?
- Current balance: What is outstanding today?
- Terms: Which agreement and amendments are current?
- Performance: Is the asset performing?
- Covenants: Are any breaches or waivers active?
- Collateral: What supports repayment?
- Priority: Where does the claim rank?
- Guarantee: Which support rights exist?
- Transferability: Can the asset be assigned or participated?
- Consent: Whose approval is required?
- Eligibility: Which portfolio rules apply?
- Evidence: What supports each eligibility test?
- As-of date: When was the data last reconciled?
- Portfolio: Which pool contains the asset?
- Membership: When did it enter the pool?
- Substitution: Can it be removed or replaced?
- Servicing: Who continues to manage the borrower relationship?
- Cash flow: Where do payments go after transfer?
- SPV: Which vehicle holds the exposure?
- Tranche: Which securities depend on the asset pool?
- Insurance: Which risk-transfer contracts apply?
- Reporting: Which investor report reflects the current state?
- Provenance: Can every field be traced to a source?
- History: Can the asset still be understood after several portfolio transfers?
If the answer to “can another institution understand this asset without reconstructing the original deal from scratch?” is no, the asset is not operationally portable.
Build continuity across successive issuances
The same problem appears in: private credit, SME loans, infrastructure loans, mortgage portfolios, equipment finance, receivables, trade finance, consumer credit, NPL portfolios, and other private debt. Institutional capital can access these markets more easily when the underlying assets have durable identities and comparable current-state data. The World Bank’s latest mobilisation numbers are impressive. But the deeper lesson is structural. Large pools of capital do not scale by reading one bespoke project file at a time. They scale when private assets can be identified, compared, qualified, pooled, transferred and monitored without losing their underlying history.
An asset class is not created merely because many similar loans exist. It is created when those loans can be represented consistently enough to move through institutional workflows.
That is why private assets need to become portable before they become scalable.