 Insights
The Invoice Exists. The Receivable May Not: What Radiant World Reveals About Trade-Finance Asset Identity
The widening Radiant World disputes show why an invoice is not enough to establish a financeable receivable. In one Singapore lawsuit, Incomlend alleges that it advanced $31.7 million against two Glencore invoices with a combined face value above $34 million, only to be told later that the invoices had already been paid and that the underlying contracts were not genuine. Separately, a Jefferies-linked fund has obtained a London freezing order of up to $499 million against Radiant World, its...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
An invoice usually identifies the seller and buyer, invoice number, issue date, currency, amount, due date, payment instructions and the goods or services supplied. It can be uploaded, scanned, entered into a financing platform, shown to a lender, digitally signed, tokenised or reconciled against another system. None of those operations establishes that it still represents a current receivable. That distinction has become unusually visible in the widening disputes around Singapore-based commodity trader Radiant World. In one Singapore High Court claim, invoice-finance provider Incomlend alleges that it advanced $31.7 million in May 2026 against two invoices issued to Glencore International AG with a combined face value of more than $34 million.
According to reporting on Incomlend’s court filing, the invoices were represented as unpaid amounts due from Glencore. When Incomlend later approached Glencore for payment in August, the claimant says it was told that the invoices had already been paid and that the underlying contracts were not genuine. The filing also alleges discrepancies involving payment terms, bank-account details and shipment information. Bloomberg Law: Radiant World Sent Lender Fake Glencore Deals, Lawsuit Says The Business Times: Radiant World and its founder sued in Singapore for US$34 million Radiant World has previously denied wrongdoing and said that it conducts its business to high commercial and legal standards. The allegations have not been finally adjudicated.
Separately, the legal and financing pressure around the group has become much larger. A Jefferies-linked fund, LAM Trade Finance Group II, obtained a freezing order from London’s High Court against Radiant World, its founder Pinkesh Nahar, Sapphire Minmetals and its chairman Rakesh Sethi. Reuters reported on 5 September that the fund had nearly $500 million of exposure to Radiant World, Nahar and another entity, while the Financial Times reported a freezing order of up to $499 million. Reuters: Jefferies-linked fund secures freezing order against trader Radiant World Reuters: Jefferies-linked fund has almost $500 million exposure to trader Radiant World Those proceedings should not be collapsed into one transaction.
The Incomlend financing and the Jefferies-linked exposure are different. The legal claims are different. The documents are different. The counterparties and financing structures may be different. But they point toward the same infrastructure question:
What evidence is required before an invoice can safely be treated as a current, owned and financeable receivable?
The answer is much more than the invoice itself. The specialist records and lifecycle models below describe review requirements and illustrations. They should not be read as claims that software has verified the rights or that every proposed field and relationship is an existing DaDepo feature.
The document and the current payment right are different records
A commercial invoice usually records what the seller says is payable. It provides useful evidence without independently proving every fact required for financing. A simplified trade chain might look like:
- Purchase agreement / purchase order
- Goods or services supplied
- Delivery / performance
- Buyer obligation arises
- Invoice issued
- Receivable outstanding
- Payment
The invoice sits inside that chain. It is not the whole chain. A financier may need evidence that: the relevant seller exists; the buyer exists; the underlying transaction exists; goods or services were actually supplied; the invoice corresponds to that transaction; the buyer is the correct obligor; the amount is correct; the amount has not been adjusted; the receivable remains unpaid; the seller still owns it; it has not already been assigned or pledged elsewhere; payment has not already been redirected; there is no material dispute or set-off; and the financing documents create the intended rights. The existence of a PDF cannot answer all of those questions.
The most important lesson from the Incomlend allegations is not necessarily document forgery. It is the alleged payment-state mismatch. Suppose a supplier issues a genuine invoice:
| Illustrative record field | Description or value |
|---|---|
| Invoice reference | Invoice 123 |
| Face amount | $20m |
| Buyer | Company B |
| Due date | 30 June |
The buyer then pays the supplier on 15 June. The invoice document does not cease to exist. Its number remains valid. Its historical face amount remains $20 million. The underlying trade may have been completely genuine. But on 16 June: “Current receivable balance = $0”. A lender shown only the original invoice could therefore see a perfectly authentic historical document describing an obligation that is no longer outstanding. That is why: “Invoice amount” is not the same field as “Current outstanding amount”. The second field needs a date and evidence. Receivables are not static. They move through states. A simple lifecycle might be:
- Created
- Issued
- Accepted / acknowledged
- Outstanding
- Partially paid
- Paid
Alternative paths can include:
- Outstanding
- Disputed
- Credit note
- Adjusted balance
Another possible path is:
- Outstanding
- Assigned
- Paid to assignee
Another possible path is:
- Outstanding
- Overdue
- Default
- Collection / restructuring
A financing system that stores only: “Invoice status: Issued” may know almost nothing about the current asset. The relevant question is:
What is the payment right now?
An invoice can start at $10 million. Then: $2 million is paid; $500,000 is credited; $250,000 is disputed; and $100,000 is subject to a contractual deduction. The historical invoice still says: “$10,000,000”. The current economic position may be:
| Record | Detail |
|---|---|
| Original invoice | $10,000,000 |
| Less cash received | $2,000,000 |
| Less credit note | $500,000 |
| Disputed amount | $250,000 |
| Other adjustment | $100,000 |
| Nominal remaining balance | $7,150,000 |
Even that does not necessarily equal the financeable amount. The financing agreement may apply reserves, concentration limits or advance rates. Several values therefore need to remain distinct: original invoice amount, current outstanding balance, eligible financed balance, advance amount, current lender exposure and expected recovery. A system with one field called “Amount” cannot represent this safely.
Establish the trade and the scope of buyer confirmation
An invoice usually derives from something. For physical commodities that may include master sale agreement, trade confirmation, purchase order, cargo nomination, shipment, bill of lading, warehouse document, inspection certificate, delivery record, title transfer, price calculation, final invoice, and payment. For services it may instead involve service agreement, statement of work, milestones, timesheets, acceptance, completion certificate, and invoice. For manufactured goods: purchase order, production, shipment, delivery, quality acceptance, returns, and invoice. The receivable is therefore connected to a performance history. The document graph matters. Consider a commodity financing package. The documents may say:
| Source | Information shown |
|---|---|
| Invoice | Cargo A; $18.4m; Vessel Alpha; Payment account X |
| Shipment record | Cargo A; Vessel Beta |
| Underlying contract | Payment account Y |
| Buyer ledger | Invoice already settled |
These records describe different aspects of the same package. Those differences do not automatically prove fraud. There may be legitimate amendments, operational substitutions, document corrections or settlement arrangements. But they are exactly the kinds of discrepancies that should stop the asset from being treated as unquestioned. The correct system response is:
- Mismatch detected
- Source identified
- Review required
not: Invoice PDF received → Asset verified. Most of the documents in an invoice-finance package may originate from the seller. That creates an obvious concentration of evidence. A seller can provide: invoice, contract copy, delivery record, account statement, bank details, payment instructions, and declarations about the balance. Those documents can be genuine copies and still fail to establish the buyer’s current position. A buyer or debtor confirmation can answer a different question: “Does the obligor recognise this obligation?” Depending on the structure and legal context, confirmation may cover: invoice reference, amount, currency, due date, delivery acceptance, dispute status, current balance, payment status, payment account, and notice of assignment. Buyer confirmation is not magical.
It can itself be incomplete, mistaken, stale or unauthorised. But it adds an independent evidence source. A message that says: “Yes, invoice is valid.” is only useful if the reviewer knows: who sent it; which legal entity they represent; whether they are authorised; which communication channel was used; whether the address or account was independently verified; which exact invoice was confirmed; what exactly was confirmed; and when the confirmation occurred. A confirmation from “[email protected]” cannot safely be treated the same as a verified response through an established buyer channel. The confirmation itself therefore needs provenance. A useful confirmation record could distinguish:
confirmation of invoice existence, goods received, the amount, absence of dispute, outstanding balance, acknowledgement of assignment notice and payment instructions. These are not identical statements. A buyer can say: “Yes, we bought the goods.” while also saying: “But we already paid the invoice.” The underlying trade may therefore be real while the financeable receivable is gone. That distinction is central to the Radiant World / Incomlend allegations as publicly reported.
Separate ownership, financing and receivable identity
Even an authentic and unpaid receivable may not belong to the party offering it for financing. The receivable may already have been: sold, factored, assigned, pledged, participated, securitised, transferred into an SPV, subjected to a floating charge, included in another borrowing base, or otherwise encumbered. The financier therefore needs to answer: “Does the receivable exist?” and separately: “Who owns it?” and separately: “Who has security or economic rights over it?” These questions can have different answers. Suppose Supplier A has a $5 million receivable against Buyer B. Supplier A may:
- remain legal owner;
- grant Lender X security over receivables;
- sell a participation in the economics to Fund Y;
- appoint Servicer Z to collect;
- direct Buyer B to pay a controlled account.
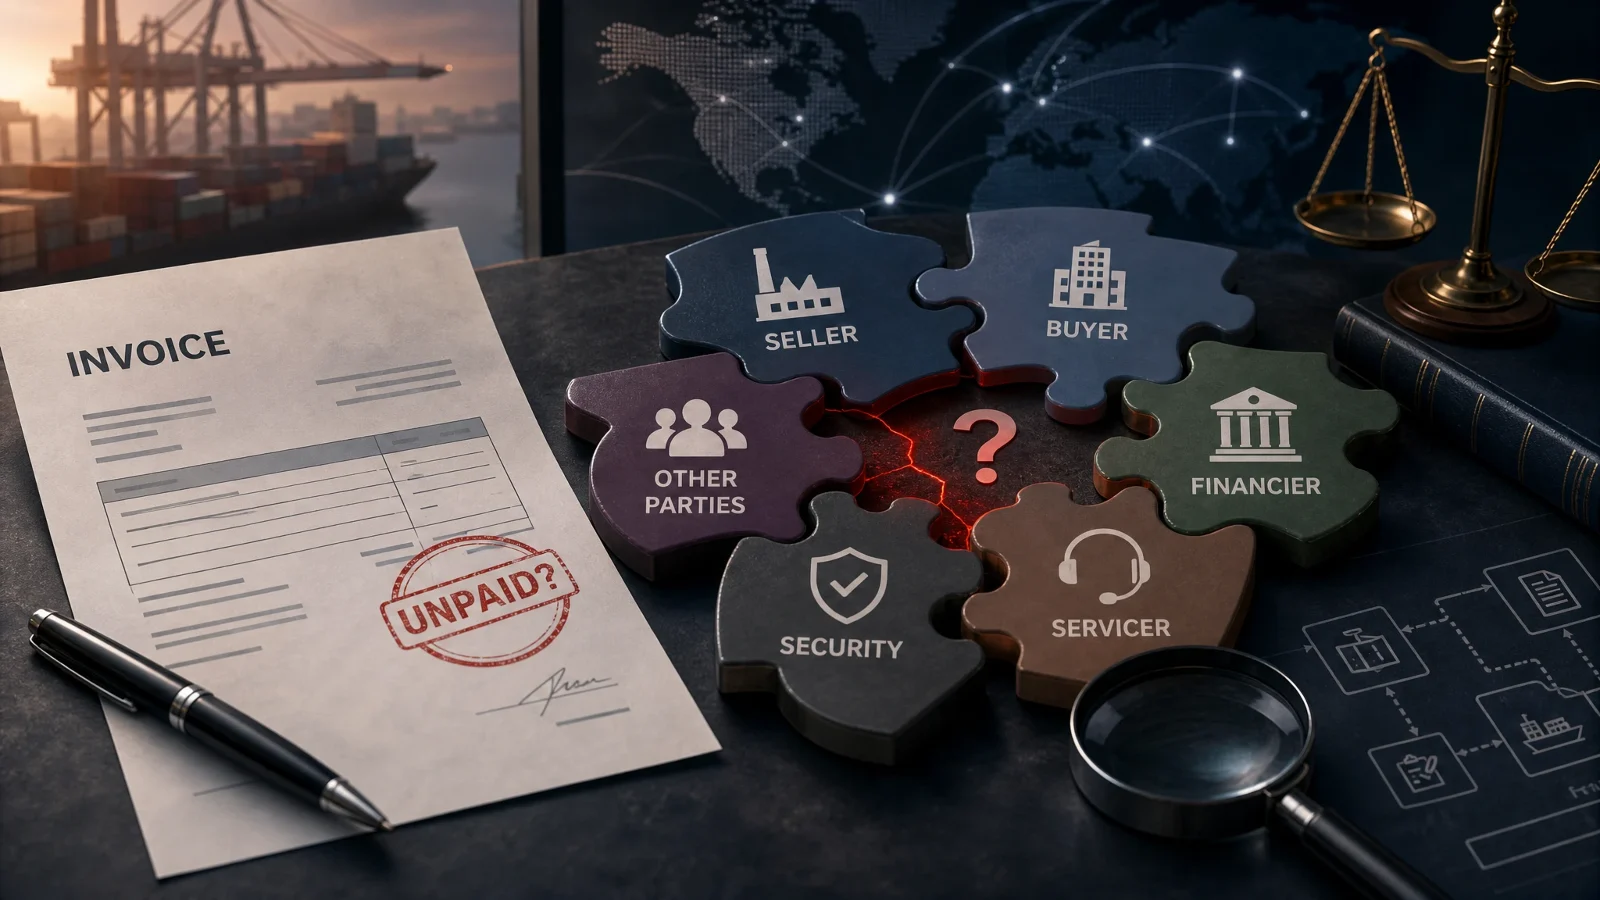
The asset map becomes:
- Receivable
- Legal owner: Supplier A
- Secured party: Lender X
- Economic participant: Fund Y
- Servicer: Servicer Z
- Payment account: Controlled Account
A simple field called “Owner: Supplier A” does not reveal the whole financing state. The classic fear in invoice finance is that the same receivable is financed twice. A simplified example: Receivable R-100 → Pledged to Lender A. Then the same invoice is presented to “Lender B”. If neither lender sees the other relationship, both can believe they have financed the same payment right. But duplicate-financing detection is not merely document hashing. Two PDFs can differ visually while representing the same underlying receivable. Conversely, one invoice can legitimately generate multiple financing interests in a structured transaction. The key object is the receivable identity.
A useful duplicate check may need to combine: seller, buyer, invoice number, purchase-order reference, invoice date, amount, currency, shipment reference, underlying contract, due date, assignment history, and financing relationships. The question is not:
Have we seen this PDF before?
It is:
Have we seen this payment right before?
The identity of a receivable should survive document replacement. Suppose an invoice is corrected. Version 1 of Invoice 2026-481 states $12.5m; Version 2 states $12.3m. The first file may be superseded. The underlying receivable relationship continues. A durable record should preserve:
- Receivable ID
- Invoice v1
- Correction
- Invoice v2
not create two unrelated assets.
Keep payment, allocation, credits and disputes current
Invoice finance often depends on where the debtor will pay. Bank-account information can appear in: invoice, assignment notice, factoring notice, servicing letter, email amendment, settlement instruction, or buyer portal. A change from “Account A” to “Account B” can be completely legitimate. It can also be critical. A robust record should preserve: previous account, new account, effective date, reason, source, approver, buyer acknowledgement where relevant, financier approval where required, and superseded instruction. The system should not silently overwrite the old bank details. A receivable cannot safely remain “outstanding” forever merely because nobody updated the finance platform.
Payment can be evidenced by different sources: debtor statement; bank transaction; controlled-account receipt; servicer record; reconciliation file; remittance advice; ERP ledger; payment-service confirmation; or another authoritative source defined by the transaction. Each source has different reliability. The record should therefore answer:
- Payment claimed?
- Payment observed?
- Payment reconciled?
- Payment final?
- Applied to which receivable?
- As of when?
- According to which source?
This is especially important where one cash receipt covers multiple invoices. A buyer may pay: “$20m” against an account containing: Invoice A for $7m, Invoice B for $8m and Invoice C for $9m. The payment does not by itself say which invoices are extinguished.
The allocation may follow: remittance advice, contractual rules, debtor designation, creditor allocation, automated reconciliation, or later manual correction. A receivable can therefore remain apparently outstanding because the cash exists but has not yet been allocated correctly. This is another reason to distinguish “Cash received” from “Receivable settled”. A buyer may return goods. A seller may grant a rebate. Quantity may be adjusted. Quality may be disputed. A pricing formula may be recalculated. The original invoice may remain intact in the archive. But a credit note changes the receivable. A lifecycle might look like:
- Invoice issued: $10m
- Credit note: $1m
- Current gross receivable: $9m
If the financier sees only the original invoice, the asset is overstated. A disputed receivable is not the same as a paid receivable. It is not the same as an undisputed performing receivable either. A dispute record may need disputed amount, undisputed amount, reason, opening date, parties, supporting evidence, contractual process, current status, resolution, credit note, settlement, and effective date. The financeable balance may change while the dispute remains open.
Connect the legal entities and financing arrangements
Commodity trading often combines: high transaction values, fast movement, multiple legal entities, short financing cycles, physical cargo, hedging, letters of credit, bilateral credit, inventory finance, receivables finance, title documents, shipping documents, and multiple banks or funds. That creates many legitimate documents. It also creates many places where one transaction can be misunderstood. Radiant World is a particularly large example. Reuters reported in August that the company had 21 creditors with registered claims over its assets, more than double the number before the start of 2025. Reuters: Claims against Radiant World assets have doubled since 2025, filings show The point is not that the existence of multiple creditors implies wrongdoing. It does not.
The point is that once many financing relationships coexist around one trading group, asset identity and encumbrance become harder to manage from isolated deal files. A lender may say: “Exposure to Radiant World: $100m”. That is a useful portfolio number. It does not identify: which legal entity owes the money; which invoices support it; which buyers are expected to pay; which receivables remain outstanding; which assets secure the facility; which receivables have been assigned; which payments have been received; which claims are disputed; or which other lenders may have competing interests. A group-level exposure needs an asset-level map underneath it.
Large trading groups can contain operating companies; holding companies; financing vehicles; affiliates; joint ventures; SPVs; and entities with historic relationships that may no longer reflect current control. A document saying: “Radiant World” is not precise enough for a legal asset record. A receivable record should identify the actual seller entity. It should identify the actual buyer entity. It should identify the financing entity. It should identify any assignor, assignee, security provider or servicer separately. Imagine: a seller named ABC Trading Singapore Pte Ltd. But the financing agreement is signed by: “ABC Trading Holdings Ltd”. Perhaps the holding company has authority. Perhaps there is an assignment. Perhaps there is a guarantee. Perhaps there is not.
The system cannot infer the legal relationship from the shared brand name. Entity precision matters. Even if the receivable is valid, unpaid and owned by the seller, the financier still needs its own rights. Those can arise through outright assignment, factoring, security assignment, charge, pledge, trust, participation, borrowing-base facility, receivables purchase agreement, or another financing structure. The Asset Passport should distinguish “Underlying receivable” from “Financing contract”. The financier’s rights come from the second object interacting with the first.
Date the assignment, priority and verification evidence
In some structures, the debtor is notified that the receivable has been assigned. That event can affect: payment instructions, discharge mechanics, set-off, perfection, priority, servicing, confidentiality, and enforcement. The exact legal effects depend on jurisdiction and contract. From an infrastructure perspective, notice should be an event:
- Assignment created
- Notice prepared
- Notice delivered
- Delivery evidence
- Debtor acknowledgement where applicable
A single “Assigned: Yes” field cannot preserve that sequence. If two financiers claim rights over the same receivable, the fact that one uploaded its document first to a platform means nothing about legal priority. Priority can depend on governing law, transaction structure, assignment timing, notice, registration, perfection, contractual subordination, possession or control where relevant, insolvency rules, and other legal factors. DaDepo can preserve the evidence. It should not invent the legal conclusion. This is perhaps the most important design principle. A system should distinguish invoice upload, field extraction and linking of underlying documents from receipt of buyer confirmation, confirmation of payment state, ownership review and financing-state review. Those states represent different levels of evidence.
The first should never silently become the last. Suppose the seller states that an invoice remains unpaid while the buyer states it was paid on 12 May. Preserve both positions with their sources and statement dates, then require reconciliation:
| Statement | Source | Date and review need |
|---|---|---|
| A: Invoice remains unpaid. | Seller | Record the statement date; reconcile against payment evidence. |
| B: Invoice was paid on 12 May. | Buyer | Record the statement date separately from the claimed payment date. |
This is exactly the type of problem where provenance is more valuable than a single “truth” field. Receivables change quickly. A statement can be accurate on Monday and wrong on Friday. Therefore: “Outstanding: Yes” is incomplete. The system needs an outstanding balance of $4.2m as of 5 September 2026 10:00 UTC, sourced to servicer reconciliation, or another clearly identified source.
Time is part of the state. A platform may describe an invoice as verified. That word can mean many things. It may mean: file integrity checked, seller identity checked, buyer identity checked, invoice number matched, duplicate-document check passed, purchase order matched, delivery evidence found, debtor confirmation received, outstanding balance confirmed, bank account verified, ownership reviewed, assignment reviewed, or payment status reconciled. Those are different checks. A useful record should say: who checked what, against which source, on what date, with what result and with what limitations. The label: “Verified invoice” is too broad.
Keep the allegations and the proposed controls distinct
The publicly reported Incomlend allegations are useful because they illustrate several distinct problems at once.
1. Underlying-transaction problem
The claimant says Glencore told it that underlying contracts were not genuine. That goes to the source transaction.
2. Payment-state problem
The claimant says Glencore told it that the invoices had already been paid. That goes to the current receivable balance.
3. Document-consistency problem
The court filing reportedly identifies discrepancies in payment terms, bank details and shipment information. That goes to reconciliation and provenance. Even if one of these checks succeeds, another can fail. That is why invoice finance cannot rely on one verification step. A receivable can be represented as a graph:
- Seller
- Underlying contract
- Purchase order / trade confirmation
- Shipment / performance
- Invoice
- Buyer obligation
- Current balance
- Ownership / assignment
- Financing
- Payment account
- Payment events
Each node has evidence. Each relationship can change. That is much stronger than a folder containing: three unconnected files named invoice.pdf, contract.pdf and shipping.pdf
Preserve the lifecycle, failed checks and historical record
For DaDepo, this is a strong example of why a receivable should be treated as a structured, time-aware asset rather than a document type.
Asset identity
Internal receivable ID, seller legal entity, buyer legal entity, invoice number, invoice date, currency, original face amount, due date, purchase-order or contract reference, shipment or performance reference, jurisdiction, governing law where relevant, and current lifecycle state.
Underlying transaction
Master agreement, purchase order, trade confirmation, goods or services description, quantity, price basis, delivery terms, shipment, vessel or transport reference where relevant, delivery evidence, acceptance, inspection, title evidence where relevant, and amendments.
Invoice record
Invoice document, invoice version, issue date, amount, currency, due date, payment terms, bank details, tax treatment where relevant, corrections, replacement invoices, credit notes, and superseded versions.
Current balance
Original amount, payments received, payment dates, partial payments, credit notes, deductions, disputes, set-off, remaining balance, balance source, reconciliation status, and as-of timestamp.
Buyer confirmation
Confirmation request, recipient, verified buyer identity, authority, communication channel, invoice confirmed, amount confirmed, balance confirmed, dispute status, payment status, assignment acknowledged where relevant, bank details confirmed where relevant, and confirmation timestamp.
Ownership
Original creditor, current legal owner, assignment, assignee, transfer date, retained interest, participation, trust relationship, security interest, financing vehicle, servicer, and current entitlement.
Financing
Financier, financing agreement, structure, commitment, advance, advance rate, eligible balance, financed amount, borrowing-base inclusion, security, concentration treatment, recourse, repayment, current exposure, and release.
Duplicate / competing-interest review
Same receivable detected elsewhere, similar invoice number, same buyer, same seller, same shipment, same contract, same amount, prior assignment, prior pledge, existing charge, other financing relationship, reviewer, and resolution.
Payment
Expected payer, expected account, remittance advice, bank or provider reference, cash receipt, receipt timestamp, allocation, reconciliation, shortfall, overpayment, payment reversal, return, final settlement state, and source.
Dispute and adjustment
Dispute opening date, disputed amount, reason, buyer position, seller position, evidence, credit note, negotiated adjustment, resolution, resolved balance, and close date.
Provenance
Source document, source system, seller-provided evidence, buyer-provided evidence, financier record, bank or payment record, servicer source, registry source, AI-extracted field, user-confirmed field, professional review, effective date, version, and last updated timestamp. This turns an invoice package into a traceable receivable record. If a buyer confirmation fails, that is useful information. If the buyer cannot identify the invoice, that matters. If the amount differs, that matters. If the payment account differs, that matters. If the invoice was already paid, that matters. The system should not simply remove the asset and discard the evidence. It should record: the check performed, its result, source and date, the exception and its resolution. Failed checks are part of the asset history.
A paid invoice can still have historical value. The record may need to show:
| Record | Detail |
|---|---|
| Invoice issued | 1 May |
| Historical outstanding amount | $34m |
| Payment received | 20 May |
| Current balance | $0 |
The statement: “Invoice amount = $34m” remains historically true. The statement: “Receivable outstanding = $34m” is no longer true. Good asset infrastructure keeps both.
Tokenisation, AI and the bounded DaDepo contribution
Putting an invoice or receivable on-chain does not solve the state problem. A token can represent: “Invoice 123” very reliably. But if Invoice 123 was paid yesterday and the token still represents the original face value today, the ledger has preserved stale information perfectly. The same is true for digital registries, blockchain, data rooms, securitisation platforms, marketplaces, and AI extraction. Better technology does not remove the need for current external evidence. It makes the quality of the state model more important.
AI-assisted preparation
The analytical uses discussed here are possibilities for document review, subject to source access and human judgement. They are not a claim that DaDepo currently performs every proposed check or reaches the resulting legal or financial conclusions. Invoices are attractive AI documents. They are structured. They contain repeated fields. AI can extract: invoice number, seller, buyer, amount, currency, dates, payment terms, purchase-order reference, bank details, and line items.
Across a document package, AI can also help identify: inconsistent buyer names, conflicting amounts, different payment terms, duplicate invoice references, conflicting bank details, missing contracts, mismatched shipment references, absent delivery evidence, credit notes not reflected in balances, payments not reflected in current state, multiple assignments, missing buyer confirmations, and stale status dates. That is useful.
AI should not independently conclude: that the underlying trade occurred; that a contract is genuine; that goods were delivered; that the buyer accepted them; that an invoice is enforceable; that the receivable remains unpaid; that the seller still owns it; that no other financier has rights over it; that a bank account is controlled by the correct party; that an assignment is legally effective; that priority is established; that an alleged discrepancy proves fraud; that a buyer confirmation is legally sufficient; or that the receivable is suitable for financing. Those are questions of external evidence, legal effect, credit and professional judgment.
DaDepo can help prepare a private document-backed asset draft and retain source-linked information for human review. The private Parties and contractual roles table can record source-described party, contract and role rows with document and clause references, optional source dates, and pending, confirmed or rejected review decisions. The same party can appear in different contracts and roles. Where current compatible completed analysis is available, AI may suggest pending role rows; a user reviews and confirms or rejects them. These records do not establish legal title, priority, enforceability, the validity of a reported exposure or the outcome of a dispute.
The specialist information model for receivables is a proposed information requirement. A complete relationship graph, automatic exposure reconciliation and automatic cross-contract decisions are not delivered capabilities established by this article. DaDepo does not need to become an invoice-finance lender. It does not need to decide whether a receivable is creditworthy. The useful role is information infrastructure. A proposed specialist workflow could help organise the relationship:
- Invoice
- Underlying transaction
- Buyer
- Current balance
- Ownership
- Financing
- Payment evidence
- Current state
The proposed model could make several important questions visible before a reviewer relies on the asset. For example:
- Is the invoice linked to the underlying contract?
- Is shipment or performance evidence available?
- Has the buyer been identified correctly?
- Has the current outstanding amount been updated?
- Are credit notes reflected?
- Has the receivable already been financed?
- Is there another assignment or security interest in the file?
- Have payment instructions changed?
- Is there independent payment evidence?
- Are conflicting statements preserved with provenance?
- When was the asset state last confirmed?
The objective is to make the evidence, relationships, current state and unresolved questions clear enough for an authorised reviewer to assess. Preparation must not be presented as DaDepo declaring the receivable legally valid.
Creating or reviewing a receivable Asset Passport does not mean that DaDepo has authenticated every invoice; established that the underlying contract is genuine; confirmed that goods or services were supplied; confirmed delivery or acceptance; established that the debtor legally owes the amount; confirmed the current balance; confirmed that the invoice remains unpaid; independently contacted or verified the buyer; authenticated a buyer confirmation; confirmed ownership of the receivable; confirmed that the receivable has not been assigned or pledged elsewhere; established legal priority; perfected a security interest; confirmed bank-account ownership; monitored a bank account; guaranteed payment; provided factoring or invoice discounting; provided a lending decision; performed underwriting; investigated suspected fraud; determined that a discrepancy constitutes fraud; provided trade finance; provided legal advice; provided valuation; provided credit ratings; guaranteed recovery; or determined investor suitability.
Important: DaDepo provides technology and information tools. It does not provide legal, financial, banking, factoring, trade-finance, investigation, underwriting, valuation, investment or credit advice or services unless a specific service is expressly identified and lawfully provided. The existence, enforceability, ownership, transferability, priority and payment status of a receivable depend on the relevant transaction, evidence, governing documents, external records and applicable law.
Questions for a receivable-state review
Before an invoice is treated as a financeable receivable, ask:
- Seller: Which exact legal entity issued the invoice?
- Buyer: Which exact legal entity is expected to pay?
- Underlying transaction: Which contract, purchase order or trade confirmation created the obligation?
- Performance: What evidence supports shipment, delivery, service completion or other performance?
- Invoice: What is the exact invoice number, amount, currency and date?
- Version: Has the invoice been amended, replaced or corrected?
- Buyer recognition: Does the buyer recognise the transaction and invoice where confirmation is part of the process?
- Current balance: What remains outstanding today?
- As-of date: When was that balance last confirmed?
- Payment: Has any amount already been paid?
- Allocation: Has received cash been correctly allocated to the invoice?
- Adjustments: Are credit notes, returns, rebates, discounts and set-offs reflected?
- Dispute: Is any part of the amount disputed?
- Ownership: Who currently owns the receivable?
- Assignment: Has it been sold, assigned, participated or transferred?
- Security: Has it been pledged or charged to another financier?
- Duplicate financing: Does the same payment right appear in another financing package?
- Notice: Has the buyer received any assignment or payment-direction notice required by the structure?
- Payment account: Which account should receive the payment, and what supports that instruction?
- Account change: Have any bank details changed since origination?
- Financing: Which financier has advanced against the receivable and how much?
- Current exposure: What financing remains outstanding against it?
- Provenance: Can each material field be traced to a source?
- Conflict: Are contradictory seller, buyer, bank or servicer records visible rather than overwritten?
- Review: Which checks remain unresolved?
If the answer to “does this payment right exist, who owns it, and how much is still payable now?” is unclear, the asset is not ready to be treated as a reliable receivable.
The broader lesson from the dispute
Commodity finance has seen document disputes before. Invoice finance has seen duplicate financing before. Banks have financed receivables that later became disputed, paid, assigned or difficult to collect before. The Radiant World developments matter because they bring several of those risks together at institutional scale. The market can have major counterparties, sophisticated lenders, large funds, established trading relationships, expensive legal documentation, and professionally produced transaction files. The core asset question can still remain unresolved. That question is not: “Do we have an invoice?” It is: “What payment right exists now?” The distinction is fundamental. An invoice may be genuine. The trade may be genuine. The buyer may be genuine. The receivable may have existed.
And yet the current balance may be zero. Or the receivable may belong to somebody else. Or another financier may already have rights over it. Or the transaction may be disputed. Or the documents may not describe the same trade at all. That leads to a broader rule for private-asset infrastructure:
A document can prove that something was recorded. A financeable asset requires evidence of what right exists now.
For receivables, the current state matters as much as the original invoice. That is why the asset needs an identity, a lifecycle and provenance—not just a PDF.
Further reading
- Bloomberg Law: Radiant World Sent Lender Fake Glencore Deals, Lawsuit Says
- The Business Times: Radiant World and its founder sued in Singapore for US$34 million
- Reuters: Jefferies-linked fund secures freezing order against trader Radiant World
- Reuters: Jefferies-linked fund has almost $500 million exposure to trader Radiant World
- Reuters: Claims against Radiant World assets have doubled since 2025, filings show
- Reuters: Mizuho Bank files case against Radiant World in Singapore
- Singapore Court of Appeal: UniCredit Bank AG v Glencore Singapore Pte Ltd [2023] SGCA 41