 Insights
An Insured Invoice Is Still Not a Verified Receivable: What Radiant World Reveals About Trade-Credit Evidence
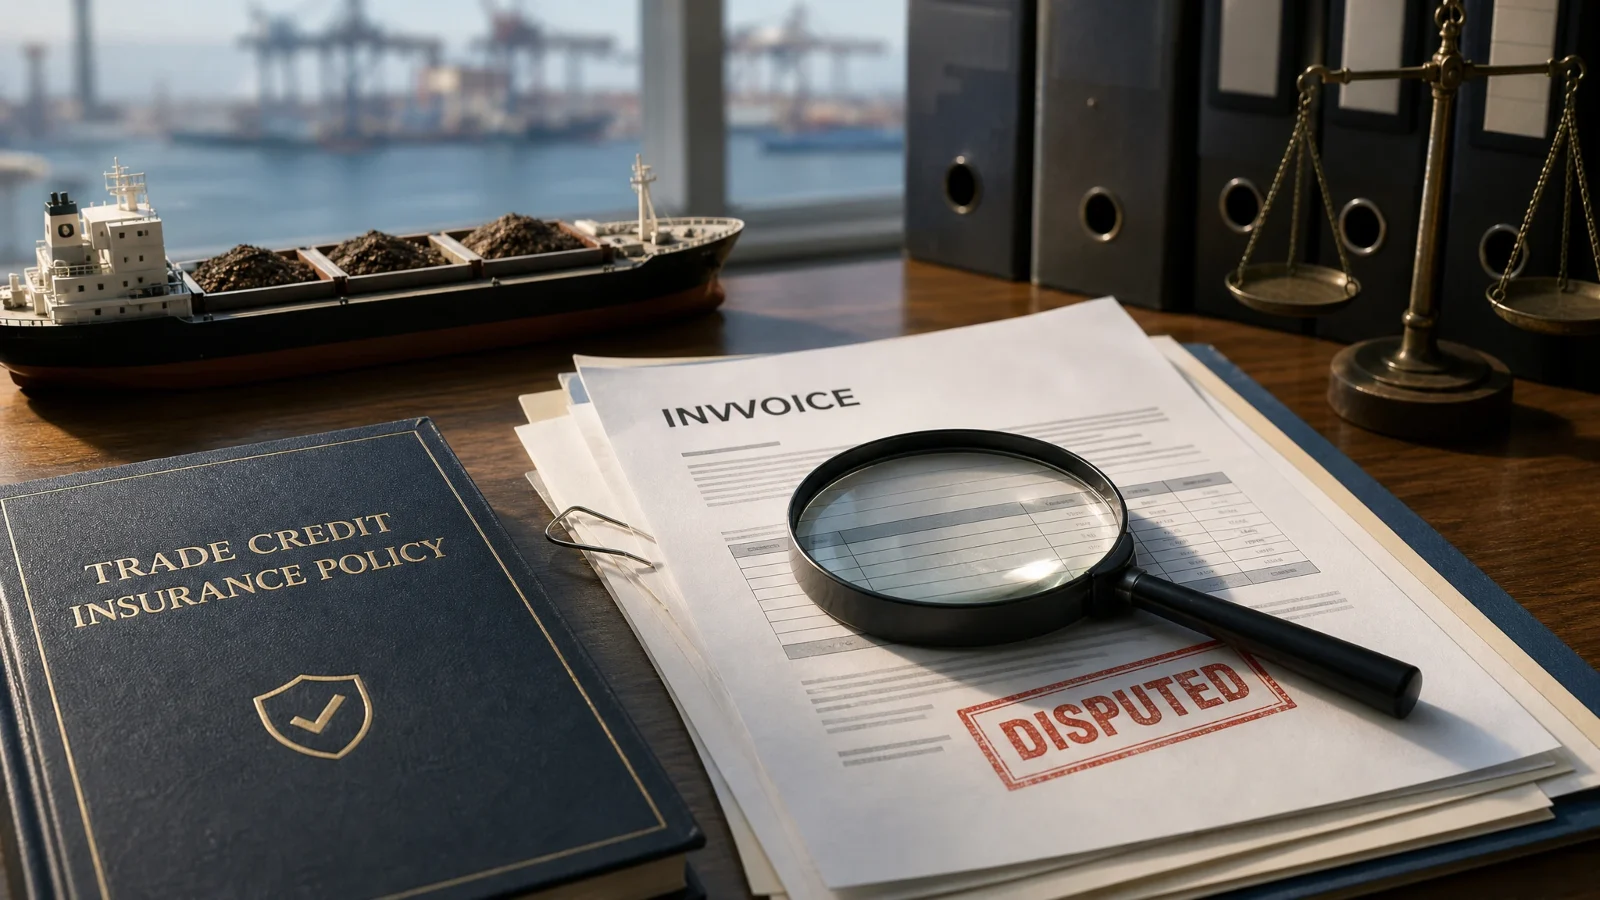
The Radiant World disputes have moved beyond lenders and commodity counterparties into trade-credit insurance. The Financial Times reported that Zurich and Allianz Trade wrote policies covering transactions linked to the embattled iron-ore trader, including Zurich cover tied to non-payment by counterparties such as Glencore. That adds a new layer to a case already involving allegations that some invoices used in financing were invalid or had already been paid. The lesson is not that...
This starts a temporary private draft. It is not public, listed for sale or shared automatically.
Trade-credit insurance can protect against defined non-payment risks without establishing that a particular invoice still represents a genuine payment right. The policy, underlying trade, current receivable, financing and any insurance claim are separate layers of evidence.
On 11 September 2026, the Financial Times reported that Zurich and Allianz Trade had insured transactions linked to Radiant World, the Singapore iron-ore trader facing UK and Singapore claims involving allegedly fraudulent trade documentation. It described Zurich policies in the double-digit millions of dollars covering non-payment by several counterparties, including Glencore, and a smaller Allianz Trade exposure. Zurich said it had no material exposure to Radiant. Reuters also reported the FT account. These reported exposures are not established indemnities or findings that an insurer must pay. Financial Times, Reuters
The added insurance layer makes one question particularly important: what genuine payment right is the cover protecting if the underlying receivable is disputed?
The policy and the payment obligation have different foundations
A buyer's payment obligation arises from the governing trade, performance and applicable terms; insurance does not create it. An invoice records a claim, and a policy may then cover defined risks associated with that receivable. A genuine insurance agreement can coexist with a dispute over the invoice, an already-paid balance, buyer liability or whether the trade occurred.
Allianz Trade's July 2026 guidance distinguishes credit insurance for genuine customers failing to pay genuine receivables from fraud scenarios without a genuine debtor or receivable. The distinction is between a real debt going unpaid and a purported payment right not existing as represented. Allianz Trade: Fraud and trade-credit cover
For example, a genuine $10 million receivable following buyer insolvency presents a different issue from a $10 million invoice with a current balance of $0 because payment already occurred. A buyer who never entered the purported contract raises another question again. A real company name, invoice file and insurance product cannot settle those differences.
The Radiant proceedings remain allegations and separate processes
Before the insurance reporting, Reuters described a London freezing order obtained by Jefferies-linked LAM Trade Finance Group II against Radiant World, founder Pinkesh Nahar, Sapphire Minmetals and chairman Rakesh Sethi, followed by a Singapore injunction request. Reuters: London proceeding, Reuters: Singapore request
Radiant World denied wrongdoing, and the proceedings remained unresolved in the source account. Insurance reporting does not prove the allegations or determine policy liability. It shows that another institutional relationship may depend on evidence from the same trade ecosystem.
Nor does the presence of Glencore or another strong counterparty name prove that the company entered the exact transaction or still owes that balance. Buyer credit analysis and transaction verification answer different questions.
Current balance, ownership and coverage need separate histories
An illustrative $20 million invoice issued on 1 May, paid in full on 20 May, remains a historically genuine invoice with a $0 current balance. Entering its face value as a current $20 million receivable after settlement would misstate the asset without making the original document false.
A receivable can also be owned by the seller, assigned, pledged, participated, sold to an SPV, transferred into a fund or otherwise encumbered. Following a claim payment, an insurer may have recovery rights. The exact ownership, security and recovery relationships come from documents and law.
Coverage has its own progression: policy issue, approved buyer or credit limit, qualifying trade, covered receivable, overdue event and notification, claim, coverage review, acceptance/dispute/rejection, then indemnity, litigation or closure. Buyer-limit approval does not establish that every invoice to that buyer is valid or insured; timing, performance, contract terms, payment periods, notification and other policy conditions can still apply.
For an illustrative $10 million balance with 90% cover, $9 million is a simple theoretical covered amount, not guaranteed claim value. Deductibles, waiting periods, limits, exclusions, recoveries, disputes, fraud allegations, compliance and adjudication can affect the outcome. Receivable amount, claimed amount and cash indemnity received are separate quantities.
Submitted, investigating, partially accepted, reserved, disputed, denied, litigated and settled are likewise different claim states. A later buyer dispute should remain visible alongside earlier facts that an invoice existed, a policy was issued and financing was funded, potentially with coverage under review. Those earlier events should not be overwritten.
Build the evidence chain from performance through claim handling
A commodity file may contain purchase and trade confirmations, cargo nomination, bill of lading, warehouse and vessel information, inspection, customs, delivery and invoice records. Each supports part of the transaction without necessarily proving the entire payment obligation.
Debtor confirmation, where obtained, should identify the seller, contract, invoice and amount, due date, delivery, current balance, payment account and relevant assignment or notice. An underwriter may have used seller information, buyer credit data, trade history, turnover declarations, invoices, credit limits, policyholder representations and external sources. A later claim handler may need the contract, delivery, account and payment/collection histories, correspondence, buyer response and proof of loss. Preserve the source and scope of each assertion.
| Proposed layer | Information needed for review |
|---|---|
| Trade and performance | Seller/buyer, contract/order/confirmation, product and quantity, price/currency, law/date; shipment, bill, warehouse, delivery/acceptance, inspection, relevant title-transfer evidence and discrepancies. |
| Invoice | Number/date, face amount/currency, due date/terms, parties and bank details, versions/corrections/credits and source. |
| Current receivable | Original and current balance, partial payments, credits/deductions, dispute/set-off, overdue amount, source/as-of date and reconciliation. |
| Buyer evidence | Legal identity, verified contact and confirmation where available, acknowledged amount, payment/dispute state and account, assignment notice, date/source. |
| Ownership and finance | Original creditor/current owner, assignment/pledge, financier and advanced amount, current exposure, collection account, servicer, release and competing interest. |
| Policy | Insurer, insured party, number/period, buyer limit, coverage percentage and risks, maximum payment terms, exclusions, notifications/overdue reporting, amendments and current state. |
| Claim | Event, notification and claim dates, amount/evidence, insurer review and information requests, disputed issue, decision, indemnity and payment, recovery and closure. |
| Provenance | Seller ERP, buyer, shipment and bank records, insurer/financier, court filings and uploads, extracted fields, professional review, effective date/version/update. |
This is a proposed information model for a reviewable package. It is not a claim that DaDepo already has an automated insurance-coverage or trade-verification engine.
Preparation can expose questions without deciding coverage
DaDepo's bounded contribution is private document-backed preparation and reviewable information. Suggested parties, amounts and dates can be checked against the underlying records, while the reviewer describes known inconsistencies and missing evidence.
Future specialised checks could compare invoices with shipments, find apparent payments missing from balances, changed bank details, potential duplicate financing, a policy limit below exposure, omitted credits, inconsistent buyer confirmations or a policy naming another entity. These are proposed checks rather than asserted present automatic functions. Possible issues need human review; they are not findings of fraud.
AI cannot determine genuine trade, buyer liability, delivery, enforceability, fraud, coverage, exclusions or an insurer's duty to pay. A Passport does not authenticate the invoice, confirm the transaction or balance, establish ownership, issue or interpret insurance, approve claims, investigate fraud, act as loss adjuster or guarantee payment. Trade-credit insurance, underwriting, claims adjustment, fraud investigation, lending, factoring, legal, investment and valuation services require their own expressly identified and lawful basis.
Guarantees, letters of credit, surety and credit derivatives create the same need to distinguish risk transfer from the underlying obligation. Risk protection can strengthen finance while leaving asset identity and the current right to payment to be established separately.
Questions for an insured receivable
Trade and current payment right
- Seller: Which legal entity issued the invoice?
- Buyer: Which legal entity is expected to pay?
- Trade: What contract created the obligation?
- Performance: What supports shipment or delivery?
- Invoice: Which exact invoice is being financed or insured?
- Amount: What was the original face amount?
- Balance: What remains unpaid today?
- Payments: Has any amount already been paid?
- Adjustments: Are credit notes reflected?
- Dispute: Does the buyer dispute any part?
- Confirmation: Has the buyer acknowledged the obligation where relevant?
Ownership, exposure and policy
- Ownership: Who owns the receivable?
- Assignment: Has it been sold or assigned?
- Security: Has it been pledged?
- Duplicate finance: Has the same receivable been financed elsewhere?
- Financier: Who has advanced against it?
- Exposure: How much financing remains outstanding?
- Insurer: Which insurer issued the policy?
- Policyholder: Who is insured?
- Buyer limit: What credit limit applies?
- Coverage: What risk is actually insured?
- Terms: What payment terms apply?
- Exclusions: Which exclusions may matter?
Claim and recovery
- Notification: Were required notices made?
- Claim: Has an insurance claim been submitted?
- Claim state: Is it pending, accepted, disputed or denied?
- Indemnity: Has any amount actually been paid?
- Recovery: Does the insurer have recovery rights?
- Provenance: Can each material fact be traced to source evidence?
A real insurer, policy, invoice and named buyer can coexist with a disputed current payment right. The useful record makes each layer and unresolved question visible, so insurance is not mistaken for verification of the underlying asset.